
TMX Group (TSX:X) Following Record Q3 Results Is The Growth Story Fully Valued
TMX Group (TSX:X) just combined record third quarter revenue with a fresh quarterly dividend declaration, giving investors new information on both earnings power and ongoing cash returns as of late October 2026.
That mix of record Q3 revenue, new acquisitions and a fresh dividend seems to be feeding into momentum in TMX Group’s shares, with a 30-day share price return of 13.38% and a 1-year total shareholder return of 18.32% that points to building enthusiasm rather than fading interest.
Scan beyond TMX Group and see how other exchange and financial infrastructure stocks with recent momentum and solid fundamentals stack up inside our hand picked list of solid balance sheet and fundamentals (6 results)
TMX Group just paired record Q3 revenue with a sharp recent share move, which underlines a strong platform. The real work now is figuring out whether that strength is already fully priced in.
Most Popular Narrative: 8% Undervalued
TMX Group closed at CA$60.07, while the most followed narrative pegs fair value around CA$65.43, which implies some remaining upside based on that framework using a 7.28% discount rate.
The accelerating expansion of TMX Group’s Global Insights and Data Analytics division is now reinforced by the RAFI Indices acquisition, which is expected to lift this area to 43% of revenue and be accretive to adjusted EPS within 12 months. This points to a larger share of high margin, recurring income and potentially higher net margins over time.
See why 30 investors see TMX Group as 8% undervalued.
Result: Fair Value of CA$65.43 (UNDERVALUED)
Still, the TMX Group narrative can crack if public issuers keep drifting to private or larger foreign venues, or if blockchain based platforms siphon off trading and clearing activity.
Find out about the key risks to this TMX Group narrative.
Another View: TMX Group Looks Expensive On Earnings
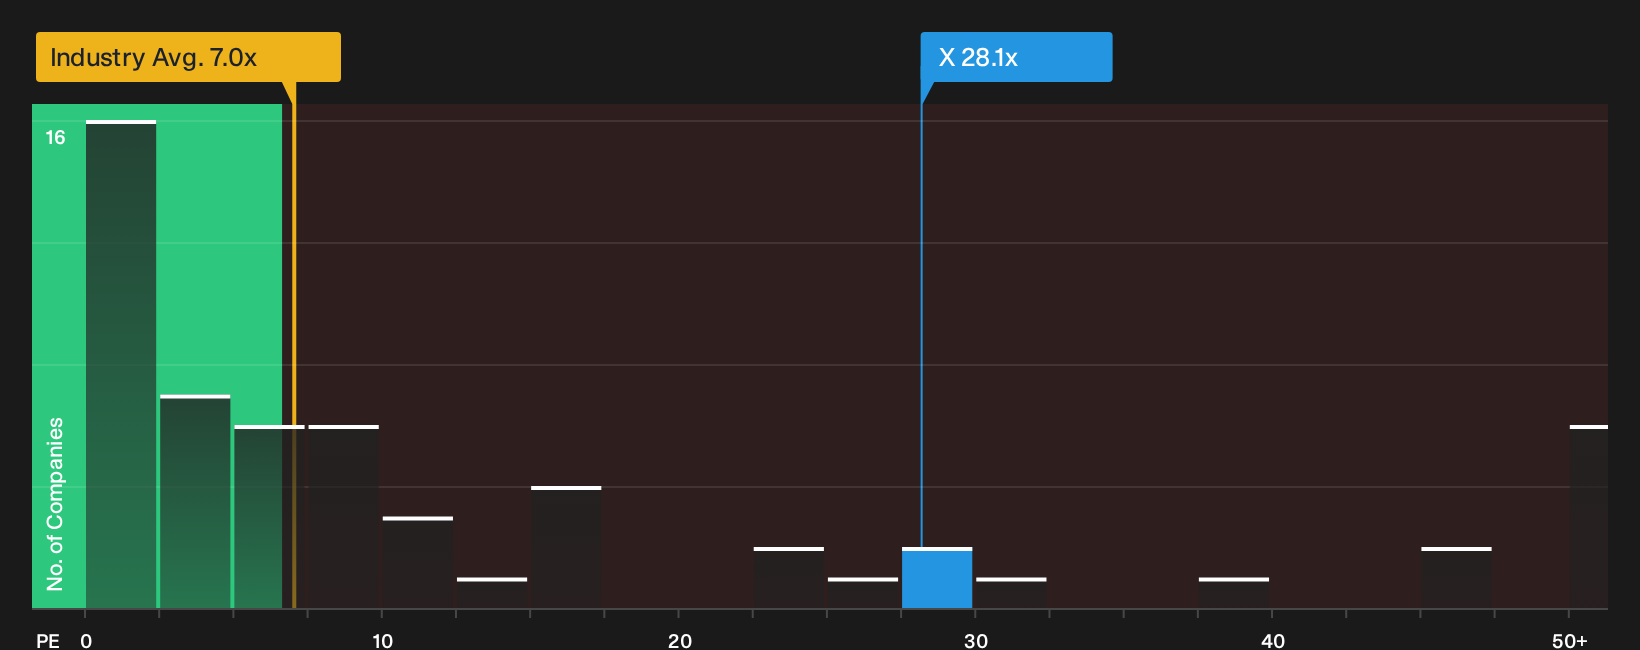
The first narrative leans on a fair value of CA$65.43, yet the current P/E of 28.1x paints a tougher picture for TMX Group. The wider Canadian Capital Markets industry trades at 6.9x, while close peers sit around 20.1x and a fair ratio of 22.6x suggests the multiple could compress. Is the market paying ahead of itself for the story here?
For a closer look at how that premium stacks up against sector norms and what it might mean for future upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether TMX Group’s premium valuation is justified or stretched. Move quickly, review both sides of the story, and weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond TMX Group?
If you stop with TMX Group, you risk missing other opportunities that fit your style, your risk appetite and your income needs just as well.
- Target potential mispriced quality by scanning stocks with strong fundamentals and room for upside using the 3 high quality undervalued stocks.
- Lock in income potential by focusing on companies that pair higher yields with resilience through the 3 dividend fortresses.
- Dial down portfolio stress by hunting for businesses with resilient finances and robust balance sheets via the 7 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com