
Is Western Union (WU) Undervalued As Dividend Pressure Clouds Earnings?
Western Union has seen its shares fall sharply in recent years, while still offering one of the highest dividend yields in the market. That mix of price pressure and income appeal puts the focus squarely on whether the current share price can be justified by the earnings that support it.
- Over the past 5 years the stock has declined 47.8%, which puts past shareholders under pressure and raises the stakes for any assessment of what its earnings are worth today.
- The dividend yield of about 14.9% depends on earnings and free cash flow that currently fall short of recent payout levels, so any strain on cash generation may affect how much value investors should ascribe to those profits.
- The analysts covering Western Union have run their own numbers. See what analysts think Western Union's shares could be worth.
The issue now is whether Western Union's current share price is adequately supported by the earnings power of the business.
If you want a wider lens on income ideas while you research Western Union and its dividend strain, a focused stock screen built around 5 dividend fortresses can be a useful next step.
Is Western Union Still Cheap on Earnings?
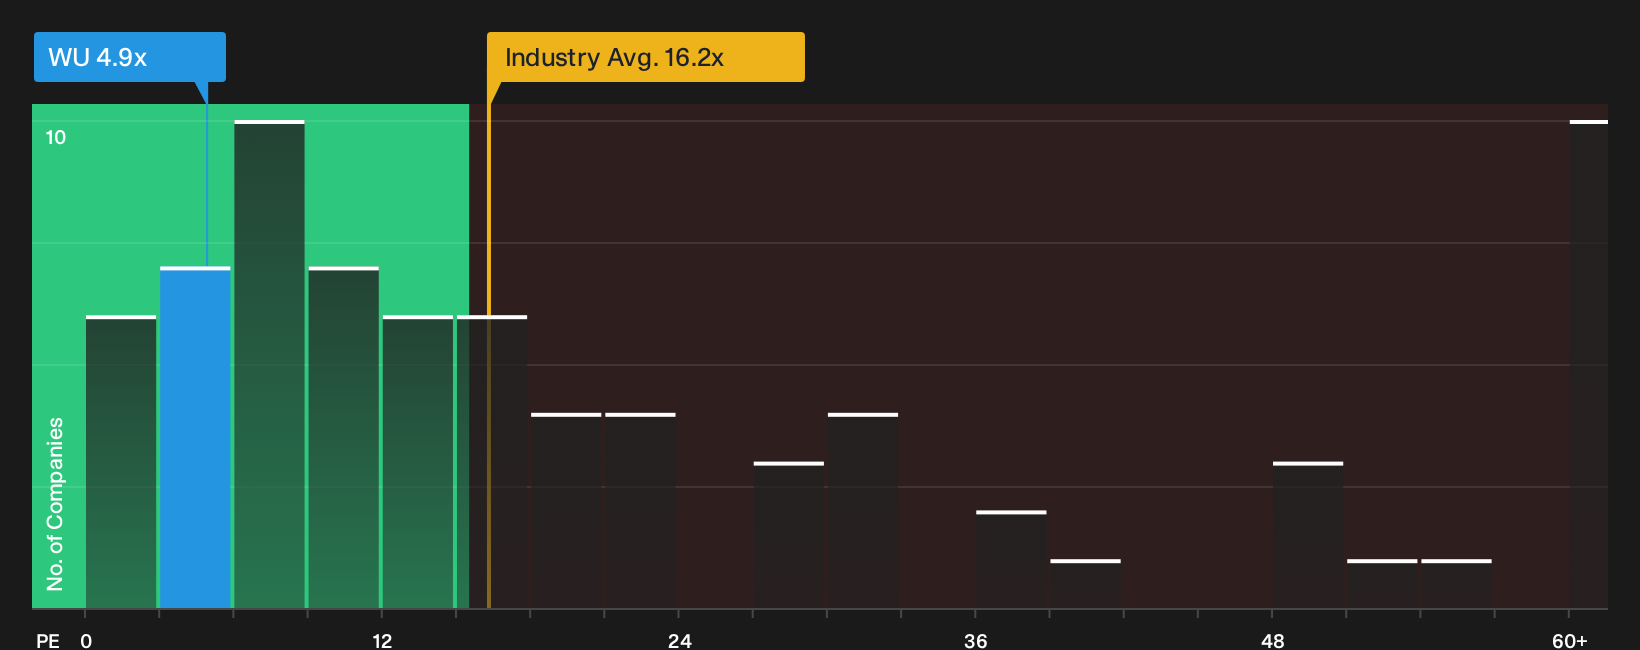
The P/E ratio is a useful lens for Western Union because earnings remain a core driver of how investors weigh this mature payments business. On this metric, the stock trades on a P/E of about 4.9x, which is far below both the Diversified Financial industry average of roughly 16.2x and a peer group closer to 53.2x. That is a steep discount in simple earnings terms and indicates that the market is pricing in meaningful concern around the durability of those profits.
The Fair Ratio model, which adjusts the expected P/E for Western Union based on its profitability profile, balance sheet risk and size, also points to the current multiple as appearing undervalued rather than stretched. Because the recent headlines focus on a 14.9% dividend yield and questions over cash coverage, the low P/E suggests that, despite those concerns, investors are still valuing the stock at a marked discount to what this framework would imply for its earnings power. Explore the numbers behind Western Union's P/E valuation.
The Western Union Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Western Union pick up where this valuation puzzle leaves off and explain what kind of future for growth, margins and earnings would need to occur for the stock to appear meaningfully higher or lower than today's price on the Community page. Each Narrative presents Western Union's implied fair value as a thesis about the business that you can keep comparing with how the story develops over time.
Community views on Western Union split between investors who see more upside in the digital and cost reset story and those who think the recent numbers already bake that in.
Bull case: 10% undervalued
"The accelerated Beyond Efficiency program, targeting US$50 million of run rate cost reductions by the end of 2026 and US$200 million by the end of 2027 through measures such as legacy product shutdowns, AI enabled productivity gains and regionalized operations, is aimed at offsetting pressure from the mix shift to lower margin digital, which could support operating margin and earnings if executed as planned..."
Discover why this Narrative puts Western Union at 10% undervalued.
Bear case: roughly fairly valued
"The current numbers on revenue, earnings guidance and dividend coverage imply a share price that already reflects a recovery in profitability that Western Union has not yet delivered..."
Explore why this Narrative puts Western Union at roughly fairly valued.
Western Union's valuation story is missing one crucial piece
The figures only tell part of Western Union's story, because the people setting priorities and the way their rewards are structured can shape how those numbers evolve over time. See who runs Western Union and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com