
Descartes Systems Group (TSX:DSG) Stock May Be 20% Undervalued As Shipping Software Gains Traction
Descartes Systems Group has delivered a solid multi year share price gain, which naturally raises the question of whether the current price still lines up with the cash the business is expected to generate. With investors watching both recent returns and fresh product news, the key issue is how those cash flows stack up against what the market is now willing to pay.
- Over the past 3 years, Descartes Systems Group has returned 27.0%, putting real weight on whether that kind of move is adequately backed by the cash flowing through the business.
- The roll out of the Descartes Pacejet multicarrier shipping solution at customers like Herschel Parts may support expectations for stickier demand and potentially steadier future cash inflows as more shipping volume runs through the platform.
- If you'd rather focus on earnings, this one's for you. See why Descartes Systems Group's 41.3x P/E tells a different valuation story.
The issue now is whether Descartes Systems Group's current share price is properly supported by its intrinsic value estimate based on its cash flows.
If you are testing whether Descartes Systems Group's cash flow story suits your style, a focused screen of other companies can sharpen that comparison. You can start with 4 high quality undervalued stocks.
Is Descartes Systems Group Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model focuses on the cash Descartes Systems Group can return to shareholders over time. On the latest twelve month figures, the business generated roughly $298.5 million of free cash flow, and the projection set points to growing cash flows rather than a shrinking stream.
Analysts supplying the DCF inputs expect that free cash flow in dollar terms steps up over the coming decade, then tapers into more moderate growth as Descartes Systems Group matures. Because the Herschel Parts rollout of Descartes Pacejet highlights how additional customer volume can run across the same software platform with limited extra cost, the discounted cash flow projections put Descartes Systems Group's estimated intrinsic value meaningfully above the current share price of CA$126.77. Find out what Descartes Systems Group could be worth using our Discounted Cash Flow (DCF) estimate.
The Descartes Systems Group Narrative: What Would Justify Today's Price?
Narratives for Descartes Systems Group pick up where the valuation puzzle leaves off and explain which potential paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price on Simply Wall St’s Community page. Rather than using a single ratio or DCF number, they translate that figure into a clear set of future conditions so you can observe over time whether the actual business is aligning with the story behind the valuation.
One of the top community narratives on Descartes Systems Group: roughly fairly valued
"Digital transformation, high recurring revenue, and strategic acquisitions strengthen customer loyalty, improve margins, and position Descartes for sustainable long-term growth."
Discover why this Narrative puts Descartes Systems Group at roughly fairly valued.
One more Descartes Systems Group check that belongs beside the cash flow view
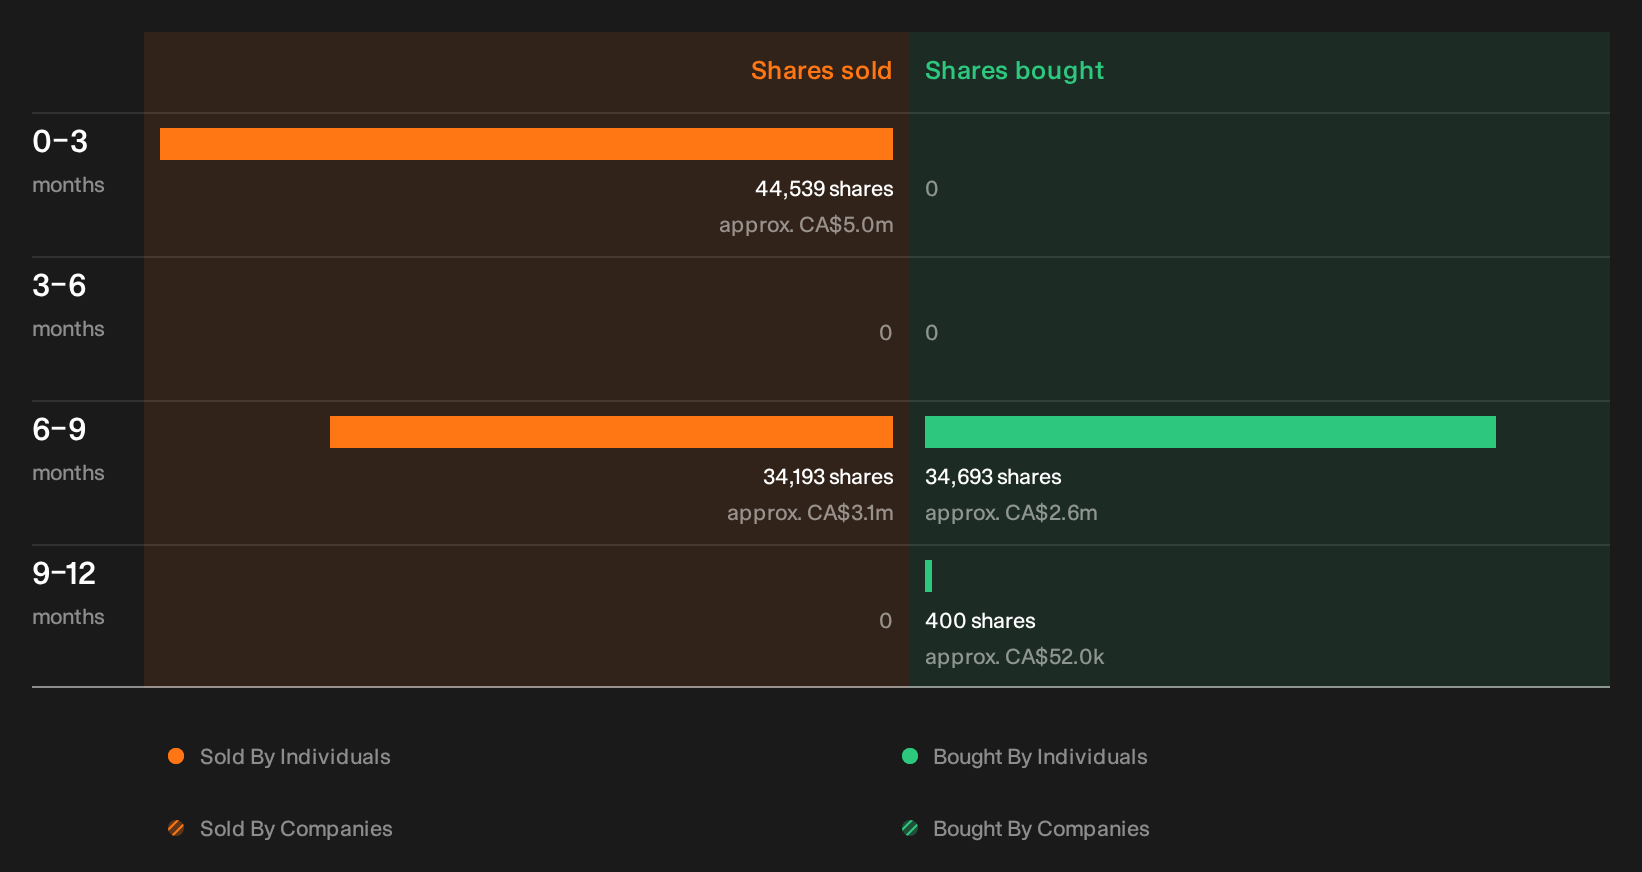
Price and cash generation tell only part of the story for Descartes Systems Group, because recent transactions by people inside the business can sometimes offer a different kind of signal. See the recent insider selling flagged for Descartes Systems Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com