
Encompass Health (EHC) On Strong Q3 And Higher Outlook Still Looks Modestly Undervalued
Encompass Health (EHC) has investors’ attention after third quarter 2026 results showed higher sales and earnings than a year earlier, followed by a raised full year revenue outlook and continued rehabilitation capacity expansion.
That backdrop has been reflected in Encompass Health’s trading pattern in 2026, with a 1 month share price return of 13.44% and a 90 day gain of 20.83% helping lift the year to date share price return to 27.76% at a last close of $135.90. Momentum looks firmly positive rather than fading, and when set against a 1 year total shareholder return of 20.25% and a very large 5 year total shareholder return of 175.91%, the latest earnings beat, higher guidance, hospital openings in Texas and the affirmed dividend help explain why investors are currently willing to pay up for the stock.
Scan other hospital and healthcare operators showing similar momentum and quality markers to Encompass Health using our hand picked list of list of solid balance sheet and fundamentals (24 results)
After a 2026 surge that pushed Encompass Health toward recent highs, the practical question is simple. Do you lean into this strength now, or wait in hope of a cheaper valuation reset before committing fresh capital?
Most Popular Narrative: 8% Undervalued
On Simply Wall St’s most followed narrative, Encompass Health screens as modestly undervalued, with a fair value of $148.17 against the recent $135.90 close. This puts recent share strength in the context of a still supportive long term thesis built on capacity, case mix and labor execution.
Ongoing expansion of Encompass Health’s inpatient rehabilitation footprint through de novo hospitals, bed additions at high occupancy sites, and small format facilities, supported by a disclosed multi year pipeline and high returns on these projects, points to further discharge volume growth that can lift net operating revenue and EBITDA.
See why 6 investors see Encompass Health as 8% undervalued.
The narrative builds this view using a 7.24% discount rate and assumes an 8.43% revenue growth rate with profit margins around 10.2%. Together, these inputs support a fair value estimate of $148.17. That sits roughly 8% above the latest share price and leans on expectations for higher acuity volumes, disciplined leverage near 1.9x and ongoing dividends and buybacks to support earnings per share over time.
Result: Fair Value of $148.17 (UNDERVALUED)
Still, the Encompass Health narrative can be knocked off course if tougher Medicare Advantage authorization trends spread, or if new hospitals and added beds ramp more slowly than planned.
Find out about the key risks to this Encompass Health narrative.
Another View: What Encompass Health’s P/E Is Really Saying
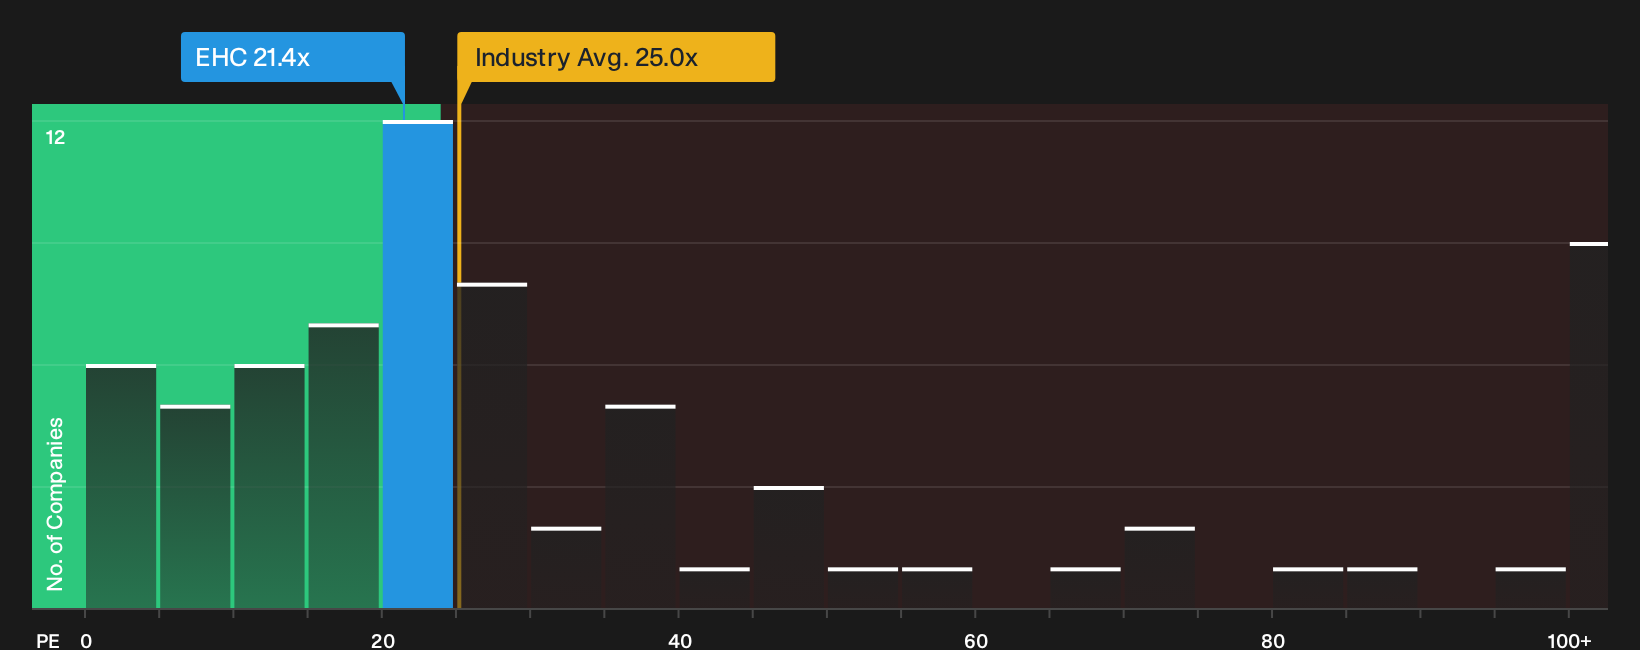
The SWS DCF model leans toward Encompass Health being modestly cheap, yet the simple P/E lens paints a tighter picture. At 21.4x earnings, EHC trades below the broader US Healthcare sector on 25x, but above its direct peer group on 17.3x and under a fair ratio of 25.4x that the market could drift toward over time.
So investors face a trade off. Is paying a premium to peers but a discount to sector and fair ratio a fair entry toll, or a sign to be patient about the price you are willing to accept?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Encompass Health sounds familiar, treat it as your signal to move quickly on your own research. Carefully examine and stress test the bullish and bearish angles yourself using the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Encompass Health?
If Encompass Health has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not reacting after the best setups move first.
- Target resilient opportunities by scanning a 29 resilient stocks with low risk scores that filters for businesses with steadier profiles and fewer financial red flags.
- Hunt for mispriced quality through a curated 30 high quality undervalued stocks that highlights companies combining stronger fundamentals with more modest valuations.
- Get ahead of the crowd by combing through a focused 19 high quality undiscovered gems built to surface lesser known stocks with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com