
What Southside Bancshares (SBSI)'s Strong Quarterly Earnings Means For Shareholders
- Southside Bancshares reported third quarter 2026 net interest income of US$60.3 million and net income of US$27.98 million, with basic earnings per share from continuing operations of US$0.94.
- The nine month figures showed US$175.32 million in net interest income and US$78.07 million in net income, which provides investors with recent data on how Southside Bancshares is managing its interest earning assets and overall profitability.
- We will now look at how this change in quarterly net income could influence the existing investment narrative around Southside Bancshares.
Southside Bancshares Investment Narrative Recap
To own Southside Bancshares, you need to be comfortable with a regional Texas bank that leans heavily on net interest income and an asset sensitive balance sheet. The latest quarter showed net interest income of US$60.3 million and net income of US$27.98 million, which supports the view that repricing efforts and higher yielding assets are feeding through to earnings.
The key short term swing factor remains how much of that earnings power survives funding cost pressure and deposit competition. Margin compression had been a concern, so stronger quarterly profitability helps the near term story but does not remove the risk that higher wholesale funding and volatile deposits could again weigh on net interest margin.
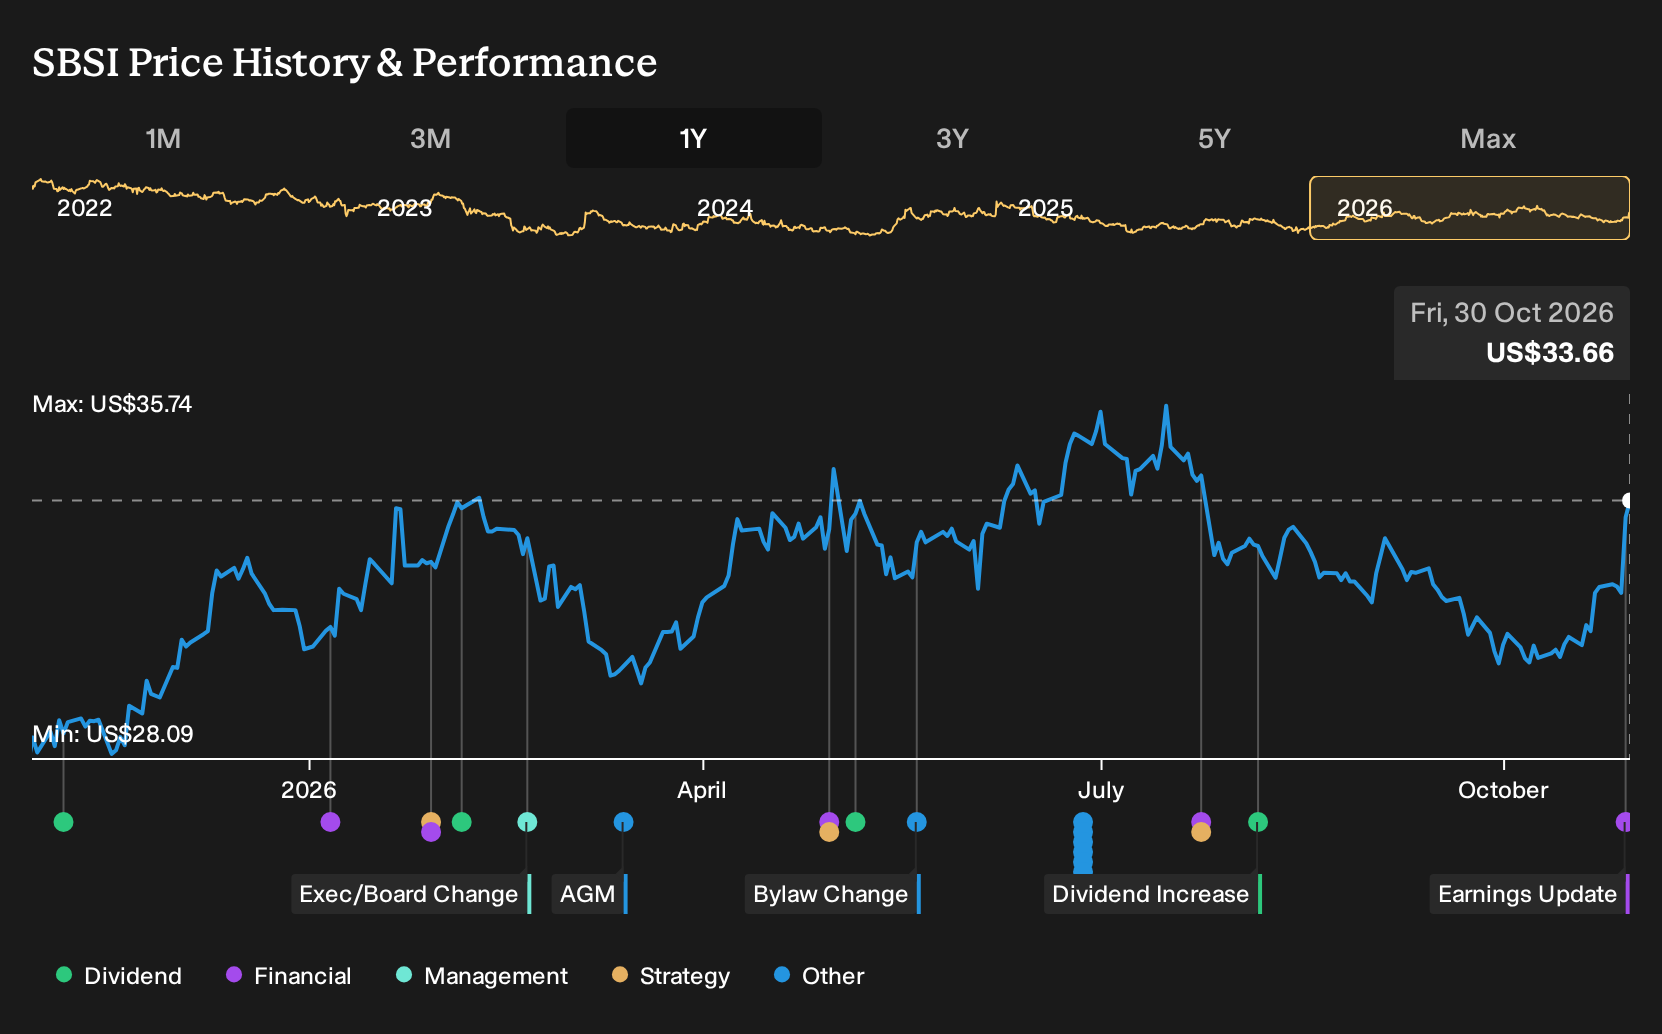
The most relevant update for this discussion is the third quarter and nine month earnings announcement on October 29, 2026. Southside Bancshares reported net income of US$27.98 million for the quarter and US$78.07 million for the first nine months of 2026, along with basic EPS from continuing operations of US$0.94 for the quarter and US$2.62 for the nine month period.
Those results provide more recent evidence on whether the earlier balance sheet moves, including securities repositioning and loan repricing, are translating into higher net interest income despite margin pressure and funding volatility. They also provide a current earnings base for weighing risks around deposit stability, wholesale balances and the possibility that rising funding costs could again compress profitability.
Southside Bancshares' current analyst narrative points to revenues of US$336.4 million and earnings of US$110.6 million by 2029, based on projected revenue growth of 11.1% per year and a projected earnings increase of about US$34.6 million from US$76.0 million today.
Uncover why Southside Bancshares' fair value is essentially aligned with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$34 to about US$46.51 per share, so you are seeing a wide gap between the lowest and highest views. When you pair that spread with ongoing questions around funding costs, deposit stability and margin pressure, the case for checking multiple Southside Bancshares viewpoints becomes clear.
Explore another Southside Bancshares fair value estimate, including one that suggests it could be worth just $34.00.
Reach Your Own Conclusion
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Southside Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Southside Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southside Bancshares' overall financial health at a glance.
Looking for more Southside Bancshares investment ideas?
If the Southside Bancshares story has sharpened your view on regional banks and risk, you can use that momentum to scan a broader set of listed businesses that might better match your return goals and comfort with volatility.
- For investors who want potential upside without paying too much for quality, review companies flagged in the 30 high quality undervalued stocks and see which ones align with your own thesis.
- If resilience and conservative balance sheets matter most to you, focus on businesses highlighted in the list of solid balance sheet and fundamentals (24 results) to find those with financial structures you might be more comfortable holding through different conditions.
- Income oriented readers can concentrate on stocks screened as 5 dividend fortresses and then judge whether those yields fit with their own cash flow needs and risk limits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com