
3 Undervalued Stocks With Discounts Up To 41%
More than $2 trillion in Nasdaq-100 value disappeared in October as investors questioned whether heavy AI spending can translate into solid cash returns. When markets punish uncertainty around future cash generation, companies quietly producing robust cash flows yet priced cheaply can slip through the cracks. This article highlights three such stocks from a discounted cash flow screener that may appeal to investors hunting for mispriced cash generators today.
The three stocks discussed next are only a small sample from this idea, with the full screen surfacing 87 more companies whose cash flow stories and valuations are not covered here. To go straight to the source and identify which of these potential mispricings best fits your approach, analyze the Undervalued Stocks Based On Cash Flows screener.
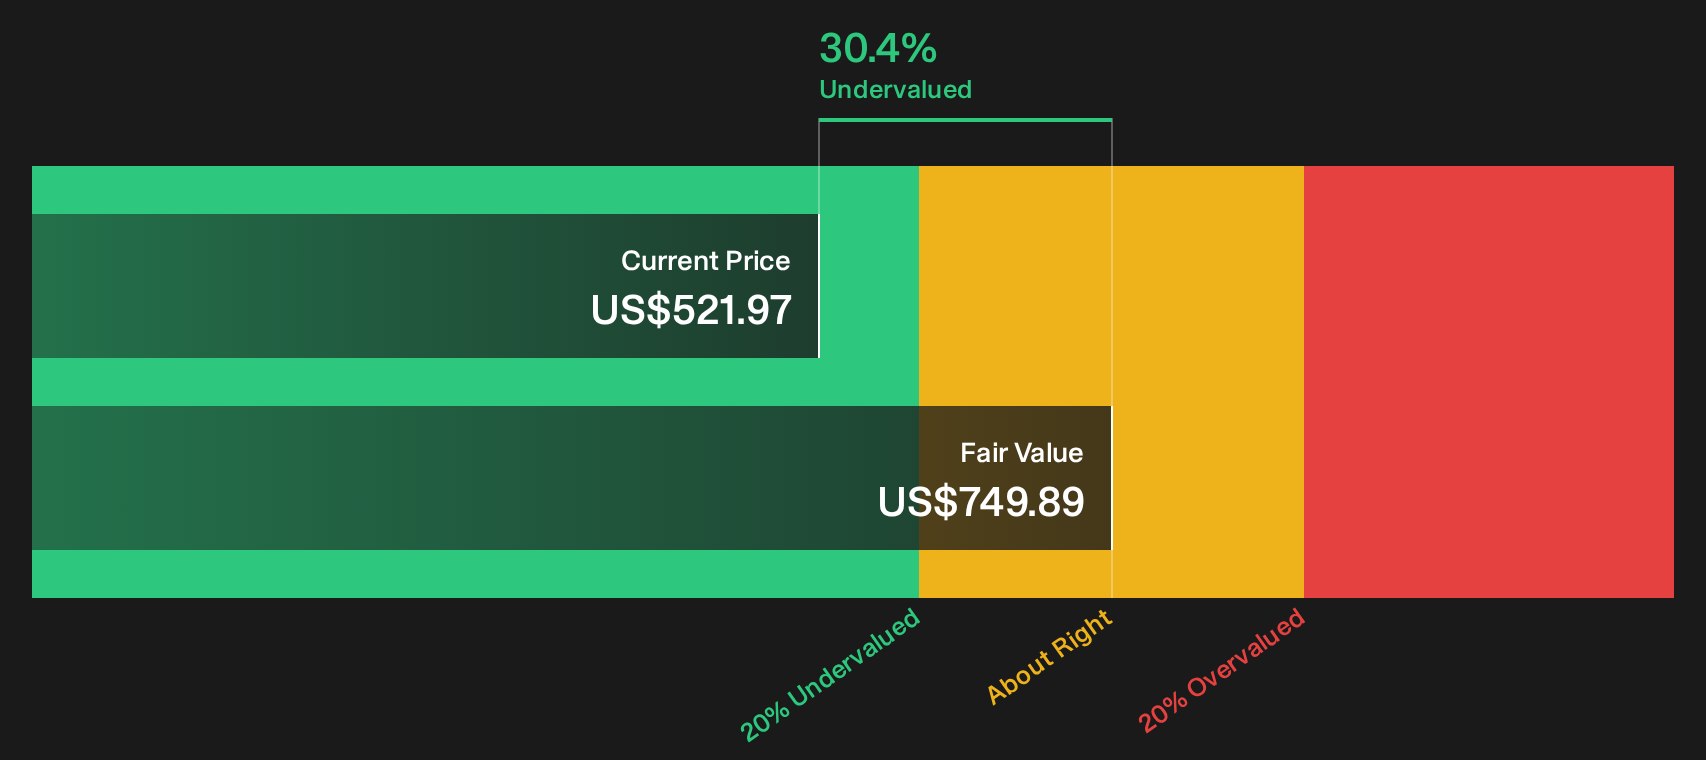
Microsoft (MSFT)
Overview: Microsoft is a global software and cloud platform provider, with Azure and AI services generating recurring, high-margin cash flows for enterprise customers.
For this cash-flow-focused screen, Microsoft matters because its Azure-driven Intelligent Cloud business converts AI and cloud demand into recurring cash, even while the share price reflects investor concerns about heavy infrastructure spending.
"Microsoft spent $37.5 billion in ninety days because customer demand for Azure cloud computing is growing at 39% per year and the company literally cannot build servers fast enough."
Investors may also consider what could happen to that cash flow profile if a single unseen pressure on long-term cloud profitability and AI economics develops in an unfavorable way.
Market Cap: US$3.94t
That hidden pressure is exactly what the full narrative for Microsoft unpacks, showing how Microsoft’s cash engine could accelerate or stall as AI infrastructure spending and pricing power evolve.
Bank of America (BAC)
Overview: Bank of America is a large U.S. bank that turns consumer and commercial lending and deposits into recurring cash-heavy banking and fee income.
Operations: Bank of America generates about US$40.8b from Consumer Banking, US$27.3b from Global Wealth & Investment Management, US$26.3b from Global Markets and US$24.1b from Global Banking.
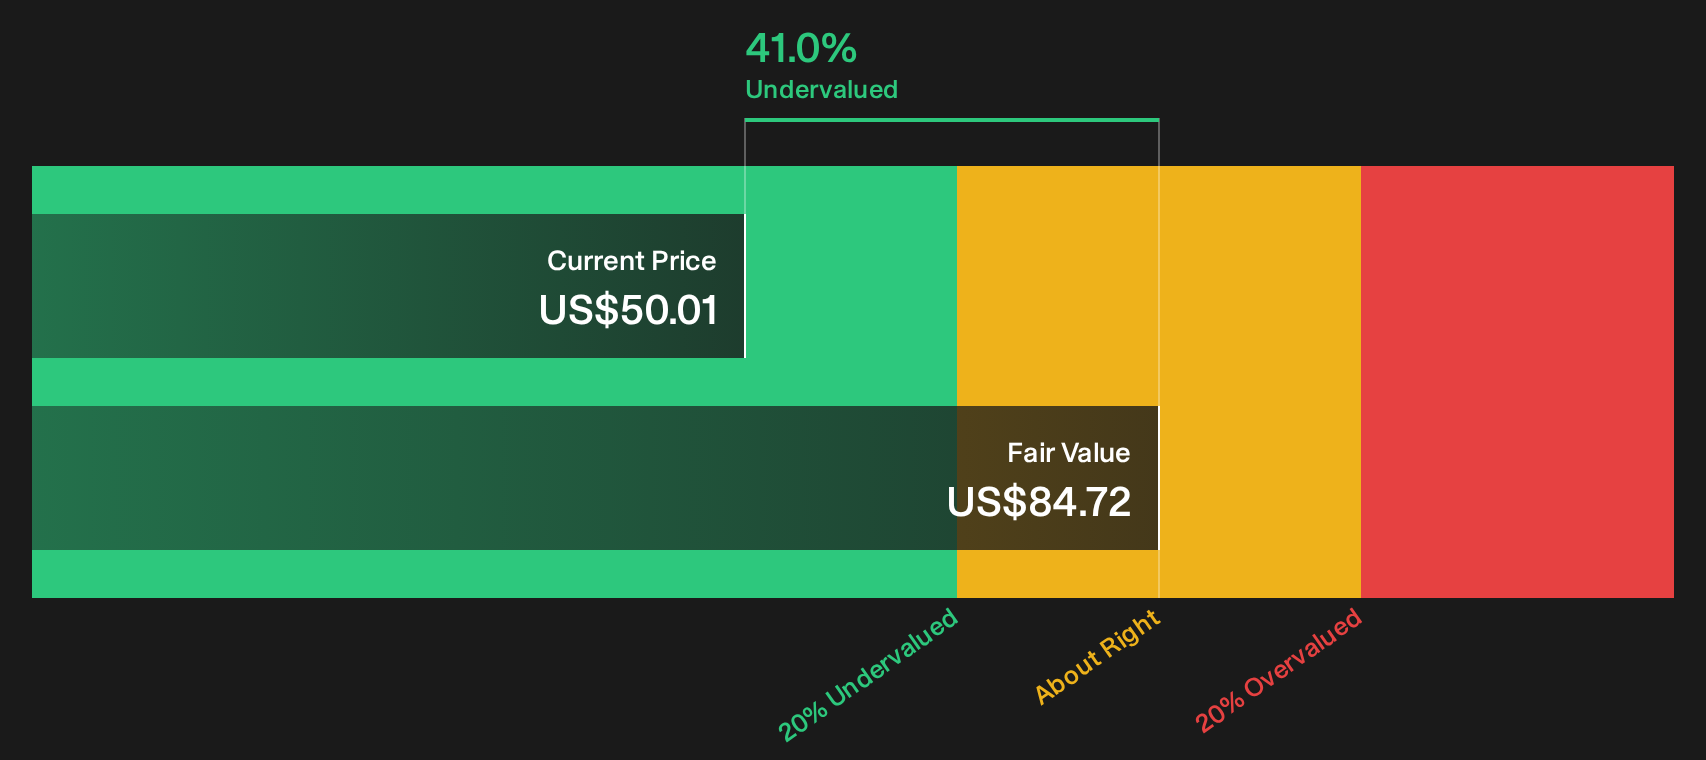
Market Cap: US$345.1b
Bank of America matters for this cash-flow screen because its lending and deposit engines produce contractual interest income that supports discounted cash flow valuations, while the broader franchise adds resilience around that core.
"Bank of America's continued investment in digital engagement and AI-driven efficiencies remains a live driver, with plans to double the AI budget within a US$14b technology spend and more than 140 AI applications such as Erica and CashPro already reducing support needs. This may support revenue and net margins as the next wave of use cases is implemented."
One risk to consider is what happens if an unseen pressure on those efficiency gains shifts net interest income or expense trends away from what the models assume.
That pressure point is exactly why the full narrative for Bank of America digs into how Bank of America’s cash engine could keep accelerating even if rate and cost trends start decoupling.
Crocs (CROX)
Overview: Crocs designs and sells casual footwear and accessories under the Crocs and HEYDUDE brands, with its core branded shoes driving cash-generative demand that fits the Undervalued Stocks Based On Cash Flows theme.
Operations: Crocs Brand delivers about US$3.41b in sales while HEYDUDE Brand adds roughly US$692 million across its footwear portfolio.
Market Cap: US$6.88b
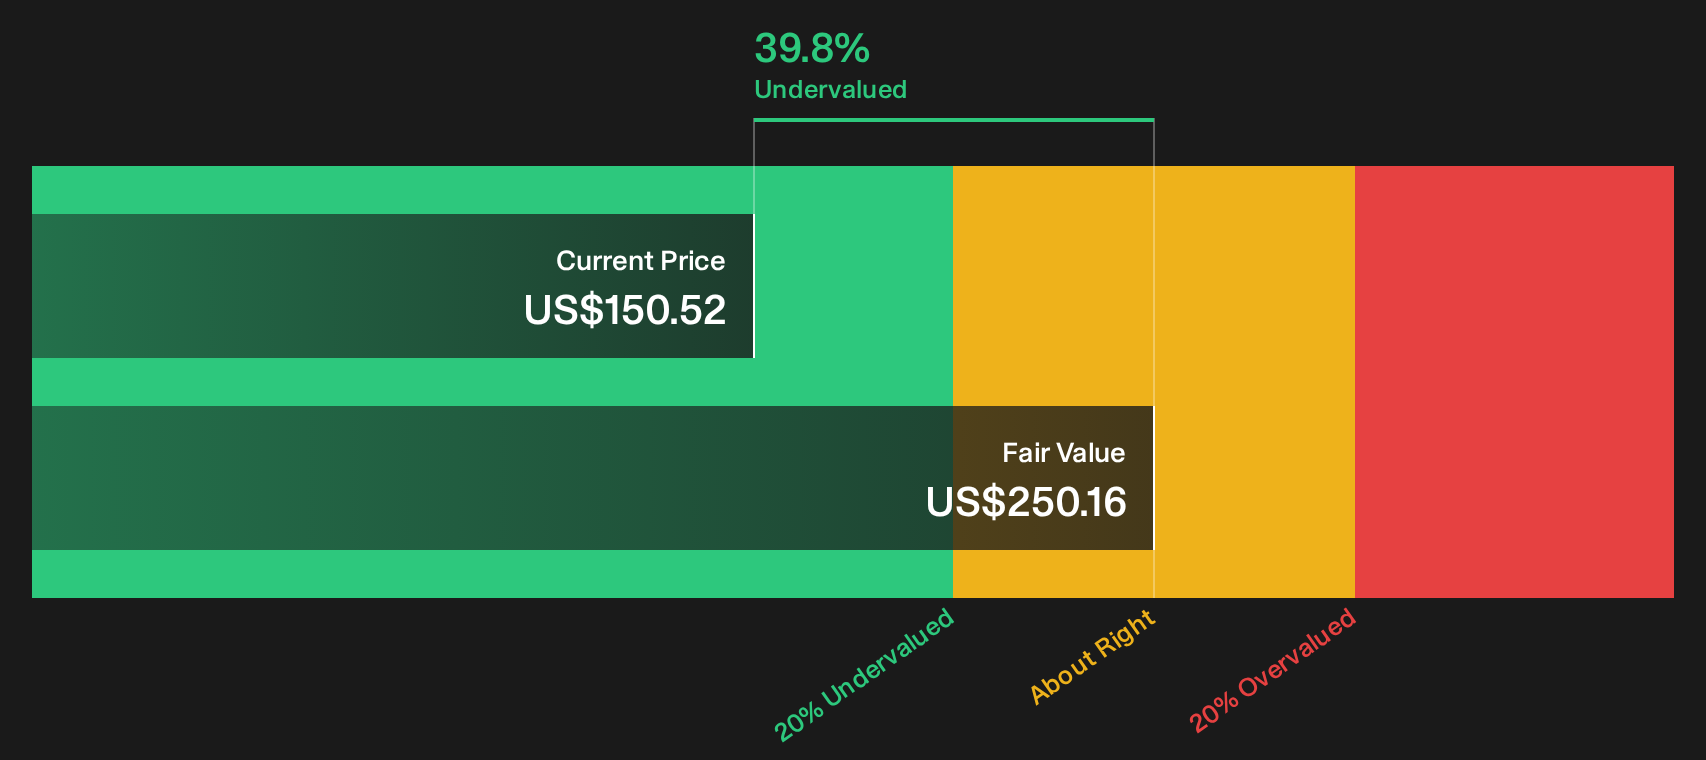
Crocs matters here because its flagship clogs, sandals and casual shoes throw off significant cash, yet the stock still trades below a DCF-based fair value estimate grounded in those cash flows.
"Expansion of Crocs beyond the Classic Clog into sandals approaching $0.5b in expected 2026 revenue, new lifestyle franchises such as Ballet Flat and Mellow, and HEYDUDE extensions in sandals, work and boots points to a broader portfolio that can support a wider customer base and more stable revenue."
The real swing factor is what happens if one unseen pressure on that cash-rich model starts to pinch pricing power faster than profits adjust.
That pricing pressure is exactly why it is worth reading the full narrative for Crocs to see how Crocs could turn an overlooked squeeze into accelerating strength.
Curious About Fresh Alternatives?
Markets move fast and fresh ideas do not stay under the radar for long. Spot potential breakouts and momentum before the crowd while it still matters and get in early.
- Target dependable cash generators and stress test income resilience by sweeping through the 5 dividend fortresses that focus on balance sheet strength and payout durability while yields remain elevated.
- Chase early momentum in real-world AI adoption by scanning the 41 profitable AI stocks that aren't just burning cash that already convert algorithms and data into earnings instead of burning capital.
- Hunt for durable pricing power in mission critical materials by reviewing the 16 top copper producer stocks powering grids, vehicles and infrastructure before institutional money crowds these producers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com