
Nihon Shokuhin Kako (TSE:2892) Q2 Results Reveal A Sharper Margin Squeeze
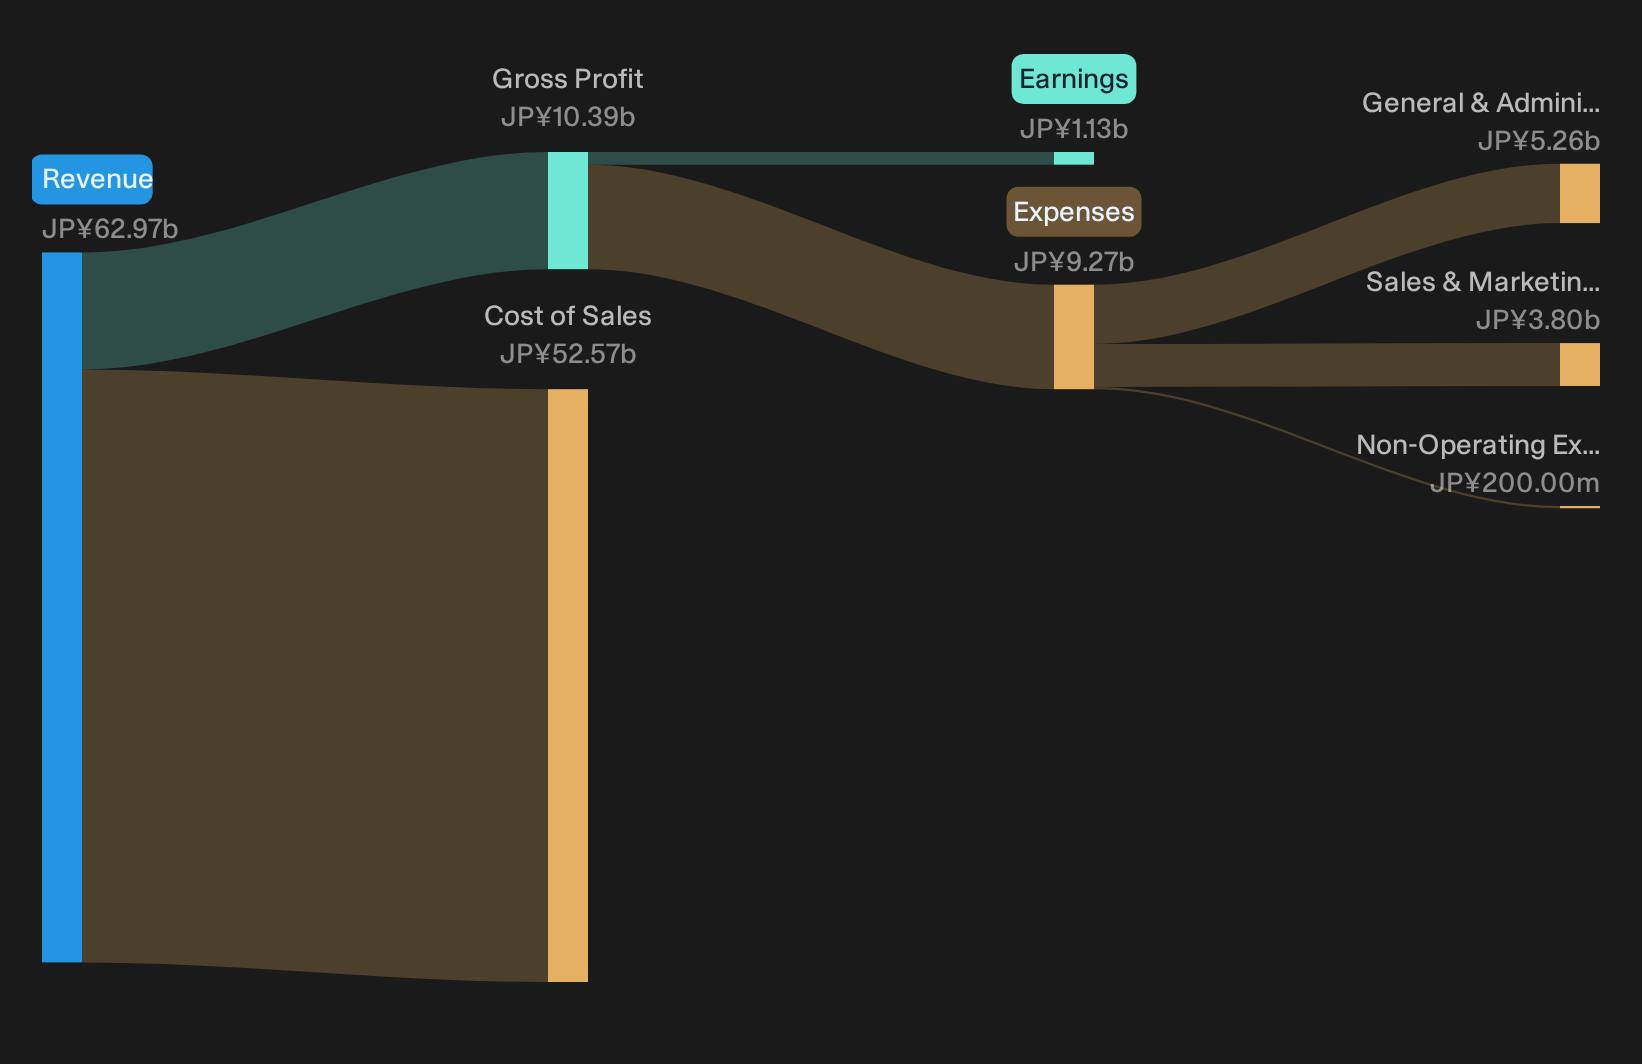
Nihon Shokuhin Kako walked into its Q2 2027 earnings release with investors already on edge after a weak year for profits and a share price stuck around ¥4,750 at the close on 30 October. The headline this quarter is margin pressure. Net profit over the trailing twelve months sits at ¥1,125 million on revenue of ¥62,966 million, and that thin profitability is where sentiment is colliding with reality.
The equity story today is all about emotion meeting arithmetic. A stock that screens cheap on some models, yet trades on a 20.2x P/E, is forcing investors to ask whether this latest squeeze in earnings power really justifies the recent drift in the price or if fear is doing more work than the numbers.
Like the earnings story at Nihon Shokuhin Kako but uneasy about thin profits on a 20.2x P/E? Benchmark this setup against a wider field of resilient, cash generative businesses in the 23 resilient stocks with low risk scores
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥16,103 million vs. ¥16,517 million (declined 2.5%)
- Net Income (Q2 2027 vs Q2 2026): ¥493 million vs. ¥631 million (fell 21.9%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥103.89 vs. ¥128.31 (down 19.0%)
- Trailing 12-month Net Profit Margin (Q2 2027 vs Q2 2026): 1.8% vs. 2.3% (compressed by 0.5 percentage points)
Ask Charlie what makes Nihon Shokuhin Kako look undervalued.
Nihon Shokuhin Kako, resilience claims under pressure
For investors leaning on the defensive food ingredients story, the Q2 profile from Nihon Shokuhin Kako asks for patience. Revenue of ¥16,103 million is close to last year’s level, which fits a steady demand narrative for starches and sweeteners. Profitability tells a tougher story. Quarterly net income of ¥493 million and a 1.8% trailing margin show earnings power under strain rather than strengthening. The case for a resilient, cash generative supplier still rests on business mix and Mitsubishi backing, not on recent profit trends.
Margin squeeze fuels the cautious argument
Bears pointing to thin returns just picked up fresh support. Net income fell from ¥631 million to ¥493 million while the trailing margin compressed from 2.3% to 1.8%. That is a clear hit to earnings quality for an ingredients producer that needs pricing power to offset input swings. Recent share performance, down about 3% over both 7 and 30 days but still up over 90 days, suggests the market is reassessing rather than capitulating. Near term, the risk narrative around cost pressure and fragile margins looks well grounded in these numbers.
After revenue sliding 0.4% over the past year and margins now tighter, it is fair to ask whether this is simply a temporary wobble or the early signal of deeper structural issues in Nihon Shokuhin Kako’s business. Scan the independent risk analysis for Nihon Shokuhin Kako which shows 1 important warning signHunt Quiet Disconnects In Plain Sight
Nihon Shokuhin Kako now shows how shifting sentiment can diverge from reported income. The real opportunity is studying where disciplined investors may see value before broad attention adjusts expectations.
- Company 1 - 29% below our estimate - supplies motion components that capture demand as factories modernize precise automated production equipment. The real opportunity is assessing whether current pricing reflects long-term adoption of these upgrades.
- Company 2 - 44% below our estimate - sells project and cloud services firms adopt as connected devices and automation projects surpass in house tools. The real opportunity is evaluating if constrained budgets obscure future integration and scalability needs.
- Company 3 - 36% below our estimate - builds large infrastructure and property assets that secure work as public facilities and logistics networks need renewal. The real opportunity is reviewing whether tender pipelines and renewal cycles align with present valuation.
That is three of the list. See every one of the 16 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com