
What Tompkins Financial (TMP)'s Earnings Beat Means For Shareholders
- Tompkins Financial reported third quarter 2026 net interest income of US$77.3 million and net income of US$28.65 million, alongside a regular quarterly dividend of US$0.74 per share that the board approved for payment in November 2026.
- The cash dividend was raised by US$0.04 per share, or 5.7% compared with the third quarter of 2025. This indicates that Tompkins Financial’s board is comfortable returning more capital even as net loan and lease charge offs modestly increased year on year.
- We will now look at how Tompkins Financial's investment narrative could be affected by stronger earnings and a higher quarterly dividend.
Expand your income playbook by comparing Tompkins Financial's latest dividend move with a curated 5 dividend fortresses that may offer similar yield strength and balance sheet resilience.
What Is Tompkins Financial's Investment Narrative?
To own Tompkins Financial, you need to be comfortable with a pretty straightforward banking story. The group leans on traditional lending and deposit gathering, plus fee income from wealth and insurance, and the latest quarter showed that this engine can still throw off solid net interest income and earnings. A higher quarterly dividend suggests management sees the capital position as supportive, even with net loan and lease charge offs edging up to US$1.2 million. That move matters if you care about income and want a bank that pays you while you wait.
The bigger swing factor is what happens after this strong patch. Analyst models point to earnings and revenue declining over the next few years, so today’s profit surge and richer dividend may not fully settle concerns about long term growth. Charge offs remain modest in absolute terms, so the latest credit data does not look like a breaking point, but it does keep attention on asset quality and pricing power if loan demand softens or funding costs bite.
That said, there is one operational pressure point inside Tompkins Financial’s story that could change the risk and reward balance if ...
There's only one way to know the right time to buy, sell or hold Tompkins Financial. Head to Simply Wall St's company report for the latest analysis of Tompkins Financial's Fair Value.
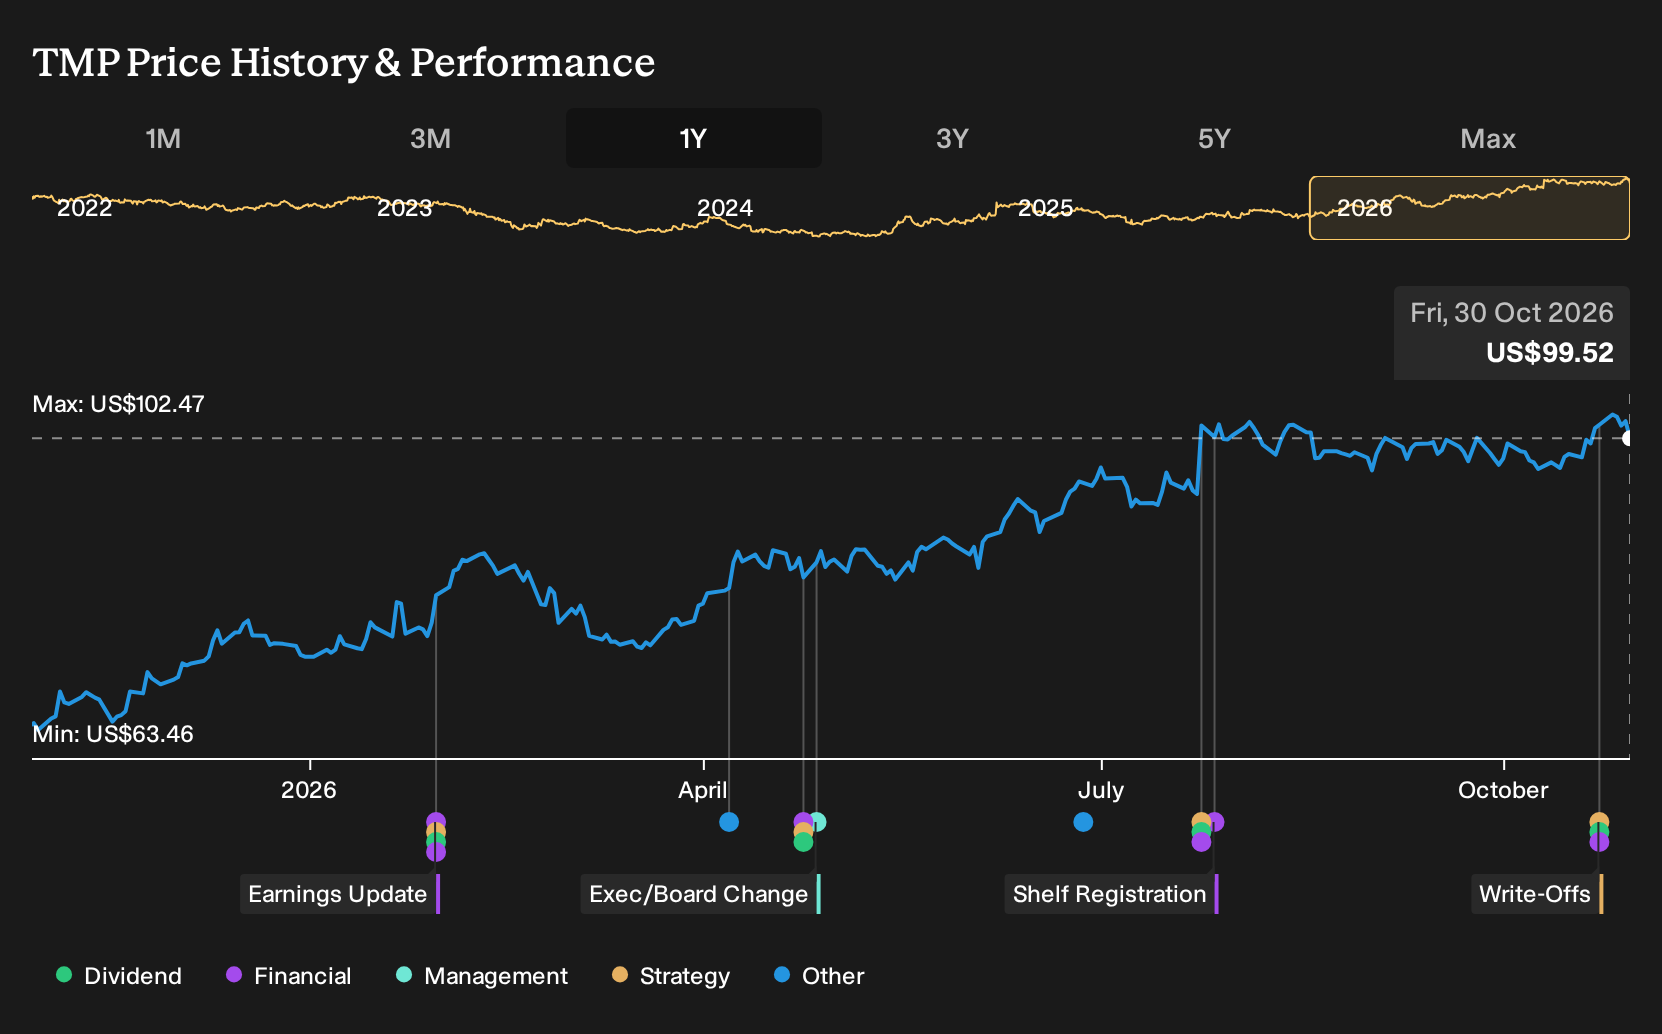
Exploring Other Perspectives
Community fair value views on Tompkins Financial from 2 Simply Wall St Community members cluster between US$105.50 and about US$129.74, so even a tiny sample spans a wide price band. Set those estimates against recent earnings and dividend news that landed on 23 October 2026 and you get a reminder that opinions can diverge sharply. Use that spread as a cue to explore more than one angle before you decide where the stock belongs in your portfolio.
Explore another Tompkins Financial fair value estimate, including one that suggests as much as 30% upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tompkins Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tompkins Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tompkins Financial's overall financial health at a glance.
Looking For More Ideas Beyond Tompkins Financial?
If this Tompkins Financial update has sharpened your thinking on income, value and risk, broaden that work by lining it up against a few carefully filtered shortlists from the Simply Wall St Screener. Each set is built to spotlight different angles on quality and resilience, so you can cross check this bank against other candidates that might fit your goals.
- For income seekers who care about durability as much as yield, compare Tompkins Financial with a curated group of 5 dividend fortresses that aim to pair strong payouts with balance sheet strength.
- If capital preservation is high on your list, stress test your ideas against 29 resilient stocks with low risk scores that score well on Simply Wall St's risk framework and may help smooth the ride.
- When you want something off the beaten path without discarding fundamentals, widen your watchlist with 19 high quality undiscovered gems that combine quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com