
Will Strong Q3 Earnings Change Evercore (EVR) Stock Narrative
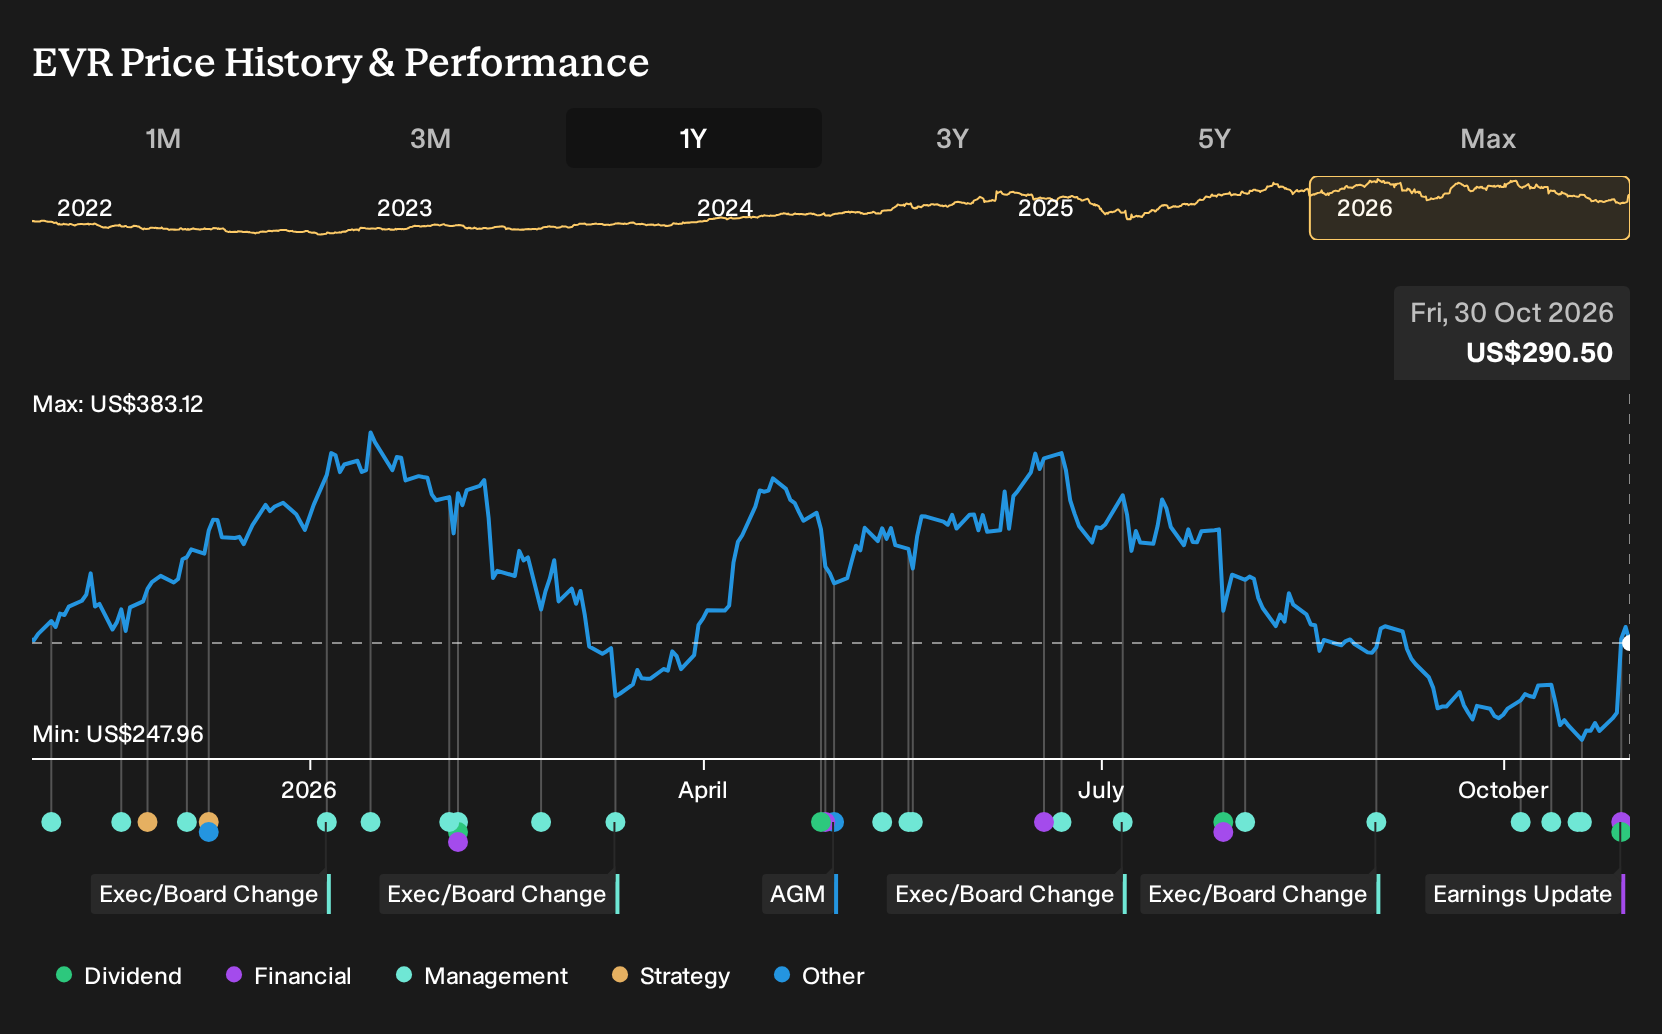
- Evercore reported third quarter 2026 revenue of US$1,176.88 million and net income of US$160.78 million, with earnings per share higher than the same period a year earlier, and affirmed a US$0.89 quarterly dividend payable in December 2026.
- The firm credited record M&A advisory activity and growing contributions from areas such as restructuring and debt advisory, while also reshaping leadership and adding senior banking talent to support its advisory platform.
- The focus now turns to how Evercore's advisory-driven earnings performance could influence its investment narrative around backlog conversion and profitability.
Scan how Evercore's advisory driven earnings story compares with other capital markets specialists by reviewing our curated list of 33 high quality undervalued stocks right now.
Evercore Investment Narrative Recap
To own Evercore, you need to believe the advisory engine can keep turning record backlogs into fee income while expense ratios stay under control. The latest quarter showed higher revenue and earnings per share, which supports that execution story. The key short term swing factor remains deal completion timing, especially in large cap M&A and related financings.
Cost inflation is still the main worry. Non compensation expenses had already been running higher as a share of revenue, and hiring senior talent keeps compensation sensitive to deal volumes. The fresh Q3 strength helps ease that concern but does not remove it, because a softer advisory environment could quickly expose those fixed costs.
The most relevant recent update for this story is the December 2026 quarterly dividend affirmation of US$0.89 per share. That decision signals Evercore is comfortable pairing elevated hiring and technology spending with ongoing cash returns, rather than pulling back capital distributions in response to cost pressure or a weaker pipeline.
For catalysts, that dividend sits alongside record backlogs and ongoing investments in senior managing directors as key proof points for investors watching execution. The risk is that higher non compensation and compensation ratios limit flexibility if advisory volumes slow. If activity holds, Evercore may be able to convert its current earnings power into consistent shareholder distributions.
Evercore's analyst narrative points to revenues of US$5.0b and earnings of US$696.9 million by 2029, based on forecast revenue growth of 2.1% per year and a decline in earnings of US$48.1 million from US$745.0 million today.
Uncover why Evercore's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on revenue risk. The most bearish analysts projected Evercore’s sales drifting toward roughly US$4.1b and earnings nearer US$494.3 million by 2029. That is far more cautious than the consensus path. Those forecasts were set before this earnings and dividend news, so opinions may change. Use the gap between scenarios as a prompt to explore several angles before deciding how this advisory story fits your portfolio.
Explore 2 other Evercore fair value estimates, including one that suggests it could be worth just $332.20.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Evercore research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Evercore. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evercore's overall financial health at a glance.
Looking For More Investment Ideas Beyond Evercore?
If Evercore has sharpened your thinking about advisory driven earnings, broaden your watchlist by scanning other opportunities with the Simply Wall St Screener. You can filter for different styles and risk profiles, then weigh those candidates against the Evercore narrative you have just reviewed.
- For investors who want potential upside paired with balance sheet strength and dependable fundamentals, start with a list of solid balance sheet and fundamentals (24 results).
- If you care most about resilience and want to limit downside risk, focus on companies highlighted in our 29 resilient stocks with low risk scores.
- When you are hunting for underfollowed opportunities with healthy financials, scan through the 19 high quality undiscovered gems and see which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com