
Welltower (WELL) Could Be 10% Undervalued Following Q3 Earnings And Higher Guidance
Welltower (WELL) just combined a busy earnings day with two other decisions that matter for income focused investors. The group reported third quarter results, raised full year profit guidance and affirmed its quarterly dividend.
At a latest share price of US$234.60, Welltower has delivered a 25.49% year-to-date share price return, while the 1-year total shareholder return of 31.49% and 5-year total shareholder return above 200% point to strong, sustained momentum rather than a short-lived bounce.
Scan beyond Welltower and see how other income focused real estate plays are moving by checking our hand picked 5 dividend fortresses in this environment of upgraded guidance and affirmed payouts.
Bulls see Welltower’s guidance lift and earnings per share gains as proof the recent run still has legs. Bears look at a rich share price and ask what is already baked in. Which side does the valuation support next?
Most Popular Narrative: 10% Undervalued
On the most followed view of Welltower, the shares at $234.60 sit below an estimated fair value of $262.05, which puts the current rally in a different light for anyone focused on what is already priced in.
Significant off market acquisition activity, with about US$15.5b of largely newer senior housing assets bought or under contract at discounts to replacement cost and with room for occupancy improvement, gives Welltower a pipeline of properties that can contribute to future revenue and NOI expansion as they stabilize.
See why 31 investors see Welltower as 10% undervalued.
This narrative is built using a 7.25% discount rate and assumes revenue growth of 14.8% a year, margin expansion from 12.1% to 15.1%, and earnings reaching $2.9b by around 2029. To align with that outlook, the stock would trade on a P/E of 92.7x those projected earnings, which is far above the current 27.0x figure cited for the broader US Health Care REITs industry.
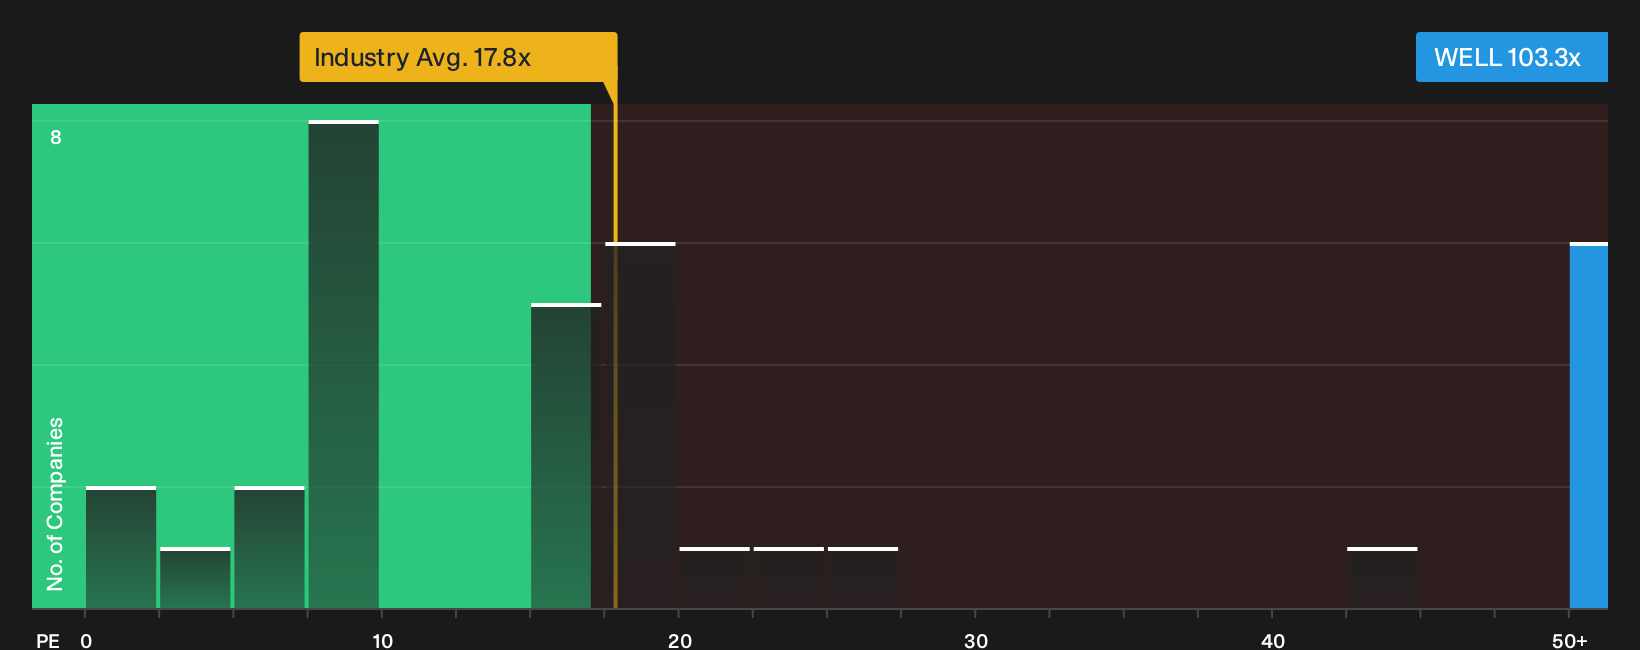
The gap between that future multiple and both the industry level and the estimated "fair" P/E of 40.7x from Simply Wall St’s fair ratio framework highlights how much optimism is embedded in the current pricing. On those figures, the current 103.3x P/E is materially richer than both peers at 86.1x and the modelled fair ratio that the market could plausibly move toward as expectations reset.
Explore the SWS fair ratio for Welltower.
Result: Fair Value of $262.05 (UNDERVALUED)
Still, if senior housing occupancy stalls or the recent US$11b of asset recycling proves more dilutive than expected, the current Welltower narrative could be challenged.
Find out about the key risks to this Welltower narrative.
Another View: What Multiples Say About Welltower
On a simple earnings multiple, Welltower paints a very different picture. The stock trades on a P/E of 103.3x, compared with 86.1x for close peers and 17.8x for the broader Global Health Care REITs group. The fair ratio framework points to 40.7x as a level the market could move toward, which signals real valuation risk if sentiment cools.
For investors weighing upside against that premium, the question is whether this pricing still leaves enough room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Welltower so far. If you want to move beyond the headlines and stress test the bullish and cautious arguments yourself, start by weighing its 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Welltower?
Do not stop your research with one stock. Broaden your watchlist with fresh ideas sourced from the Simply Wall St screener tools that spotlight different edges in the market.
- Target potential mispricings by scanning our 33 high quality undervalued stocks, which pairs quality fundamentals with prices that may not reflect underlying strength.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) so you can focus on businesses built on firmer financial footing.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that highlights strong fundamentals before attention fully arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com