
Should Higher Earnings Require Action From ASSA ABLOY (OM:ASSA B) Investors?
- ASSA ABLOY reported third quarter 2026 sales of SEK 40,771 million and net income of SEK 4,715 million, with basic earnings per share from continuing operations at SEK 4.24. For the first nine months, sales were SEK 115,781 million and net income was SEK 12,669 million.
- The company paired higher third quarter and year-to-date earnings with basic earnings per share from continuing operations rising to SEK 11.41 for the nine-month period, which provides a clearer view of how profit translates on a per share basis during 2026.
- This article examines how ASSA ABLOY's investment narrative relates to this higher earnings performance and what that may indicate for investors.
ASSA ABLOY Investment Narrative Recap
For an investor to stay with ASSA ABLOY, the core belief is that the shift toward higher tech access solutions and recurring software and services keeps gaining weight inside the portfolio. The latest quarter, with SEK 40,771 million in sales and SEK 4,715 million in net income, supports a view that the operating engine is still functioning across mixed regional end markets.
The most important short term swing factor remains non residential demand and specification activity, especially in North America and Europe, versus ongoing softness in residential and logistics. Currency remains the biggest operational risk, since persistent FX headwinds could offset mix benefits. The new figures do not materially change these near term drivers, but they make the earnings base more visible.
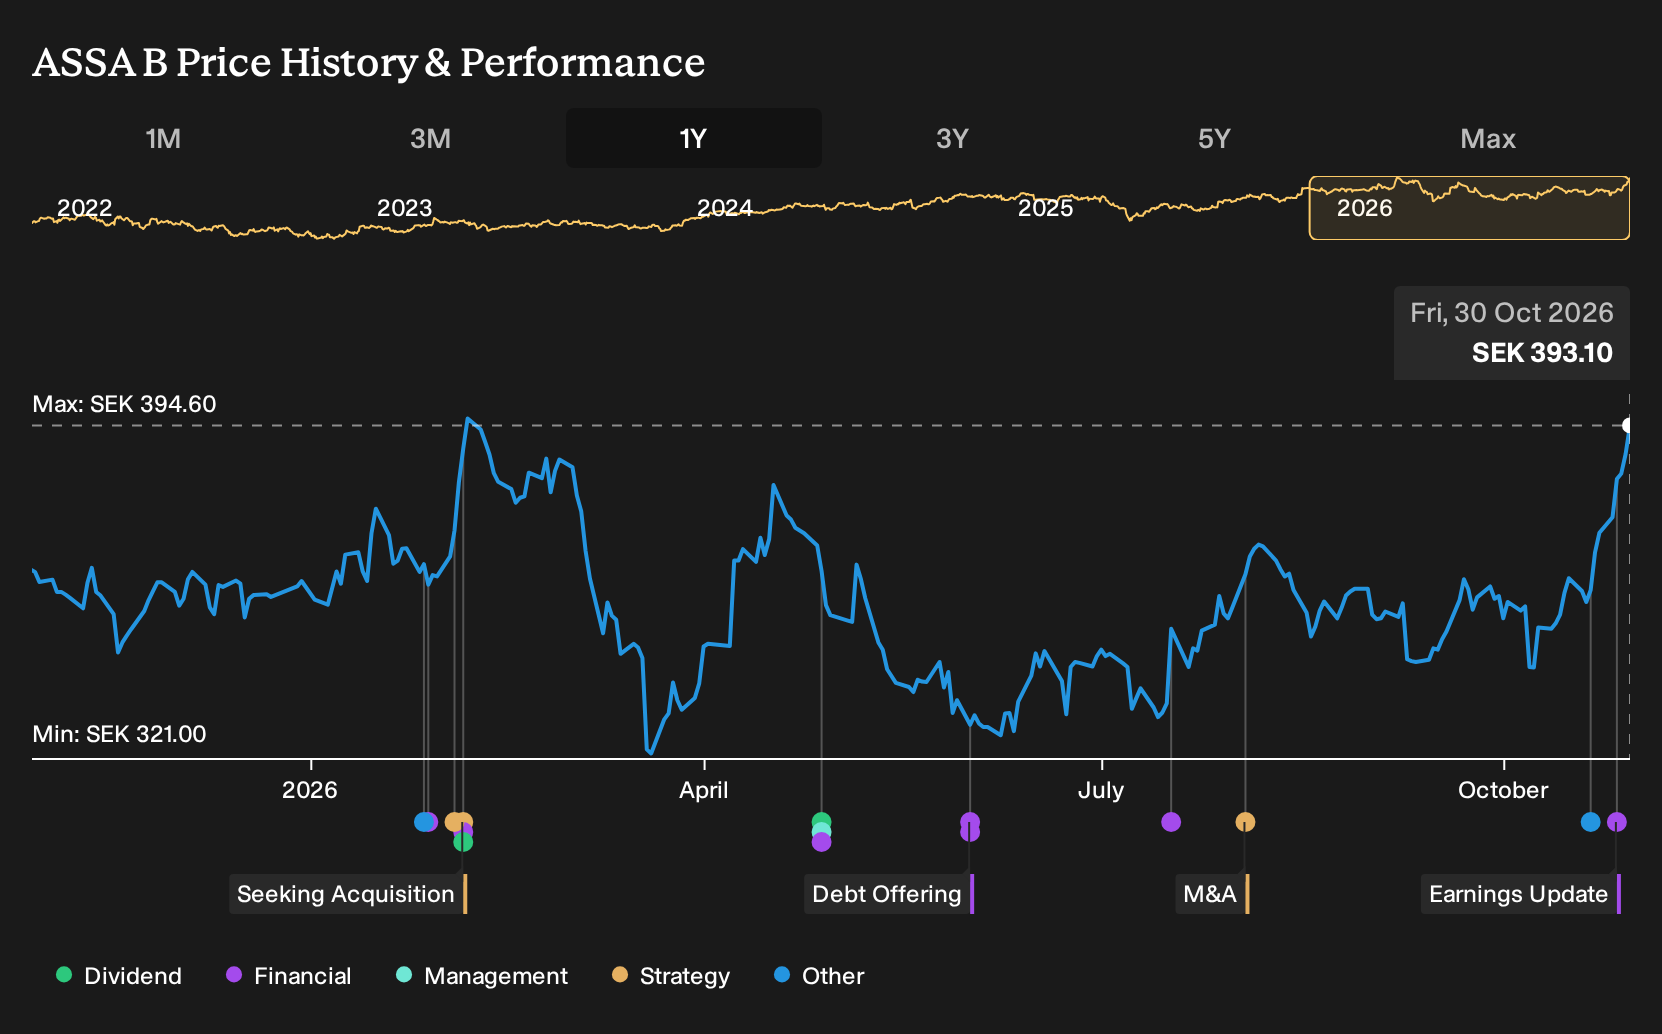
Among the recent announcements, the October 2026 earnings release itself is the clearest reference point for those catalysts. Higher basic earnings per share from continuing operations, at SEK 4.24 in the quarter and SEK 11.41 for nine months, ties directly into the thesis that ASSA ABLOY can convert its mix into firmer profitability.
For you as a shareholder, that report helps track whether faster growing electromechanical products and recurring software and services are enough to counterbalance weaker residential and logistics exposed lines. It also gives more data on how cost efficiency programs and acquisitions are feeding through to net income, while reminding you that FX and leverage remain key items to monitor over the next few reporting periods.
ASSA ABLOY's current analyst storyline points to revenues of SEK 192.7b and earnings of SEK 22.7b by 2029, based on assumed yearly top line growth of 8.4% and an earnings increase of SEK 6.3b from SEK 16.4b today.
Uncover why ASSA ABLOY's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Not every analyst reads the latest ASSA ABLOY report the same way. The most cautious voices focus on acquisition risk, especially the margin impact from Level Lock, and were only pencilling in about SEK 184.3b of revenue and SEK 22.0b of earnings by 2029. You can treat that more pessimistic path as one of several narratives, and then look at how updated figures might influence it.
Explore 5 other ASSA ABLOY fair value estimates, including one that suggests as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your instincts.
- A great starting point for your ASSA ABLOY research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASSA ABLOY. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASSA ABLOY's overall financial health at a glance.
Looking for more investment ideas beyond ASSA ABLOY?
If the ASSA ABLOY story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you quickly surface other listed businesses that fit the type of earnings profile and risk balance you care about.
- For investors who care most about quality at a reasonable price, scan a curated universe of companies with strong cash generation and supportive fundamentals using the 204 high quality undervalued stocks.
- If capital preservation and smoother portfolio swings matter more to you than headline growth, narrow your search to businesses with sturdier financial profiles by running the 218 resilient stocks with low risk scores.
- When you want to get ahead of the crowd and research less-followed opportunities, broaden your watchlist with the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com