
Altra Fastigheter (OM:ALTRA) Profit Jump Draws Attention, Is The Stock Still Undervalued?
Altra Fastigheter (OM:ALTRA) just paired a major share buyback with a sharp jump in profitability, giving investors fresh numbers to reassess the real estate stock’s risk and reward profile.
Recent trading suggests investors are starting to price in that profitability shift. The share price is at SEK78.05, with a 1 month share price return of 11.58% and a year to date share price gain of 7.29%. However, the 1 year total shareholder return is almost flat at 0.64% and the 5 year total shareholder return is down 38.92%, which hints at improving momentum after a tougher multi year stretch.
Scan how Altra Fastigheter compares with other real estate shares showing improving profitability and fresh price momentum by checking our hand picked 204 high quality undervalued stocks in the sector.
Altra Fastigheter has just combined a large buyback with a jump in earnings, which puts you at a crossroads. Is this already the better entry point, or is it more sensible to wait for potentially lower prices before running the numbers?
Most Popular Narrative: 9.9% Undervalued
Altra Fastigheter's most followed narrative pegs fair value at SEK86.60, which sits above the latest close at SEK78.05 and presents the buyback as part of a broader earnings and balance sheet story.
Refinancing more than one third of debt in 2025, lowering the average interest rate from 5.0% to 4.2% and maintaining an equity ratio of 41.7% provides financial flexibility that can influence earnings through lower interest costs and capacity for selective growth investments.
See why 2 investors see Altra Fastigheter as 10% undervalued.
Result: Fair Value of SEK86.60 (UNDERVALUED)
Still, the narrative can crack if Finland continues to weigh on valuations, or if higher vacancy and slower reletting drag on rental income and cash flows.
Find out about the key risks to this Altra Fastigheter narrative.
Another View: What Multiples Say About Altra Fastigheter
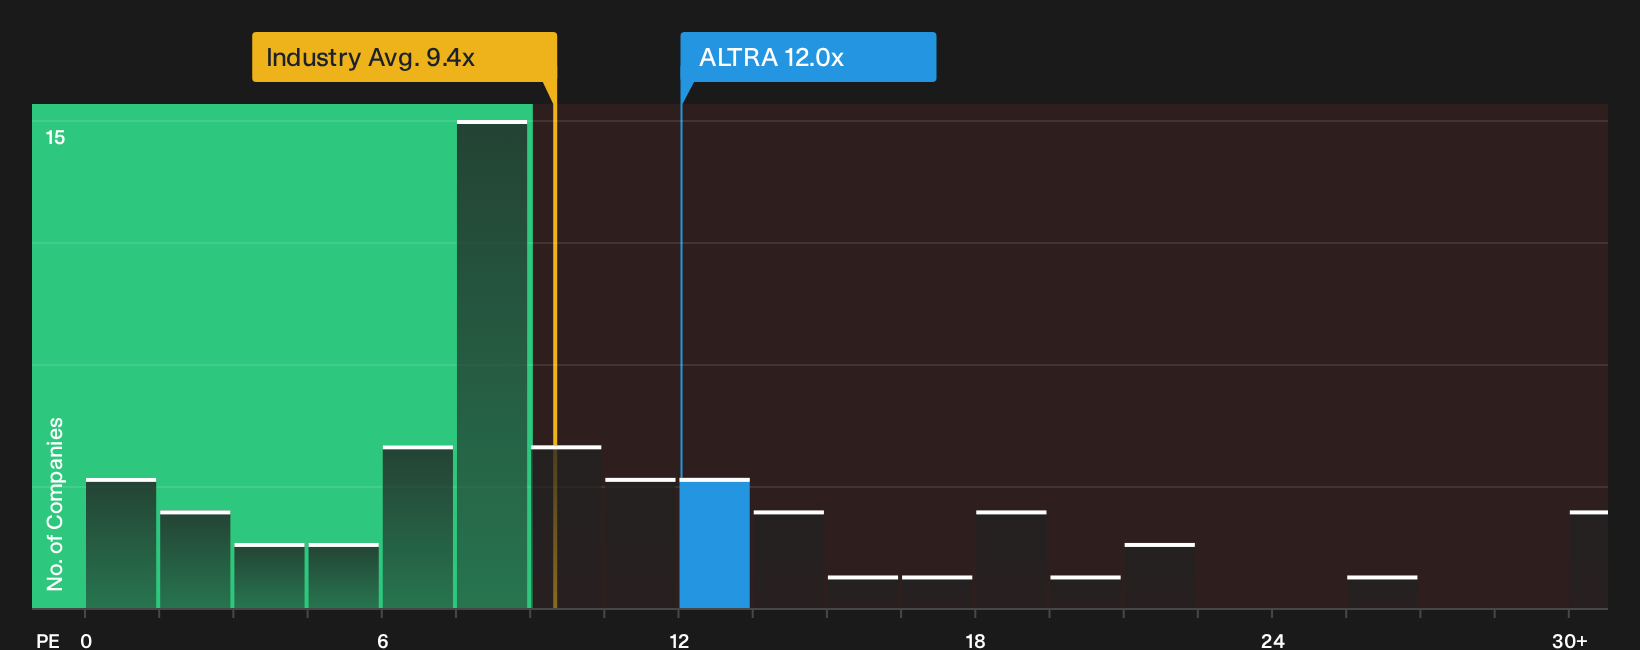
Altra Fastigheter might look cheap against its own fair value narrative, yet its 12x P/E is richer than the Swedish real estate industry at 9.4x, even if it sits below peer average at 17.2x and under the fair ratio of 14.6x. Is that gap a cushion or a warning sign for you?
To see how those P/E gaps compare with earnings quality and sector risks, it helps to walk through the valuation breakdown in more detail, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed about whether Altra Fastigheter’s momentum and valuation gaps are enough to act on right now, or whether caution makes more sense. To put the latest figures in context and weigh both the concerns and the potential upside, check 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Altra Fastigheter?
If Altra Fastigheter has sharpened your focus on value and risk, do not stop here. Use the screener to pressure test your next move with clear, comparable ideas.
- Target resilient income by reviewing companies with strong payouts and solid fundamentals using the 221 dividend fortresses.
- Hunt for quality at a discount by scanning financially sound businesses trading below their estimated worth through the 204 high quality undervalued stocks.
- Stack the odds in your favor by filtering for companies that pair healthy balance sheets with durable fundamentals in the list of solid balance sheet and fundamentals (199 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com