
Will Third Quarter Earnings Change Athabasca Oil Stock Narrative
- Athabasca Oil reported third quarter 2026 revenue of C$360.89 million and net income of C$77.81 million, with basic earnings per share from continuing operations of C$0.16.
- The business paired higher quarterly revenue and profit with slightly lower petroleum and natural gas production volumes. This highlights the importance of pricing, mix and cost control in Athabasca Oil’s earnings profile.
- We will now assess how Athabasca Oil’s higher quarterly profit on slightly lower production shapes the existing investment narrative around its assets.
Scan the earnings-driven momentum around Athabasca Oil and compare it with 4 high quality undervalued stocks that pair solid fundamentals with potential mispricing in the market.
Athabasca Oil Investment Narrative Recap
To own Athabasca Oil, investors need to be comfortable with a production story that leans heavily on execution at Leismer, Corner Phase 1 and Duvernay. The latest quarter shows that earnings can hold up even when output softens slightly, as long as pricing, mix and costs cooperate. That outcome supports the idea that the core assets can fund the plan, rather than undermine it.
The short term swing factor still appears to be how cleanly Athabasca Oil delivers its expanded capital program without eroding free cash flow. The main risk has not materially shifted. Slippage in timing or budget on these projects, combined with already lower profit margins versus last year, would pressure flexibility until larger volumes are online.
The third quarter 2026 earnings release is a key update to consider. Revenue of C$360.89 million and net income of C$77.81 million came alongside slightly softer production at 38,602 boe/d for the quarter. That combination of stronger quarterly profit with modestly lower volumes puts attention squarely on how effectively the firm is managing price exposure and operating costs while it spends on growth.
For the nine months, Athabasca Oil reported revenue of C$1,008.73 million and net income of C$190.27 million, with earnings per share flat year on year at C$0.39. That plateau in per share profit, during a period of heavier capital spending and lower production, highlights both the opportunity and the risk. Execution on Leismer, Corner Phase 1 and Duvernay remains the operational hinge for any potential future earnings acceleration.
Athabasca Oil's current narrative links analyst expectations of 22.0% yearly revenue growth over the next three years and a move in earnings from about C$228.7 million today to a consensus of C$554.9 million by 2029, implying roughly a 2.4x increase in profit, with a longer range forecast that points to C$2.3b in revenue and C$554.9 million in earnings by 2029.
Uncover why Athabasca Oil's fair value aligns with its current price.
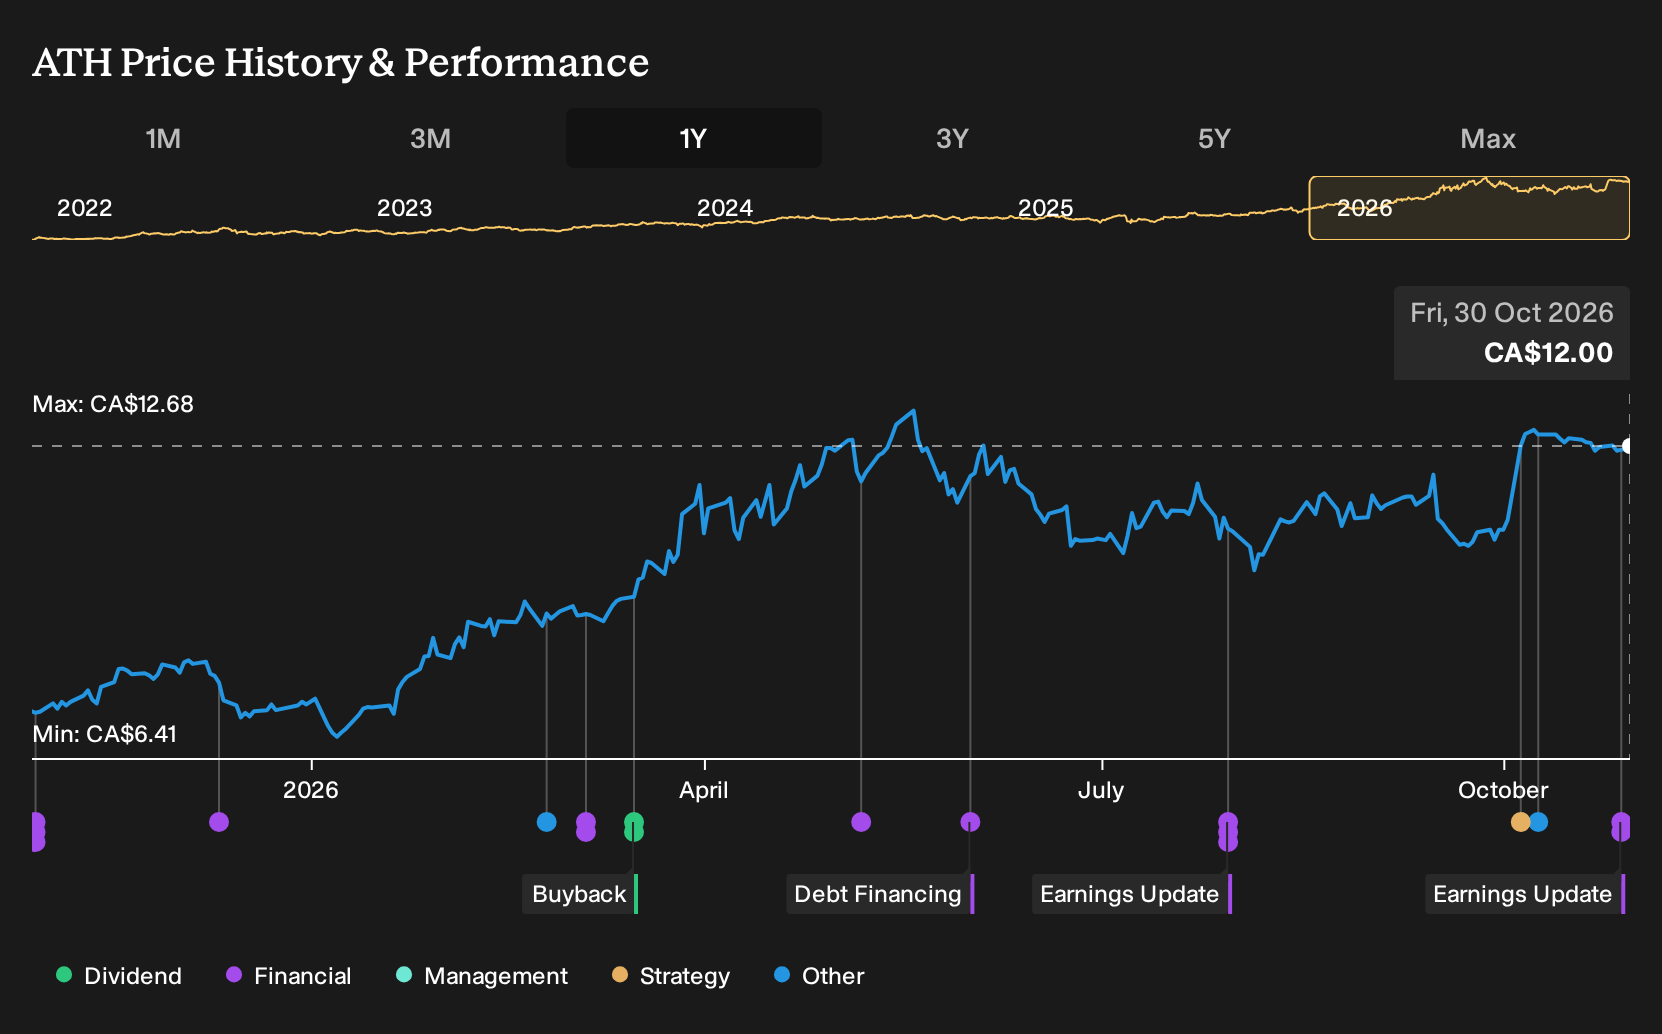
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight C$10.81 to C$12.10 band, which already shows how even a small sample can produce different views. Set that beside execution risk around Athabasca Oil’s capital program and shifting confidence, and you are reminded to compare several perspectives before relying on any single one.
Explore 2 other Athabasca Oil fair value estimates, including one that suggests it could be worth as much as CA$12.10.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Athabasca Oil research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Athabasca Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Athabasca Oil's overall financial health at a glance.
Looking for more Athabasca Oil style ideas?
If Athabasca Oil has sharpened your focus on earnings quality, balance sheets and execution risk, broaden that lens across the wider market using the Simply Wall St Screener.
- For investors who want potential mispricing backed by solid fundamentals, scan the market using our 4 high quality undervalued stocks and see where disciplined cash generation meets a discounted tag.
- If capital preservation sits high on your list, start with companies that carry fewer red flags by reviewing our 9 resilient stocks with low risk scores and narrow in on businesses with more resilient profiles.
- When you are hunting for quality beyond the usual tickers, cast a wider net with our 8 high quality undiscovered gems and surface lesser known stocks that still post strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com