
SHIFT (TSE:3697) Expands Its Financial Remit, Is The Valuation Already Full?
SHIFT stock: governance changes and a wider financial remit
SHIFT (TSE:3697) has put governance and business scope in the spotlight after announcing the planned retirements of two directors, alongside a proposal to broaden its Articles of Incorporation to include investment related financial services.
The latest governance announcements land after a sharp 30.22% 1 month share price return and a 27.85% 3 month share price gain for SHIFT. However, the 5.75% 1 year total shareholder return contrasts with a much weaker 3 year total shareholder return that declined 39.53%, suggesting that recent momentum follows a more difficult longer track record.
Spot emerging patterns around SHIFT by scanning the hand picked 69 high quality undiscovered gems that could be reacting to similar governance shifts and new business ambitions.SHIFT now blends a software testing engine, new financial ambitions and a share price that has climbed sharply in recent months. The next question is whether that mix is actually priced fairly today.
Preferred P/E multiple of 38.6x: Is it justified for SHIFT?
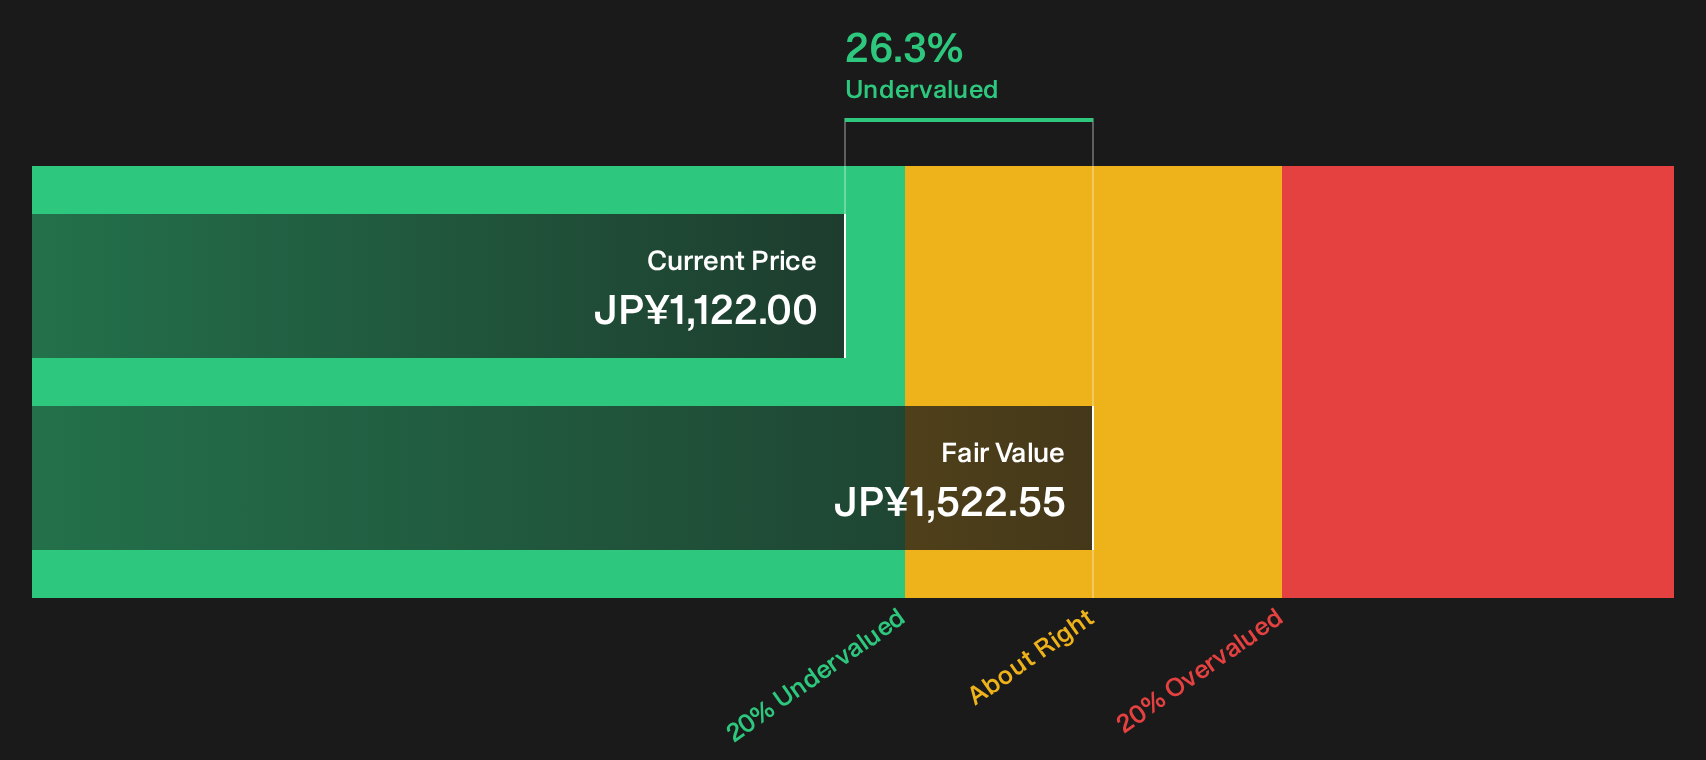
On headline valuation, SHIFT trades on a P/E of 38.6x, which is rich against peers even though the share price sits at ¥1,122 and the stock is flagged as trading 26.3% below an internal fair value estimate based on discounted cash flows.
The P/E ratio compares the current share price to earnings per share and effectively shows how many years of current profits investors are paying for. For a software quality assurance group like SHIFT, that multiple often reflects how the market weighs forecast earnings growth, perceived resilience of cash flows and the credibility of management execution.
Here, the market is paying a higher price for those profits than for peers. The P/E of 38.6x is described as expensive versus the peer average of 19.3x and also expensive compared to the broader JP IT industry average of 16x. Yet against an estimated fair P/E of 41.7x from the SWS model, the same multiple is described as good value. This indicates that if earnings trends and forecast growth of 37.2% per year materialise as expected, sentiment could logically shift toward that higher fair level.
The gap between the current 38.6x and the estimated fair P/E of 41.7x is not large in absolute terms. However, it reinforces that the present valuation already bakes in solid profit expansion and better returns on equity than the 17.5% recorded today. To justify a premium of this size versus the industry, SHIFT needs the forecast improvement in earnings quality and the projected return on equity of 28.6% in three years to hold up, or the P/E could end up feeling stretched relative to sector norms.
Explore the SWS fair ratio for SHIFT.
Result: Price-to-earnings of 38.6x (OVERVALUED)
Still, SHIFT carries clear pressure points, including a premium P/E against peers and a much weaker 3 year shareholder return that could limit enthusiasm.
Find out about the key risks to this SHIFT narrative.
Another view on SHIFT's value using the SWS DCF model
The P/E story paints SHIFT as expensive against peers, yet the SWS DCF model points in the opposite direction. At ¥1,122, the shares sit against an estimated fair value of ¥1,522.55, which implies the cash flow view frames the stock as undervalued rather than stretched.
The contrast is sharp. One lens compares SHIFT to what the market pays for other IT businesses today, while the DCF lens ties value to the cash it is expected to generate over time. If both are using the same earnings forecasts, which yardstick do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHIFT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by SHIFT's rich P/E and discounted DCF story. Use that tension as a prompt to move fast, examine the underlying data in detail and test your own thesis against the balance of 2 key rewards and 2 important warning signs.
Looking for more SHIFT style investment ideas?
If SHIFT has your attention, do not stop here. Broaden your watchlist with other focused ideas that match the kind of risk and reward trade offs you care about.
- Target stronger downside protection by scanning a curated group of resilient companies through the 23 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the hand picked 16 high quality undervalued stocks that pair fundamentals with more modest pricing.
- Build a steadier income stream by checking out the yield focused picks inside the 28 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com