
Hospital Contract Win Could Be A Big Moment For Implenia Stock (SWX:IMPN)
- Implenia has been appointed total contractor for the new Schaffhausen Hospitals building in Switzerland, a multifunctional healthcare project worth about SFr165m that is scheduled to start construction in 2027 after final approval.
- The Schaffhausen contract adds a sizable, long-duration healthcare project to Implenia's workload. It reinforces the company's focus on complex social infrastructure where design, execution risk and long-term client relationships matter for earnings quality.
- The next area of attention is how Implenia's investment narrative could be influenced by this SFr165m Schaffhausen hospital contract win.
Scan how other listed builders are positioned for complex social infrastructure by checking out the curated list of solid balance sheet and fundamentals (199 results) alongside Implenia's latest hospital contract win.
Implenia Investment Narrative Recap
To own Implenia, you need to believe the pivot toward complex projects and higher margin services can translate a CHF 8.5b order book and a 7.9% precalculated margin into steadier EBIT and cash generation. The Schaffhausen hospital contract fits that story but is not large enough on its own to redefine it. The more immediate swing factor remains consistent delivery on existing major projects.
The biggest operational risk still sits in the seasonally weak first half cash profile and a 23.4% adjusted equity ratio that has not reached the 25% target. If working capital timing turns less friendly or profitability softens, balance sheet progress could slow, financing costs could increase and the equity story could feel more fragile.
One of the more relevant reference points here is management’s focus on higher margin, specialized segments. Healthcare and laboratory buildings, data centers and property related services are cited as key areas, backed by CHF 10m to CHF 20m of planned growth investment in 2026. The Schaffhausen project falls neatly into that specialization effort around complex social infrastructure.
For you as a shareholder or potential investor, the link is practical. Each large, complex contract like Schaffhausen asks Implenia to prove the benefits of its digital tools, value assurance programs and lean initiatives in real project outcomes. Consistent execution supports the case for earnings growth, stronger free cash flow and eventually a higher equity ratio, while any stumble would feed directly into the existing risk list rather than create a new one.
What The Schaffhausen Contract Means Against Implenia’s Forecasts
Implenia's Schaffhausen hospital win sits against a set of analyst assumptions that already bake in measured expansion in both revenue and profitability rather than a step change from any single project. Analysts currently model revenue growing by 4.8% a year over the next three years, profit margins rising from 2.5% today to 3.2% in that period, and earnings moving from CHF 84.0 million today to CHF 126.7 million by 2029 based on a broadly aligned consensus view.
On those numbers, the hospital contract looks more like incremental support for an existing story than a rewrite of the script. The earnings path analysts describe implies an increase of about CHF 42.7 million from current levels to the 2029 forecast. This would need to be delivered through a mix of complex infrastructure projects like Schaffhausen, ongoing higher margin service activity and the targeted CHF 10 million to CHF 20 million of growth investment planned for 2026 rather than through one flagship job alone.
Implenia's narrative projects CHF 3.9b revenue and CHF 126.7 million earnings by 2029. This requires 4.8% yearly revenue growth and an earnings increase of about CHF 42.7 million from CHF 84.0 million today.
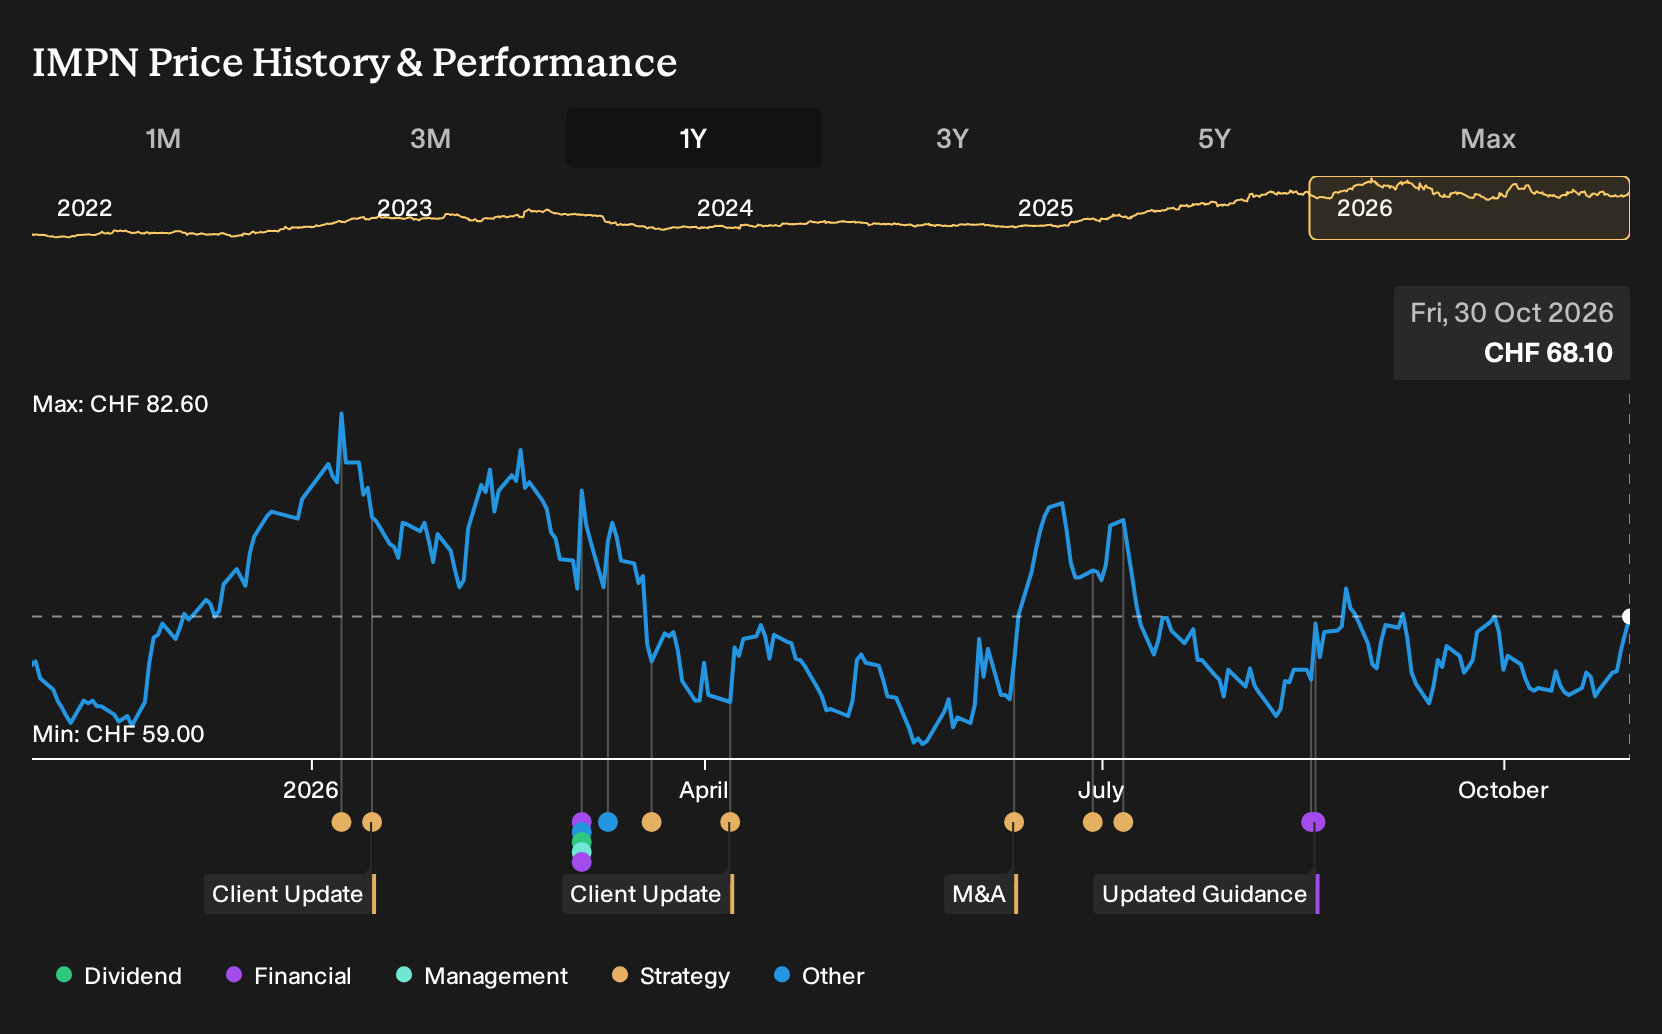
Uncover why Implenia's fair value indicates a 29% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view treats Implenia’s growth push as the real catalyst. The most optimistic analysts were already pencilling in revenue of about CHF 4.2b and earnings of roughly CHF 137.8 million by 2029, before this Schaffhausen hospital win. You can read those forecasts as a much bolder story that the new contract might yet reshape.
Explore 2 other Implenia fair value estimates, including one that suggests there may be as much as 47% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Implenia research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Implenia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Implenia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Implenia?
If you want to pressure test your view on Implenia against other opportunities, use the Simply Wall St Screener to scan for businesses with the balance sheets, dividends or valuations that fit your own playbook.
- For investors who care most about resilience and financial strength, start with a curated 218 resilient stocks with low risk scores that already clear a tight risk filter.
- If income is a priority and you want yields that work harder, compare Implenia with a hand picked set of 221 dividend fortresses built around higher payout profiles.
- When you are hunting for quality at a sensible entry point, line Implenia up against a focused group of 614 high quality undiscovered gems that combine fundamentals with under the radar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com