
Is Omnicell (OMCL) Undervalued On Raised Guidance And Stronger Q3 Margins?
Omnicell (OMCL) just posted third quarter 2026 results that beat its own guidance, with margin gains tied to Titan XT hardware, OmniSphere contracts, and tighter cost control catching investor attention.
Despite the guidance raise, Omnicell’s share price has slipped over the past week, with a 7 day share price return of 2.91% and a 1 day move that was slightly lower. However, the 1 month share price return of 9.08% hints at improving momentum after a tougher year to date. Over a longer horizon, total shareholder return of 9.17% over 1 year and 20.40% over 3 years contrasts with a 5 year total shareholder return that declined 79.33%. Recent news around Titan XT, OmniSphere and higher earnings guidance is therefore being weighed against a much weaker longer term track record.
Compare Omnicell’s rebound with other healthcare tech opportunities and scan a hand picked 34 healthcare AI stocks list that may also be benefiting from software heavy, automation focused demand shifts.
Omnicell has rallied off the lows, yet a 5-year return that declined 79.33% still hangs over a business posting higher earnings guidance. Has the recent rebound already captured that reset, or is the gap still wide?
Most Popular Narrative: 40% Undervalued
Omnicell last closed at $36.65, while the most followed narrative pegs fair value at about $61.29, suggesting a wide gap that investors are now stress testing against fresh earnings and guidance.
The continued rollout and adoption of the cloud-native OmniSphere platform across Omnicell's customer base will simplify enterprise-wide medication management, make adding new features and integrating advanced analytics much easier, and accelerate the company's transition to higher-margin, recurring SaaS-based revenues, supporting improved revenue predictability and net margins.
See why 6 investors see Omnicell as 40% undervalued.
Result: Fair Value of $61.29 (UNDERVALUED)
Still, Omnicell’s story can change quickly if tariff costs bite harder than expected or if hospital capital budgets tighten and delay major automation projects.
Find out about the key risks to this Omnicell narrative.
Another View On Omnicell’s Valuation
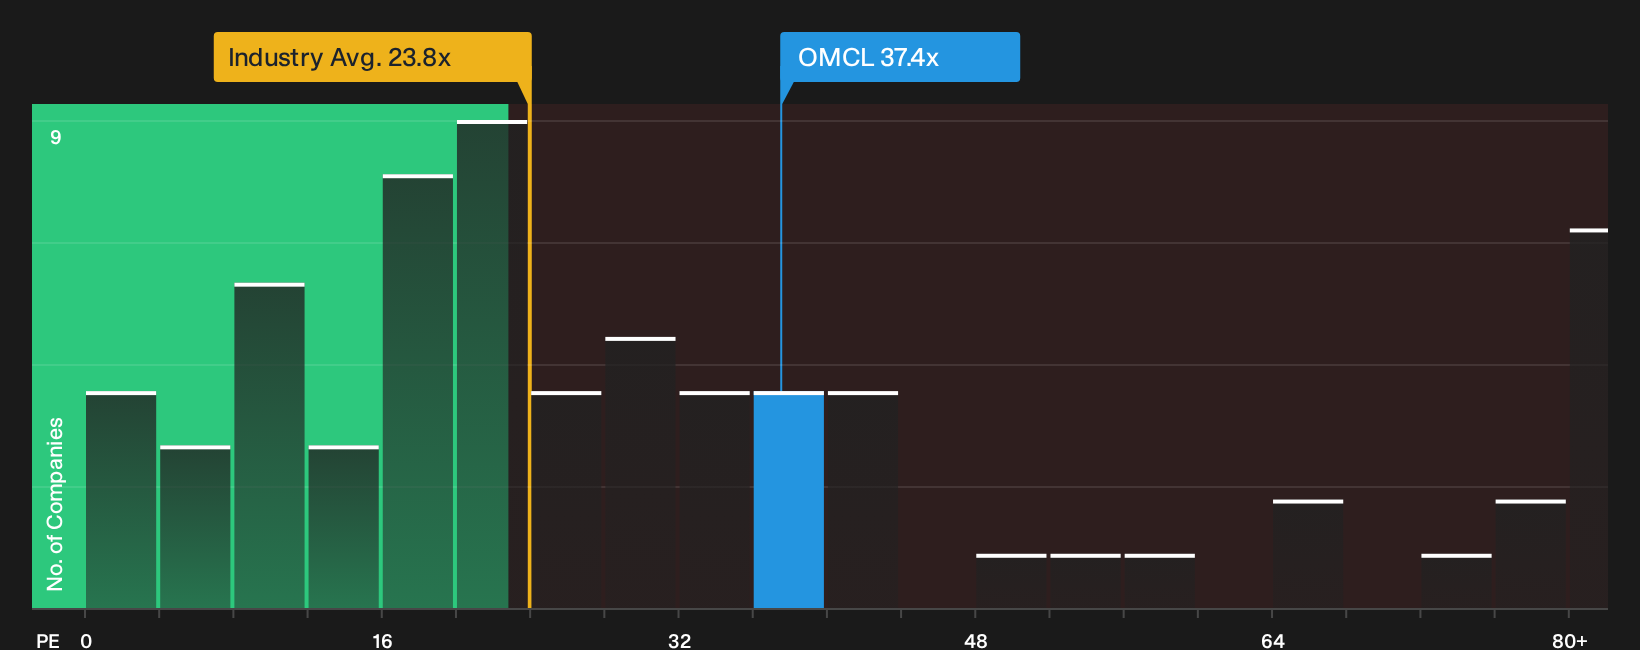
The analyst narrative and our fair value estimate frame Omnicell as undervalued at around a 40% discount, yet the market is still paying a rich P/E of 37.4x versus 23.8x for the US Medical Equipment sector, 34.2x for peers, and a fair ratio of 23.7x. Is that a margin of safety or a premium that could shrink?
For investors weighing this P/E gap against the fair value estimate, it can help to see how the numbers stack up in one place, along with what they might imply for valuation risk or opportunity See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals in the Omnicell story so far. If you want your view grounded in numbers rather than headlines, begin with the upside case in 4 key rewards.
Looking for more investment ideas beyond Omnicell?
Do not stop at Omnicell. Use the Simply Wall Street Screener to surface fresh ideas so your watchlist reflects where capital could work hardest next.
- Target stability first by reviewing a 29 resilient stocks with low risk scores that aims to keep potential downside in sharper focus.
- Hunt for mispriced quality and scan a 19 high quality undiscovered gems that might not yet be crowded with attention.
- Prioritise financial strength and filter for a list of solid balance sheet and fundamentals (24 results) that can better withstand tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com