
Nine Month Earnings Beat Could Be A Game Changer For Endesa (BME:ELE)
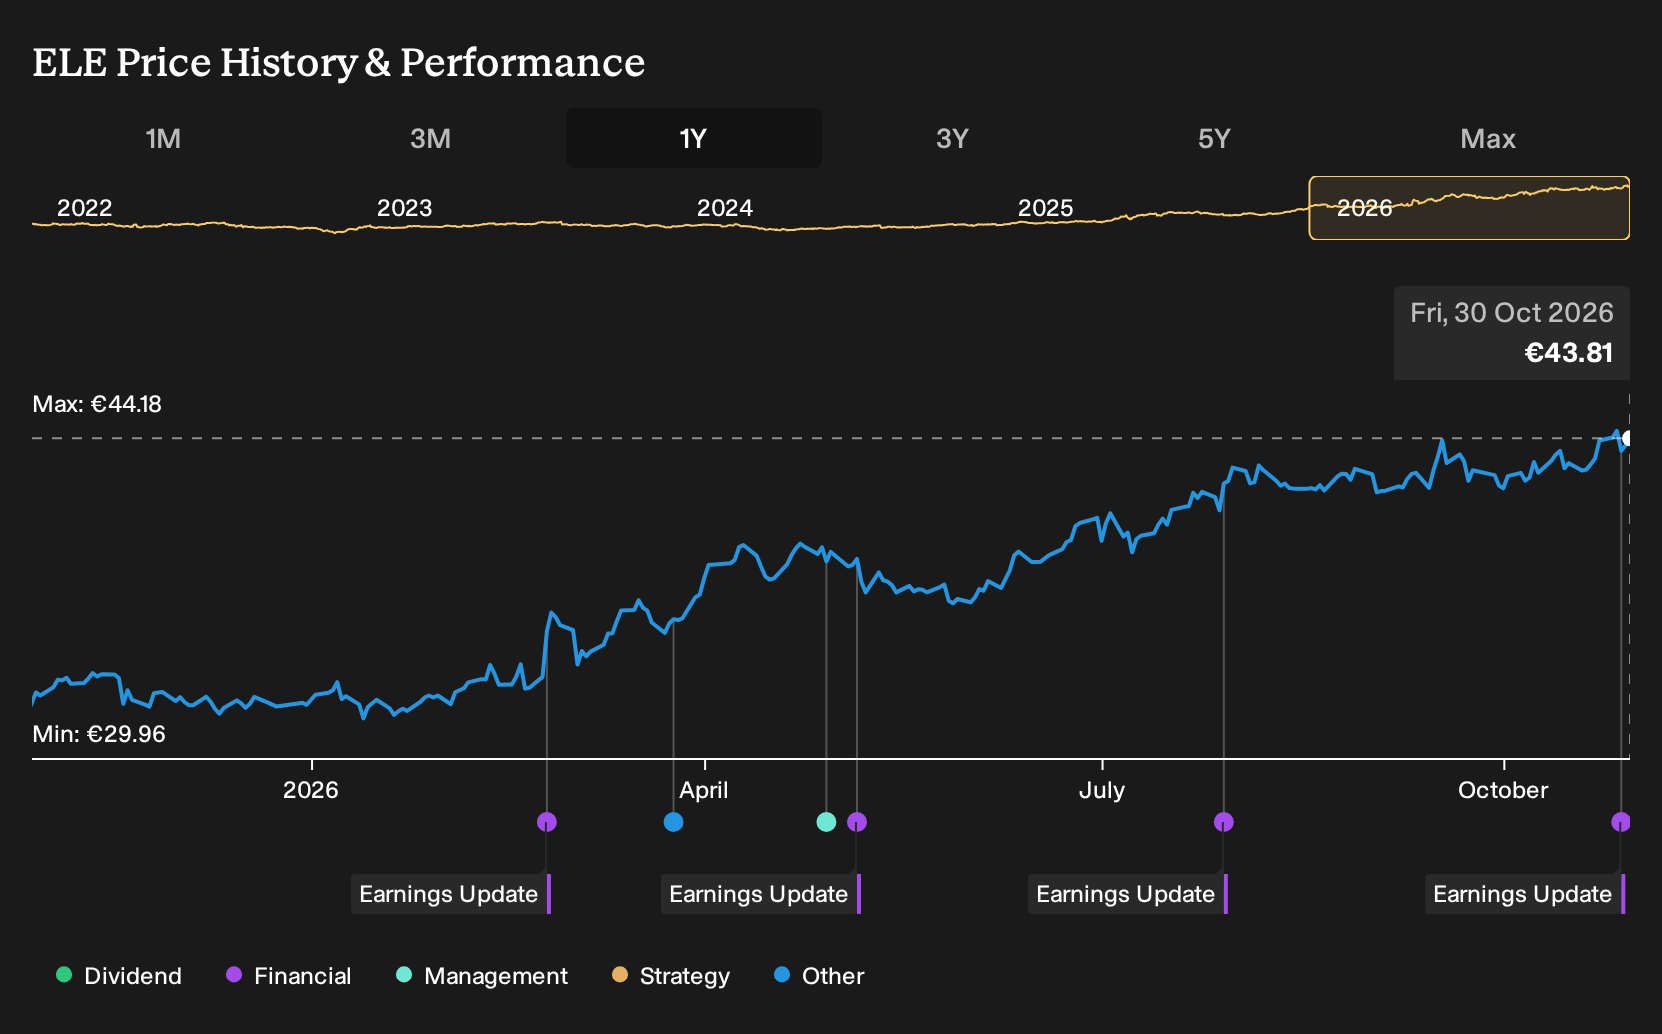
- Endesa reported earnings for the nine months to 30 September 2026, with sales of €17,122 million, revenue of €17,389 million, and net income of €1,962 million, all above the levels reported a year earlier.
- The utility also reported higher basic and diluted earnings per share from continuing operations at €1.883 compared with €1.616 a year ago, which points to stronger profit per share alongside its larger top line.
- Investors may now reassess how Endesa's higher earnings per share from continuing operations affect the existing investment narrative they have been using.
Endesa Investment Narrative Recap
For an investor to stay with Endesa, the belief usually hinges on a regulated and contracted earnings mix that aims to keep cash flows relatively steady while funding grids and renewables. The latest nine month figures show higher sales, revenue and net income year on year, which supports that narrative rather than changing it. In the short term, the key swing factor is still how Spain’s distribution framework and grid investment timing translate into allowed returns.
The biggest near term risk remains execution and funding of heavy CapEx against a debt load already flagged as high and a dividend history described as unstable. Earnings per share from continuing operations at €1.883 compared with €1.616 give Endesa a little more room to work with, but do not remove those balance sheet and regulatory sensitivities.
The earnings release for the nine months to 30 September 2026 is the clearest recent datapoint to focus on. Sales of €17,122 million, revenue of €17,389 million and net income of €1,962 million, all above the prior year levels, indicate that Endesa is currently delivering on its plan to lean on regulated and contracted activities for around 85% of 2026 to 2028 EBITDA.
For you as a shareholder, the question is how this operational delivery lines up with expectations for grid CapEx and renewables. The reported uplift in basic earnings per share from continuing operations to €1.883 sits alongside ongoing cost efficiency efforts and a long investment cycle in networks and clean generation, while risks around high leverage, Spanish market demand and future allowed returns still shape the medium term catalyst mix.
Endesa's analyst narrative points to forecast revenues of €23.5b and earnings of €2.5b by 2029, based on 1.6% yearly revenue growth and an earnings uplift of about €0.1b from current earnings of €2.4b.
Uncover how Endesa's fair value indicates a 16% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view focuses on demand risk. The most optimistic Endesa analysts were pencilling in revenue of about €27.6b and earnings of €2.7b by 2029, far above the consensus €23.5b and €2.5b. Those projections came before this earnings update, so you may see those bullish expectations either reinforced or seriously questioned.
Explore 3 other Endesa fair value estimates, including one that suggests it could be worth as much as €44.30.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Endesa research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Endesa. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Endesa's overall financial health at a glance.
Looking For More Investment Ideas Beyond Endesa?
If Endesa's latest update has you rethinking how you spread risk and opportunity across your portfolio, it can help to line it up against other companies with different balance sheet strength, income profiles, and growth angles. A structured screener gives you a cleaner shortlist so you spend more time weighing fundamentals and less time sifting through noise.
The Simply Wall St Screener lets you filter for financial traits that matter to you, then compare those candidates side by side with Endesa's profile.
- For investors hunting for quality at a sensible price, you can start with companies that combine stronger fundamentals and valuation support through our 204 high quality undervalued stocks.
- If income is a key part of your plan, you can target stocks with robust yields and balance sheets that can support them by checking the 221 dividend fortresses.
- When capital preservation matters most, you can narrow your watchlist to businesses with steadier financial risk profiles via the 218 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com