
Should Earnings Beat Require Action From Abercrombie & Fitch Stock Investors?
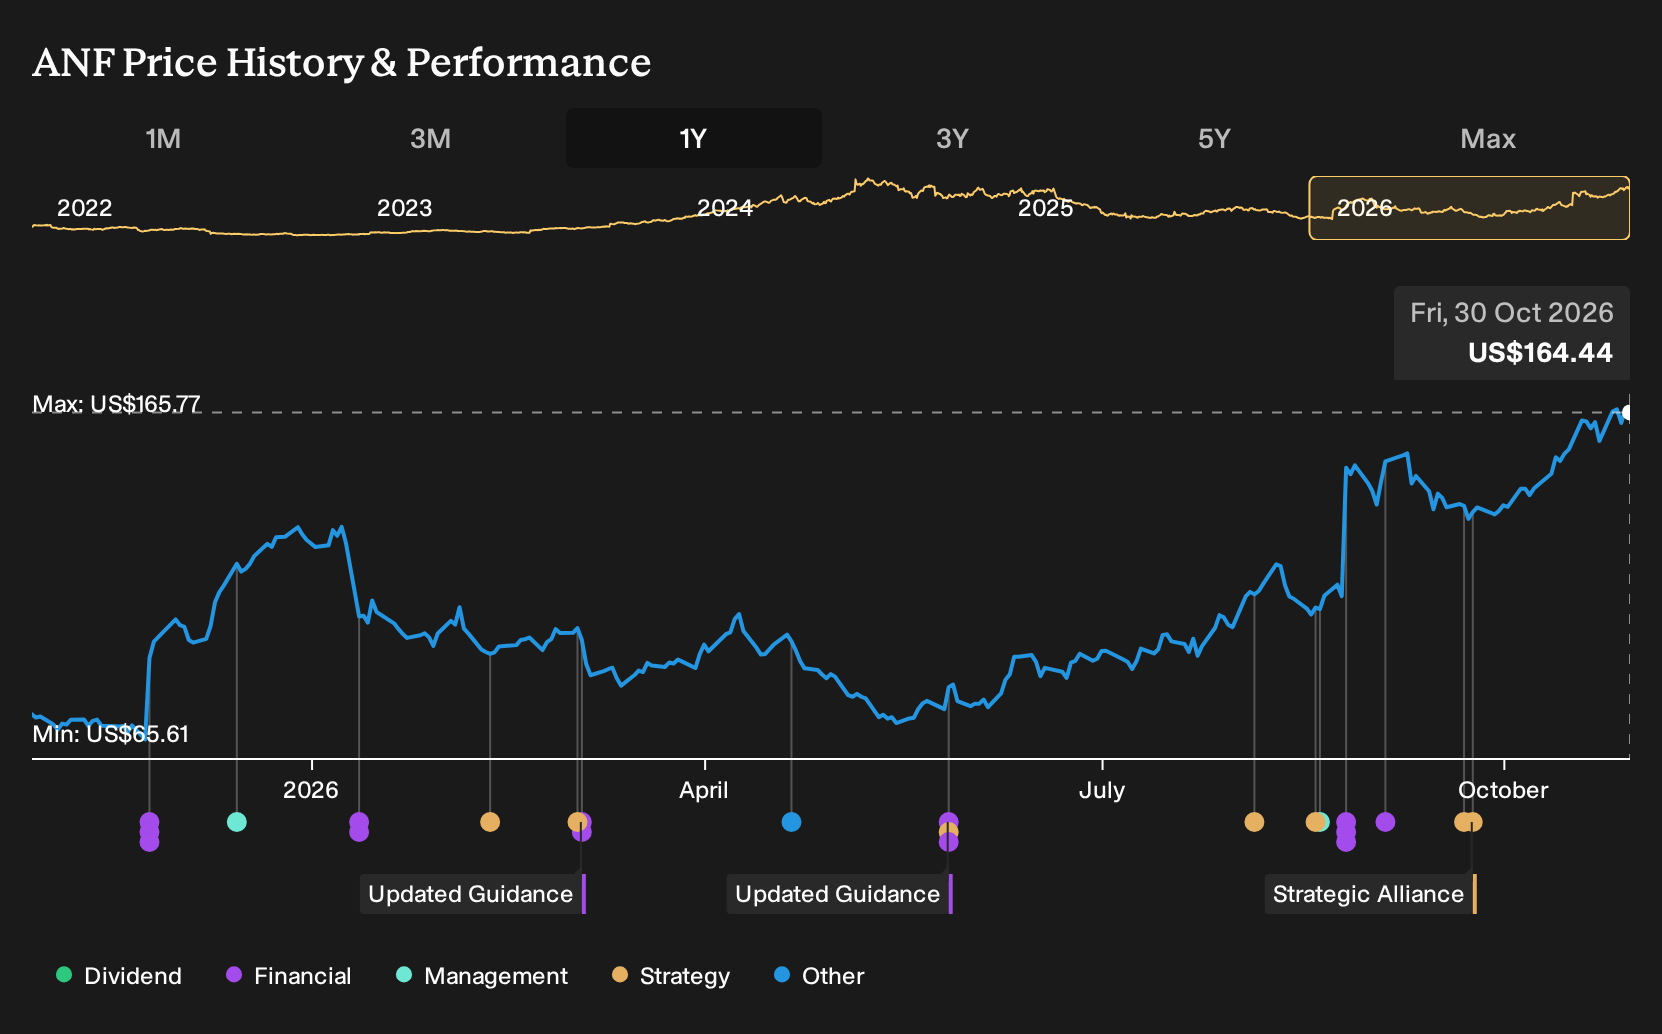
- Abercrombie & Fitch recently reported quarterly results that came in ahead of expectations, with a 63.2% gross margin, steady same store sales and an active share repurchase program supported by a solid balance sheet.
- The combination of strong profitability and aggressive buybacks, which lifted annual EPS growth to 76.3%, shows how Abercrombie & Fitch’s merchandising and capital allocation choices are working together to reshape earnings power.
- Next, the focus is on how Abercrombie & Fitch’s stronger margins and EPS growth could influence its broader investment narrative and risk profile.
Scan how Abercrombie & Fitch’s earnings story compares with other retailers lifting profitability and buying back shares by running the curated 33 high quality undervalued stocks before the next quarterly call lands.
Abercrombie & Fitch Investment Narrative Recap
To be comfortable owning Abercrombie & Fitch, you need to believe the current profitability levels are sustainable while tariff costs, international unevenness and reputational questions around value perception stay manageable. The recent beat on expectations supports that idea, but it does not fully answer how long tariff refunds or unusually strong gross margin support can last.
The near term catalyst sits in continued merchandising execution and efficient inventory control that keep gross margin resilient as ERP tools bed in and partnerships scale. The biggest risk is that EMEA and APAC softness lingers or worsens at the same time as tariff relief fades, which could squeeze earnings even if US demand holds.
The upcoming third quarter 2026 earnings call on 24 November is the key operational update linked to this news flow. Abercrombie & Fitch plans to walk through store expansion, partnership performance and progress on its repurchase program. That call will help you judge whether recent margin strength lines up with underlying demand or depends heavily on one off supports.
Attention naturally falls on how management frames tariff mitigation, international regions under pressure and any early learnings from the March 2026 merchandising ERP go live. Commentary around inventory visibility, markdown discipline and partner contributions will be central for anyone treating current EPS levels and share buybacks as a template for the next few years.
Abercrombie & Fitch’s current analyst setup points to revenues of US$6.2b and earnings of US$560.9 million by 2029, built on assumed yearly top line growth of 4.8% and an earnings increase of about US$24.9 million from the US$536.0 million reported today.
Uncover why Abercrombie & Fitch's fair value is consistent with its current price.
Exploring Other Perspectives
One alternate angle on Abercrombie & Fitch is far more focused on concerns about physical store exposure. The most bearish analysts were pencilling in about US$6.1b of revenue and US$576.7 million of earnings by 2029, yet still arrived at a US$137.93 price target. That gap shows how sharply views can differ, so treat this earnings beat as a prompt to explore several competing narratives.
Explore 4 other Abercrombie & Fitch fair value estimates, including one that suggests it could be worth just $163.55.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Abercrombie & Fitch research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Abercrombie & Fitch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Abercrombie & Fitch's overall financial health at a glance.
Looking For More Ideas Beyond Abercrombie & Fitch?
If Abercrombie & Fitch has sharpened your appetite for quality setups, use this as a springboard to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital protection is your priority, start with companies that our models flag for resilience and lower risk using the 29 resilient stocks with low risk scores.
- If you want businesses that combine balance sheet strength with sound fundamentals, filter for companies on the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for less crowded opportunities with strong fundamentals, cast a wider net through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com