
Learn Why The Bull Case For Otis Worldwide (OTIS) Could Change Following Service Led Growth
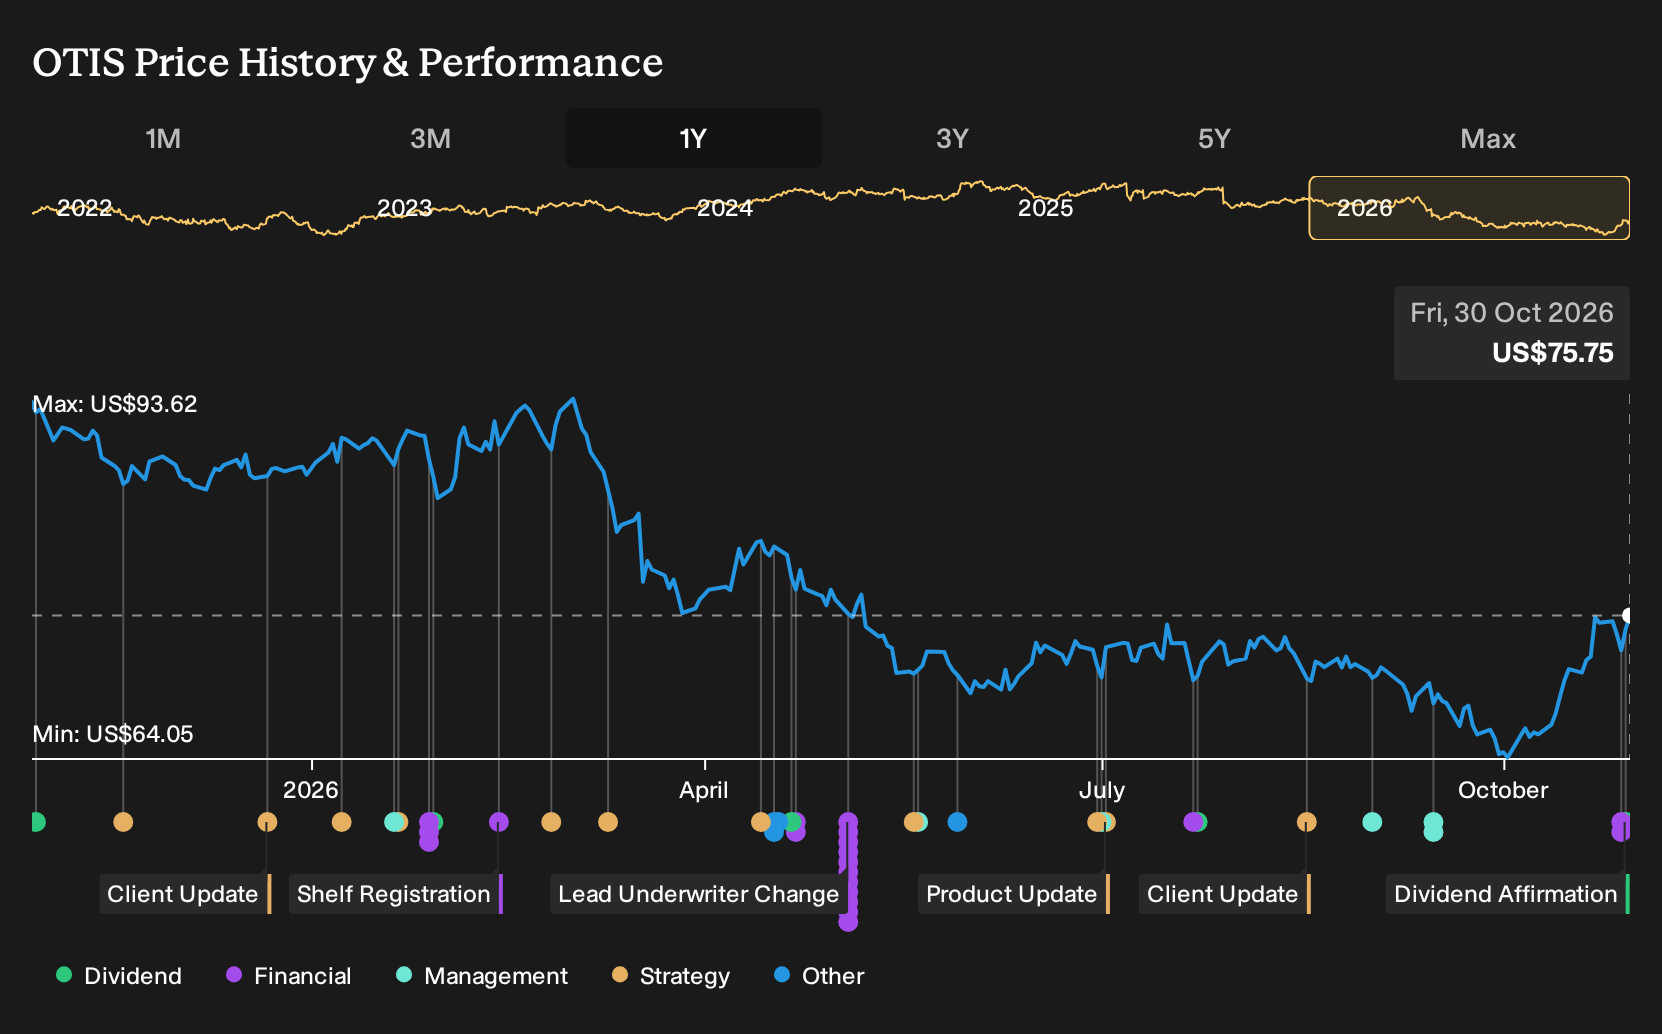
- Otis Worldwide reported Q3 2026 sales of US$3,914 million, net income of US$414 million and diluted EPS from continuing operations of US$1.08, and the board approved a quarterly dividend of US$0.44 per share payable in December 2026.
- Service led organic sales growth and a larger modernization backlog, alongside maintained 2026 net sales guidance of US$15.1 billion to US$15.3 billion, highlight that Otis Worldwide is leaning on recurring maintenance and upgrade demand rather than relying purely on new equipment orders.
- The company’s investment narrative could be influenced by stronger organic service growth and modernization driven earnings.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you need to be comfortable with a story built on service contracts and modernization work rather than chasing cycles in new installations. Q3 results, with US$3,914 million in sales and US$414 million in net income, support that service led tilt. The maintained 2026 net sales outlook of US$15.1b to US$15.3b suggests the recent update does not dramatically shift the near term narrative.
The short term swing factor still sits in how effectively Otis Worldwide can convert its large, connected service portfolio and modernization backlog into higher service margins without hurting retention. Pressure points remain around service margin compression, execution on AI pricing tools and service retention slipping from prior levels. Those issues look more important to watch than this quarter’s headline numbers.
The most relevant update for that story is the Q3 2026 earnings release. Management reported service led organic growth and a larger modernization backlog, alongside higher net income of US$414 million and diluted EPS from continuing operations of US$1.08 for the quarter. Those data points give you more concrete evidence about how the business mix is trending.
That mix matters for potential catalysts. Stronger organic service activity and growing modernization orders build multi year visibility, which can help offset softer new equipment demand in China and pockets of cost pressure. At the same time, investors still need to weigh execution risk around service retention, the US$50 million service excellence and productivity programs, and how quickly tools like AI driven pricing actually show up in reported margins.
Otis Worldwide's narrative projects US$17.5b revenue and US$2.0b earnings by 2029. This rests on analysts assuming 4.9% yearly revenue growth and an earnings increase of about US$400m from US$1.6b today.
Uncover why Otis Worldwide's fair value indicates a 14% potential upside to its current price and how that gap could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on a different catalyst for Otis Worldwide. They worry that extra service investment and technology spending could keep earnings closer to US$1.9b on roughly US$17.0b revenue by 2029. Those forecasts were set before this dividend affirmation and steady guidance, so expectations may still shift.
Explore 4 other Otis Worldwide fair value estimates, including one that suggests it could be worth just $73.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking For More Ideas Beyond Otis Worldwide?
Once you have a view on Otis Worldwide, it helps to line it up against other opportunities that match your goals for income, quality and risk. The Simply Wall St Screener lets you filter for businesses that fit your criteria in a few clicks.
- If you want income backed by strong fundamentals, use the screener to focus on companies with sustainable payouts and solid cash generation through 5 dividend fortresses.
- If value is your priority, narrow the field to financially healthy businesses trading below estimated worth by starting with 33 high quality undervalued stocks.
- If resilience matters most to you, filter for businesses with steadier risk profiles and durable balance sheets by scanning 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com