
Asian Growth Companies Insiders Are Backing In November 2026
In recent months, Asian markets have been navigating a complex landscape characterized by geopolitical tensions and fluctuating oil prices, while maintaining a focus on economic stability and growth. As investors seek to identify promising opportunities within this environment, companies with high insider ownership often signal confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 72.2% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 107.8% |
| SEERS (KOSDAQ:A458870) | 33.6% | 37.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 45.3% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 43.3% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
| ASE Technology Holding (TWSE:3711) | 25.8% | 39.5% |
Let's take a closer look at a couple of our picks from the screened companies.
RFHIC (KOSDAQ:A218410)
Simply Wall St Growth Rating: ★★★★★☆
Overview: RFHIC Corporation designs and manufactures radio frequency and microwave components for wireless infrastructure, commercial and military radar, and RF energy applications both in South Korea and internationally, with a market cap of ₩1.30 billion.
Operations: The company's revenue segments are composed of Rfhic with ₩131.44 billion, Rs Systems contributing ₩42.71 billion, Rf Materials at ₩38.13 billion, and Rfhic Us Corporation generating ₩19.17 billion.
Insider Ownership: 33.3%
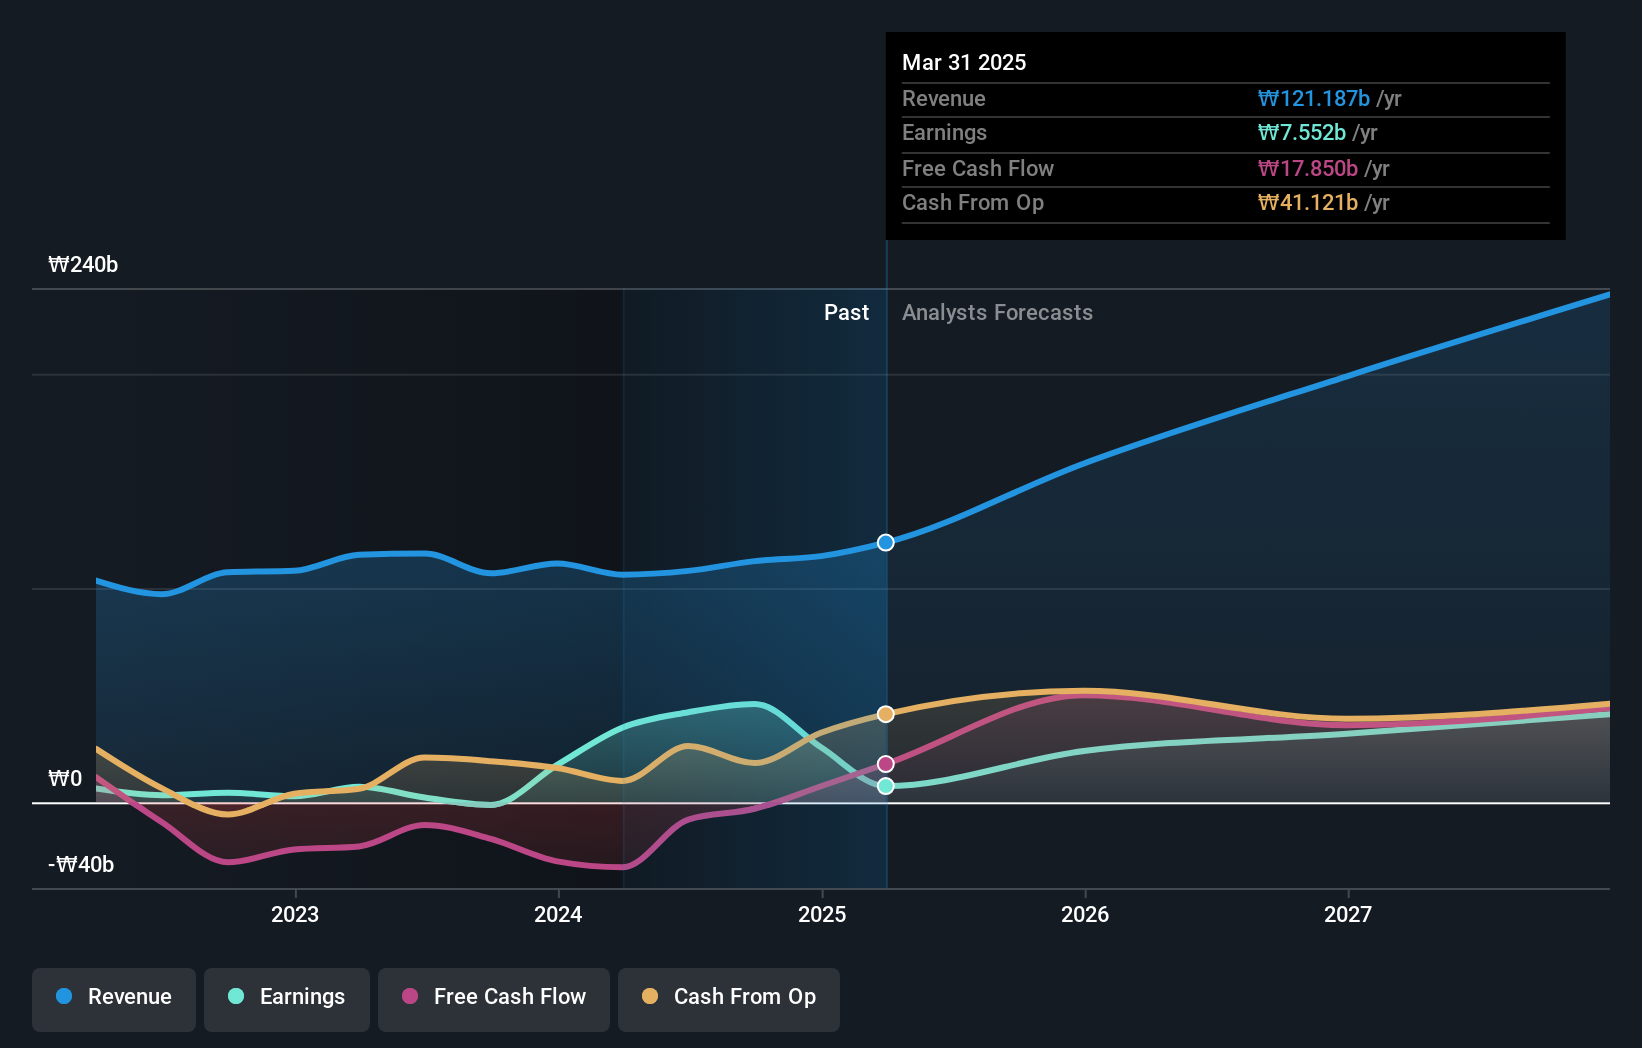
RFHIC is positioned as a growth company with high insider ownership in Asia, trading 6.9% below its estimated fair value. Analysts forecast that its earnings will grow significantly at 27.36% annually, outpacing the KR market's growth rate of 27.1%. Despite recent share price volatility, RFHIC's revenue is expected to increase by 28% per year, surpassing the market's average of 12.7%. Its Return on Equity remains modest at a forecasted 16.7%.
- Click to explore a detailed breakdown of our findings in RFHIC's earnings growth report.
- Our expertly prepared valuation report RFHIC implies its share price may be too high.
Metis TechBio (SEHK:7666)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Metis TechBio Co., Ltd. focuses on the research and development of AI-empowered nanomaterials for delivering active agents across carbon-based life forms in Chinese Mainland and the United States, with a market cap of HK$13.19 billion.
Operations: The company's revenue segment is primarily derived from the research and development of new nano materials, amounting to CN¥258.15 million.
Insider Ownership: 23.2%
Metis TechBio's revenue is projected to grow at 28.2% annually, outpacing the Hong Kong market. The company is expected to achieve profitability within three years, with earnings growth forecasted at a striking 81.42% per year. Despite recent share price volatility and low future Return on Equity (1.2%), strategic alliances with Eli Lilly could yield up to US$1.1 billion in milestone payments, enhancing its innovative AI-driven delivery platforms and R&D capabilities.
- Dive into the specifics of Metis TechBio here with our thorough growth forecast report.
- Our valuation report unveils the possibility Metis TechBio's shares may be trading at a premium.

Nanjing Vazyme Biotech (SHSE:688105)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Nanjing Vazyme Biotech Co., Ltd provides technology solutions in life science, biomedicine, and in vitro diagnostics with a market cap of CN¥11.67 billion.
Operations: Nanjing Vazyme Biotech Co., Ltd generates revenue through its offerings in life science, biomedicine, and in vitro diagnostics.
Insider Ownership: 14.9%
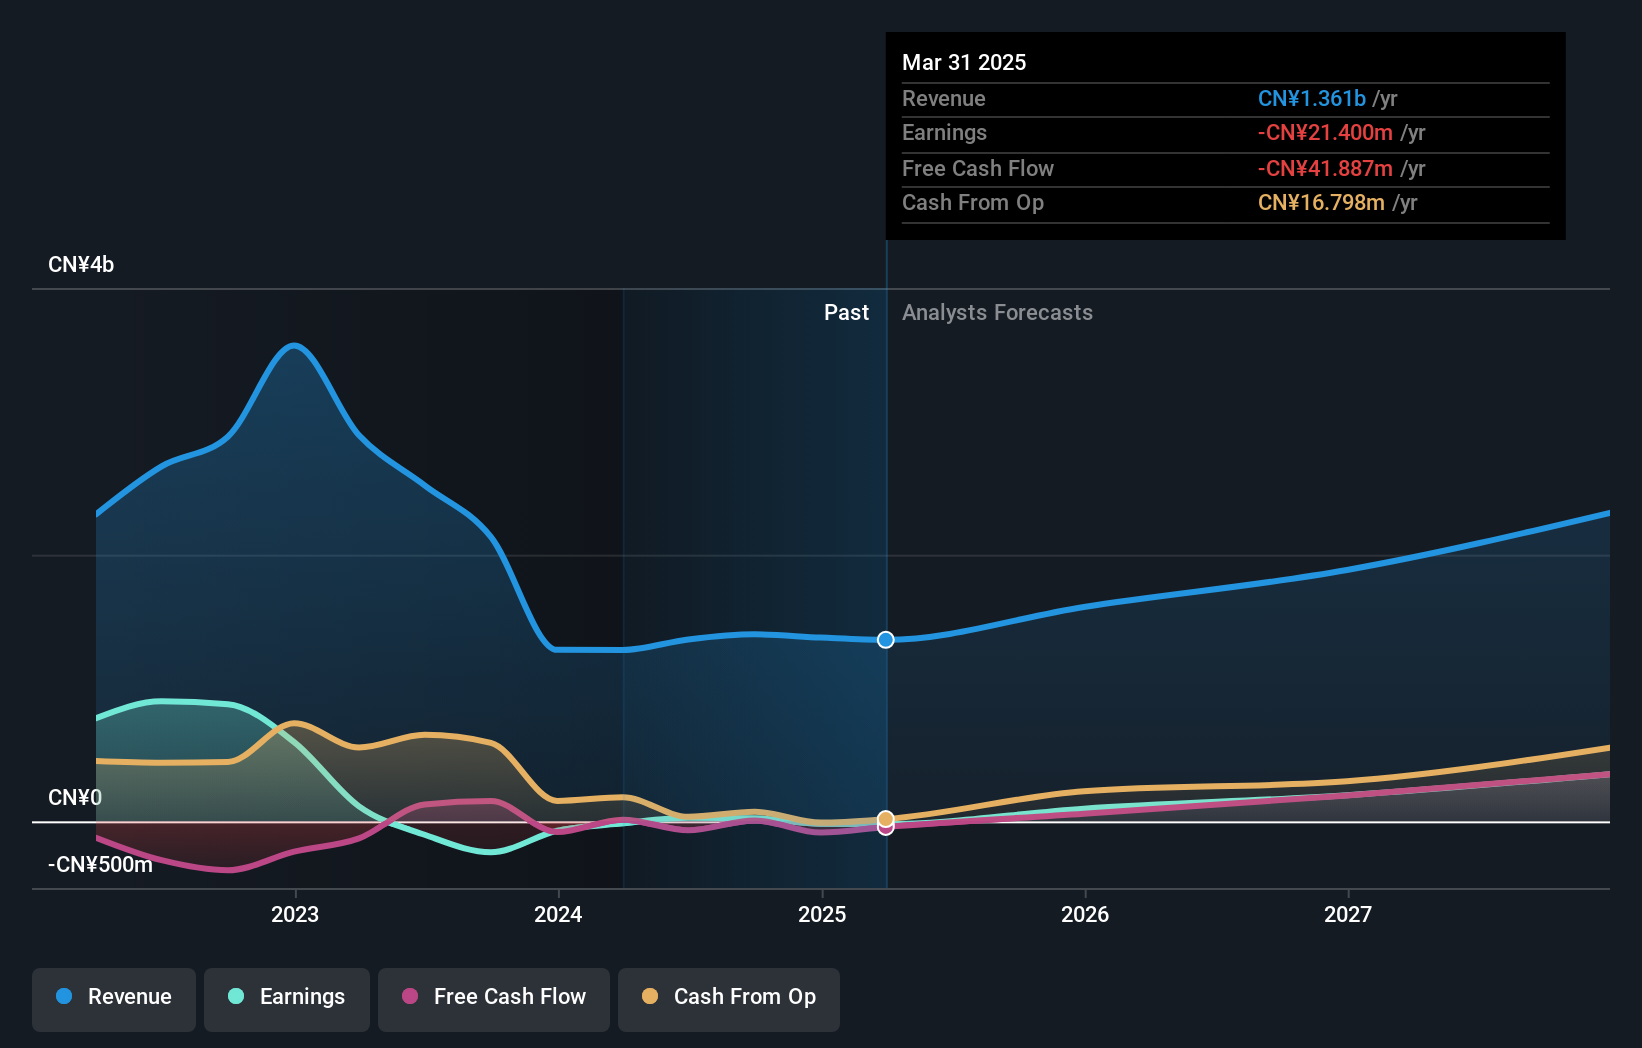
Nanjing Vazyme Biotech's earnings are projected to grow significantly at 69.9% annually, surpassing the Chinese market average. Despite a volatile share price and a low forecasted Return on Equity of 5.1%, the company has shown improved profitability with net income rising from CNY 6.62 million to CNY 24.22 million over nine months ending September 2026. Trading below fair value by 23.8%, its revenue growth is expected to outpace the market at 17.3% annually, although slower than desired for high-growth standards.
- Click here and access our complete growth analysis report to understand the dynamics of Nanjing Vazyme Biotech.
- Our valuation report here indicates Nanjing Vazyme Biotech may be overvalued.
Key Takeaways
- Unlock our comprehensive list of 542 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Ready For A Different Approach? AI is about to change healthcare. These 125 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com