
Can Kokuyo (TSE:7984) Justify Its Valuation After Stronger Nine Month Earnings?
Kokuyo earnings event and why it matters now
Kokuyo (TSE:7984) just posted nine month results to September 30, 2026, with sales of ¥290,174 million, net income of ¥18,068 million, and basic EPS of ¥42.62 from continuing operations.
Those figures compare with ¥265,650 million in sales, ¥16,723 million in profit, and EPS of ¥37.31 a year earlier. This gives investors fresh numbers to reassess how the stock’s current valuation lines up with recent performance.
Kokuyo’s latest nine month update lands after a softer patch in the share price, with the stock down 4.6% on a 90 day share price return, while the 3 year total shareholder return of 60.1% and 5 year total shareholder return of 128.7% still point to a much stronger longer run.
Scan Kokuyo’s latest figures against other potential opportunities by reviewing 16 high quality undervalued stocks with resilient balance sheets and solid cash generation profiles.
Kokuyo’s share price has eased over the past quarter while earnings have moved in the opposite direction. Is that a rational reset of expectations, or sentiment drifting away from the underlying progress? And what does the current valuation imply?
Preferred P/E multiple of 15.7x: Is it justified for Kokuyo?
The current discussion around Kokuyo keeps circling back to one thing. At a P/E of 15.7x, the share price near ¥868.1 reflects a lot of information about both its recent results and what investors are willing to pay for those earnings today.
P/E simply compares the market price of the stock to its earnings per share. For a business like Kokuyo, which earns money from office furniture, stationery and related services in Japan and overseas, this ratio gives you a quick sense of how much investors are paying for each unit of profit generated.
On one side, Kokuyo is described as good value when this 15.7x P/E is set against an estimated fair P/E of 17.2x. That suggests the current valuation sits below a level the market could move towards if earnings quality, projected growth and business mix remain consistent with the assumptions behind that fair ratio.
On the other side, the same 15.7x P/E screens as expensive when compared with the peer group on two fronts. It is higher than the peer average of 14.6x and also above the broader JP Commercial Services industry average of 13x, which implies investors are paying a premium relative to many similar businesses.
Explore the SWS fair ratio for Kokuyo.
Result: Price-to-earnings of 15.7x (ABOUT RIGHT)
Still, Kokuyo’s story could change quickly if office demand weakens or if competition in stationery and e-commerce squeezes pricing power and profitability.
Find out about the key risks to this Kokuyo narrative.
Another view on Kokuyo’s value
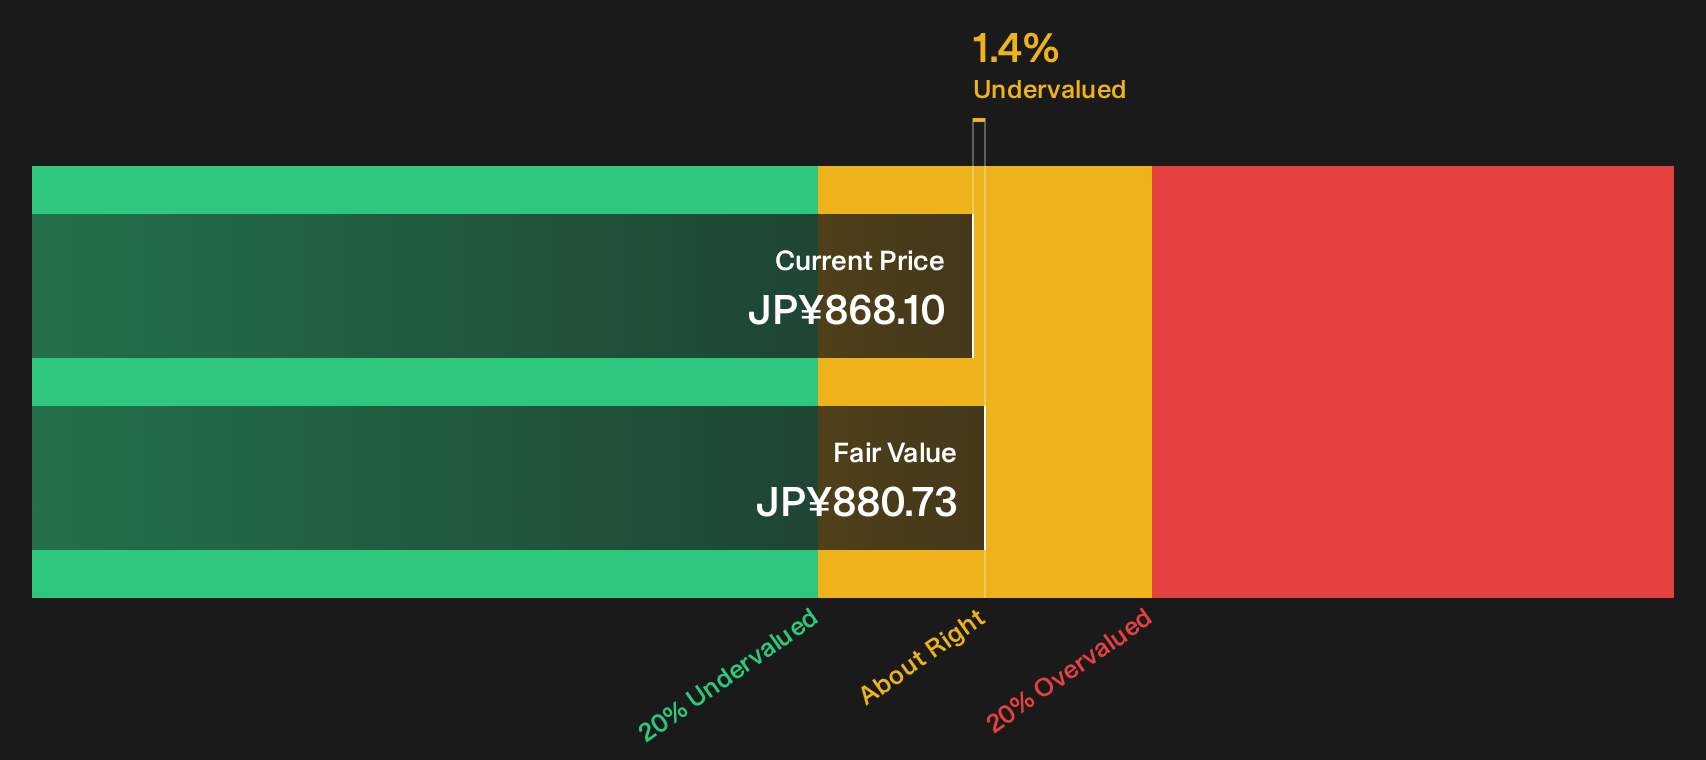
There is a different lens on Kokuyo that comes from the SWS DCF model. On that measure, the stock at ¥868.1 sits slightly below an estimated future cash flow value of ¥880.73, which points to only a modest gap between price and cash generation potential.
For investors, that small discount leaves less room for error if cash flows soften or if expectations shift materially. It raises a practical question: Is a narrow margin of safety enough to justify staying focused on Kokuyo over other ideas with a clearer valuation cushion?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kokuyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around Kokuyo feels mixed, with both issues to watch and positives that appeal to investors, use the data, not just the headline, to make your own call. Then weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Kokuyo?
If Kokuyo has your attention but you want a wider bench of ideas, use the Simply Wall Street Screener to compare other opportunities against the same clear data.
- Target dependable income streams by reviewing 28 dividend fortresses built around companies with higher yields and robust payout profiles.
- Surface resilient businesses by scanning the list of solid balance sheet and fundamentals (21 results) that combine financial strength with consistent fundamentals.
- Get ahead of the crowd by checking the 69 high quality undiscovered gems that pair solid quality indicators with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com