
S&T Bancorp (STBA) Could Be 5% Below Fair Value Following Dividend Rise And Q3 Growth
S&T Bancorp dividend move and earnings backdrop
S&T Bancorp (STBA) has approved a higher quarterly dividend of $0.38 per share, set against recent third quarter results that showed higher net interest income, higher net income, and lower net charge offs compared with the same period last year.
S&T Bancorp shares trade at $50.55 after a small pullback on the day. The 1-month share price return of 1.83% contrasts with a 90-day share price decline of 3.49%. Even so, total shareholder return of 42.63% over 1 year and 97.46% over 3 years points to strong long term momentum, which recent dividend and earnings news has helped to reinforce.
Scan other regional banks that show similar earnings and dividend momentum using our curated list of 29 resilient stocks with low risk scores alongside S&T Bancorp.
Bulls point to S&T Bancorp’s richer dividend and steady earnings, while bears focus on recent share price softness after big multi year gains. Which story does the current valuation lean toward as you weigh fresh results against the price tag?
Most Popular Narrative: 5% Undervalued
On Simply Wall St’s most followed narrative, S&T Bancorp screens as modestly undervalued, with an indicated fair value of about $53.33 against the recent $50.55 share price. That gap is tied directly to how funding strength, margins and capital returns are expected to interact over time.
The main thing that has to go right is that S&T Bancorp converts its expanded commercial teams and stronger funding mix into consistent C&I and CRE loan growth without eroding asset quality as it moves past the $10b Durbin threshold.
The expansion of commercial banking teams, with around 20% growth year to date and a target of 30% by year end focused on C&I and CRE in core markets, is intended to translate into stronger loan pipelines, higher line utilization and ultimately support revenue growth.
See why 3 investors see S&T Bancorp as 5% undervalued.
Result: Fair Value of $53.33 (UNDERVALUED)
Still, the narrative can crack if muted net interest income trends persist, or if further loan balance declines undercut the case for stronger earnings power.
Find out about the key risks to this S&T Bancorp narrative.
Another View: S&T Bancorp through the P/E lens
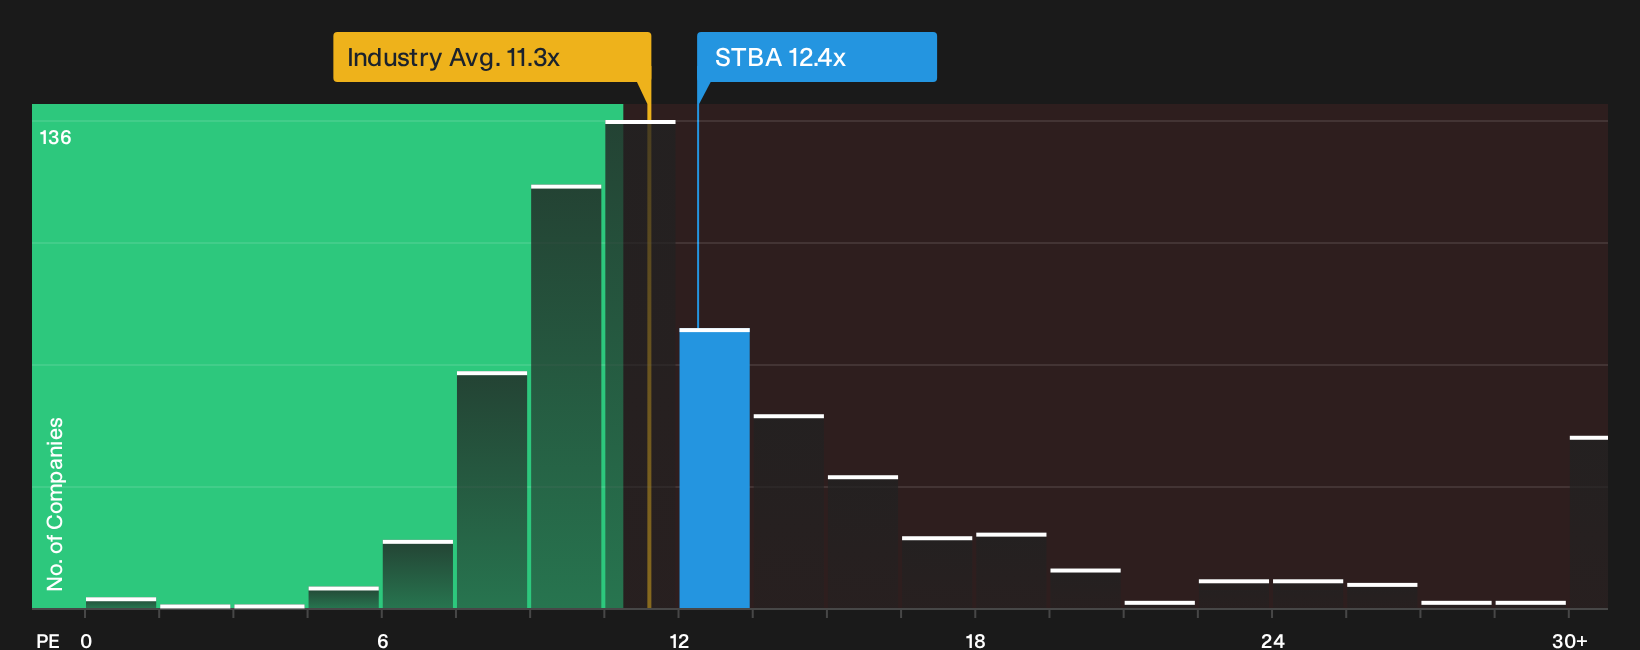
There is a very different story when S&T Bancorp is judged on its P/E ratio instead of cash flows. The shares trade at 12.4x earnings, above the US Banks industry at 11.3x and above a fair ratio of 10.4x, which points to valuation risk rather than a clear bargain.
That gap means investors are already paying a richer price for each dollar of profit, even though forecasts for earnings and revenue growth are modest. This leads to the question of whether S&T Bancorp has enough earnings quality and return potential to justify that premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution feels familiar, treat it as a prompt to act promptly, review the data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more S&T Bancorp sized ideas?
If S&T Bancorp is on your radar, do not stop here. Cast the net wider and pressure test your thinking against fresh options before the market moves.
- Target resilient opportunities that prize capital protection by reviewing a curated 29 resilient stocks with low risk scores tailored to steadier balance sheets and lower volatility profiles.
- Hunt for potential bargains with stronger fundamentals by scanning a focused 33 high quality undervalued stocks that filters for quality businesses at discounts to intrinsic worth.
- Build a cash flow focused playbook by comparing yields and payout strength through a purpose built 5 dividend fortresses aimed at reliable income streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com