
What Investors Got Wrong About United Parks & Resorts Before The Drop
If you had paused on United Parks & Resorts, in response to mixed analyst views in late 2025, and skipped the temptation to treat it as a straightforward recovery play, the next twelve months looked very different on paper. For United Parks & Resorts shareholders, the loss over the past year was 36.4%, including dividends. What early assumptions about Orlando resilience, weather risk, or concentrated ownership were available then for you to question before that decline unfolded?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind United Parks & Resorts. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
What United Parks & Resorts Investors Were Really Arguing About
The shares cost US$47.46 at the start of the period, and anyone looking at United Parks & Resorts then had to choose between two very different stories that both sounded reasonable.
The bullish Narrative pointed to a Fair Value of US$56.57, anchored in expectations of strong Orlando attendance, higher guest spending, and benefits from digital tools like the mobile app and CRM to lift per capita spend and margins.
The bearish Narrative set Fair Value at US$44, arguing that aging demographics, climate volatility, and pressure on admissions and in park spending could strain revenue growth and profit stability over time.
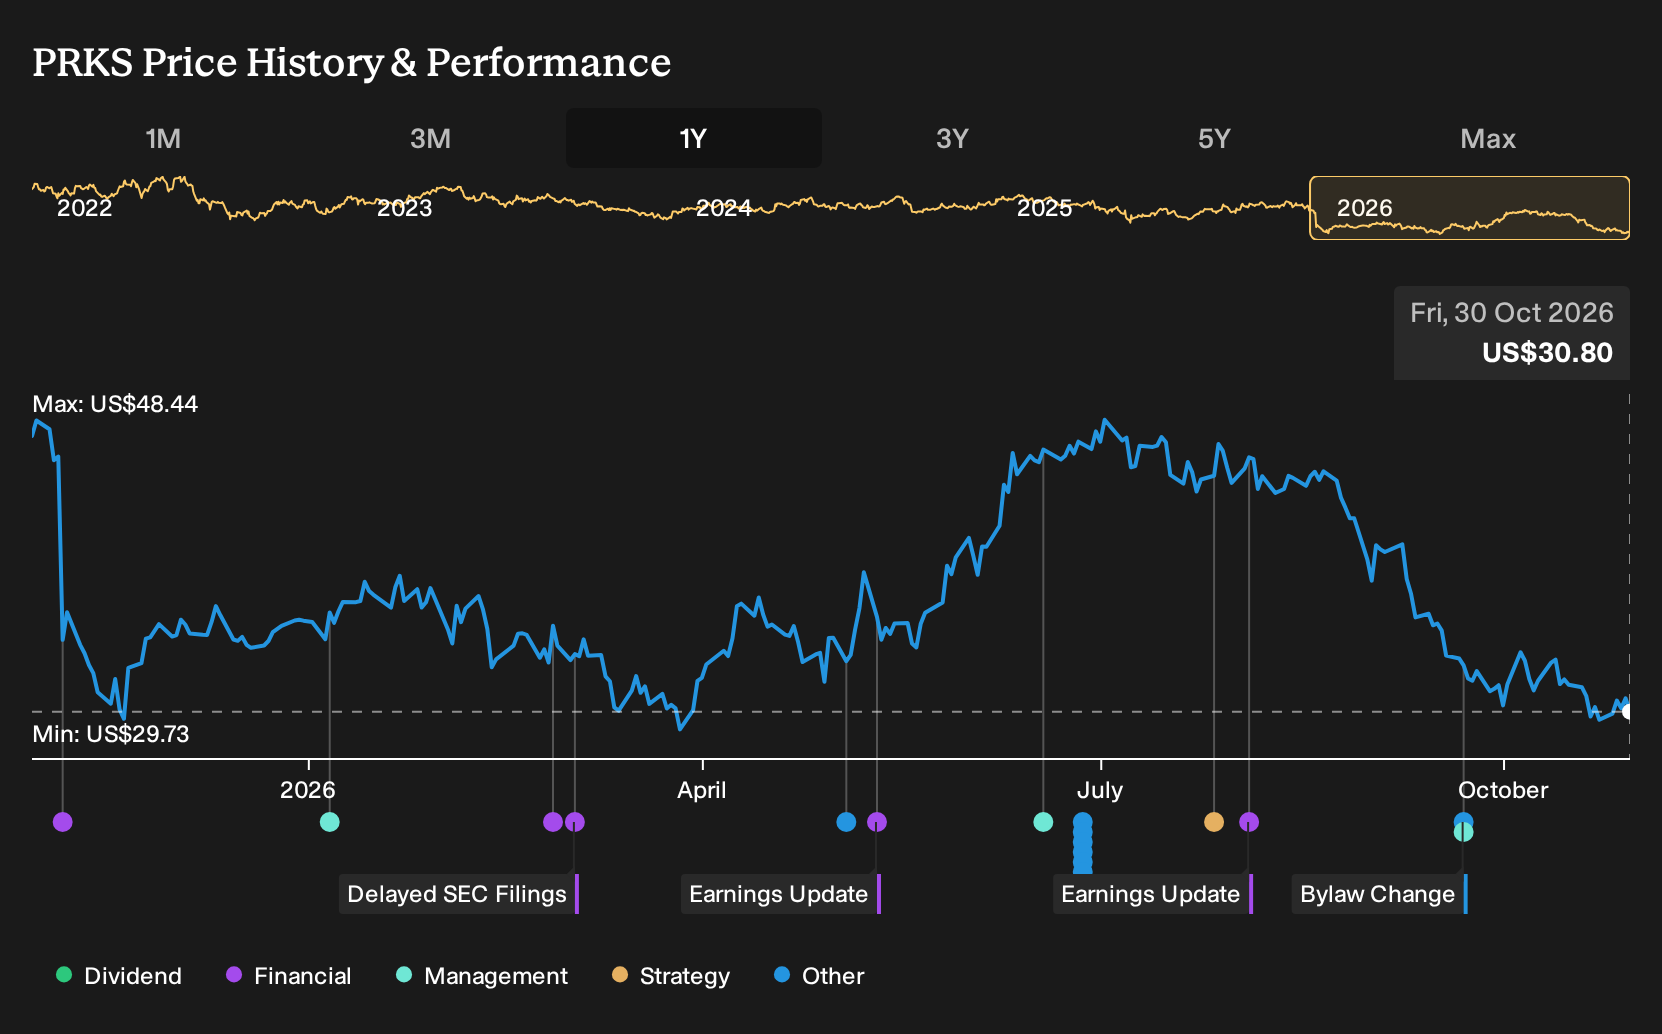
What The Evidence Did To The United Parks & Resorts Argument
United Parks & Resorts reported Q2 2026 revenue of US$483.3 million and net income of US$63.3 million, with net margin slipping from 16.3% to 13.1% versus Q2 2025, which challenged the bullish story built on expanding profitability. Record in-park spending and higher total revenue per capita partly supported that optimistic angle, so the period cut both ways.
The key lesson is simple. When a thesis leans on margin expansion, treat net margin as the primary checkpoint each results season and test it directly against the original claim, not the share price.
What The Fall In United Parks & Resorts Now Asks You To Believe
United Parks & Resorts trades at US$30.8, while the selected Narrative’s Fair Value sits above that level based on its own assumptions, not on hard fact.
The argument now leans on prepaid demand, in-park spending, and asset optionality. A buyer must judge whether sustained prepaid visits and higher guest spend can outweigh softer attendance and higher costs.
"Forward bookings and deferred revenue that reached $211.9 million by June 30, 2026, together with earlier commentary on strong group and pass sales, indicate that United Parks & Resorts continues to build a base of prepaid visits and ancillary products that can support future revenue recognition and earnings visibility."
One Narrative disagrees with today's price. → See where this Narrative says United Parks & Resorts should trade
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 35% below our estimate - converts shorter-cycle subsea projects into higher margin equipment and long term service relationships.
- Company 2 - 36% below our estimate - pushes an AI hardware and software stack customers rely on for intensive data processing.
- Company 3 - 41% below our estimate - tackles complex technical, safety and regulatory problems needing multidisciplinary science and engineering collaboration.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com