
Tractor Supply (TSCO), What Is Behind The Fresh Attention?
Tractor Supply (TSCO) just reported fresh third quarter results, showing higher sales but lower profit and earnings per share compared with last year. The company also reaffirmed its full year guidance, which helps anchor investor expectations.
Recent trading tells a mixed story. Tractor Supply’s share price has climbed 9.17% over the past month and 5.70% over the last quarter. However, the year-to-date share price return is down 33.23%, and the 1-year total shareholder return has declined 35.77%.
Scan how Tractor Supply’s latest guidance compares with rural and retail peers by running through the hand picked 33 high quality undervalued stocks that pair solid cash flows with sturdier balance sheets.
After a sharp year to date slide and a short burst of relief in recent weeks, Tractor Supply now sits at a level where the key tension is simple: Is most of the upside already used up, or is the rerating still early?
Most Popular Narrative: 6% Undervalued
On the most followed narrative, Tractor Supply screens as slightly below its assessed fair value of $36.30 versus the latest close at $33.94. That gap rests on the idea that some specific projects and category plays can steadily improve earnings power over time.
The growing pet ecosystem that now links assortment resets, over 200 new pet products, Freshpet coolers, subscriptions projected above US$200 million in 2026, and the acquisition of VIP Petcare with access to about 1 million pets annually may support steadier pet category revenue and earnings contribution.
See why 45 investors see Tractor Supply as 6% undervalued.
Result: Fair Value of $36.30 (UNDERVALUED)
Still, the narrative can wobble if comparable sales keep weakening, or if freight and fuel costs rise once tariff refunds and vendor support taper off.
Find out about the key risks to this Tractor Supply narrative.
Another View: Tractor Supply Through The P/E Lens
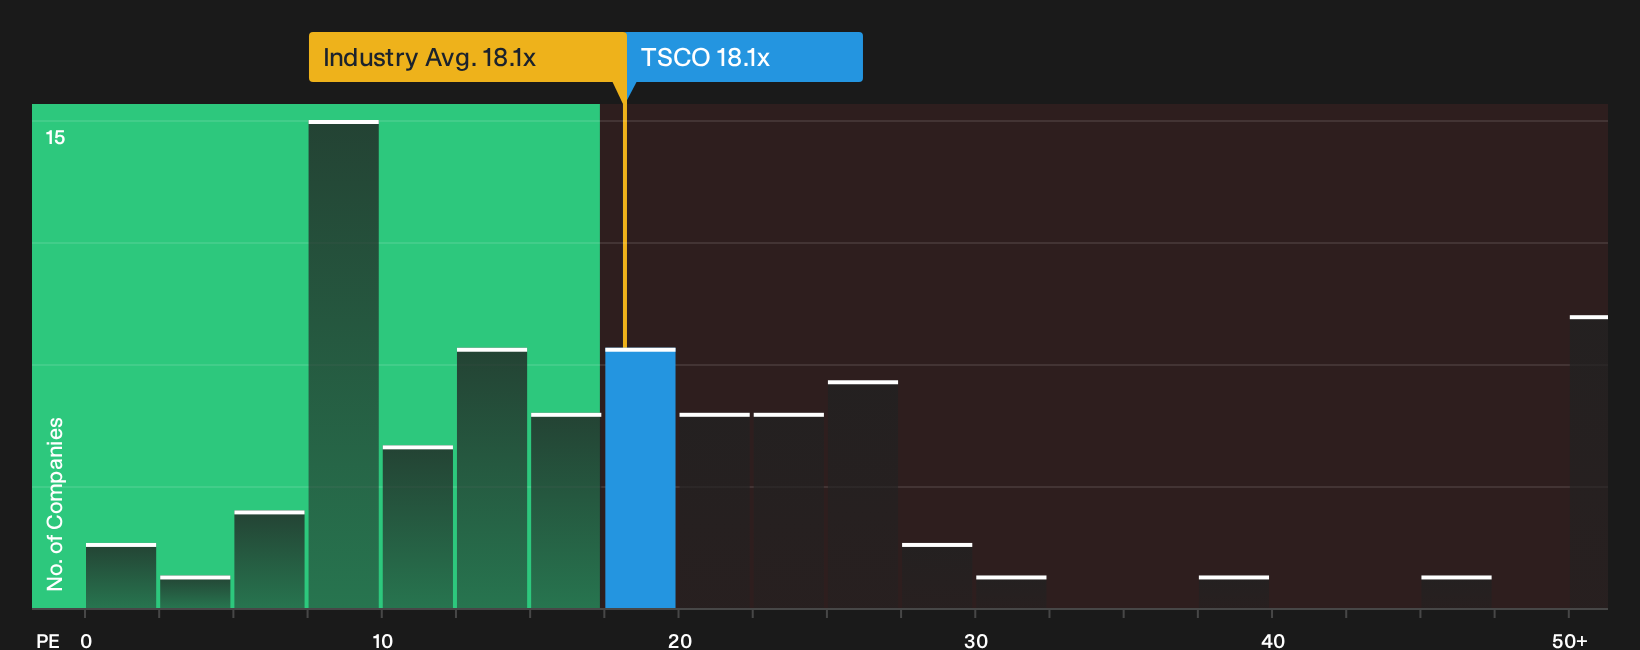
The SWS DCF model suggests Tractor Supply trades about 2.2% below estimated fair value, which lines up with the 6% undervalued narrative. The P/E ratio tells a more cautious story. At 18.1x against a fair ratio of 15.8x, the stock screens rich on this metric despite looking cheap versus peers at 22.6x. This may indicate a limited safety margin if earnings disappoint.
To see how the numbers compare using this approach, walk through the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Tractor Supply so far. If you want a clear view before the crowd reacts again, weigh the upside and downside in the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Tractor Supply?
Do not stop with a single ticker. The strongest portfolios usually come from comparing a few focused ideas side by side before making a move.
- Target overlooked growth potential by scanning the 19 high quality undiscovered gems that pair solid fundamentals with under-the-radar stories the crowd has not chased yet.
- Lock in more resilient candidates by running through a list of solid balance sheet and fundamentals (24 results) that filters for sturdier finances and healthier fundamentals when conditions get rough.
- Pressure test your value thesis against a 29 resilient stocks with low risk scores that narrows in on companies with lower overall risk scores and more durable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com