
Hershey (HSY) Could Be 109% Above Fair Value After Raised 2026 Outlook
Hershey (HSY) moved back into focus after its third quarter 2026 report. The company reported higher profit, raised its full-year earnings outlook, and management highlighted a heavier 2027 product pipeline.
At a share price of US$165.61, Hershey has seen a 1-day share price return of 3.33% surrounding the earnings release, although the 90-day share price return is down 6.79% and the year to date share price return is down 9.21%. In that context, the 1-year total shareholder return is roughly flat at 0.57%. Recent profit strength and guidance upgrades appear to be rebuilding momentum after a weaker period, but not yet enough to materially change the longer multi year total shareholder return profile.
Scan how Hershey's earnings story compares with other consumer staples by zeroing in on our hand picked 33 high quality undervalued stocks, which pair solid fundamentals with compressed valuations.
The rebound in Hershey after this earnings jolt sets up a simple question for you as a buyer: Does the current price still offer an attractive trade off between risk and reward, or has the easy upside already been taken?
Most Popular Narrative: 109% Overvalued
Hershey last closed at $165.61 while the leading narrative fair value sits at $79.25, which frames the current share price as rich relative to that estimate and turns the question from near term momentum to long term payoff.
A fortress brand and scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact.
See why 6 investors see Hershey as 109% overvalued.
Result: Fair Value of $79.25 (OVERVALUED)
Still, that fortress narrative can crack if cocoa costs stay elevated far longer than expected, or if GLP-1 appetite suppression drags category demand lower.
Find out about the key risks to this Hershey narrative.
Another View On Hershey's Valuation
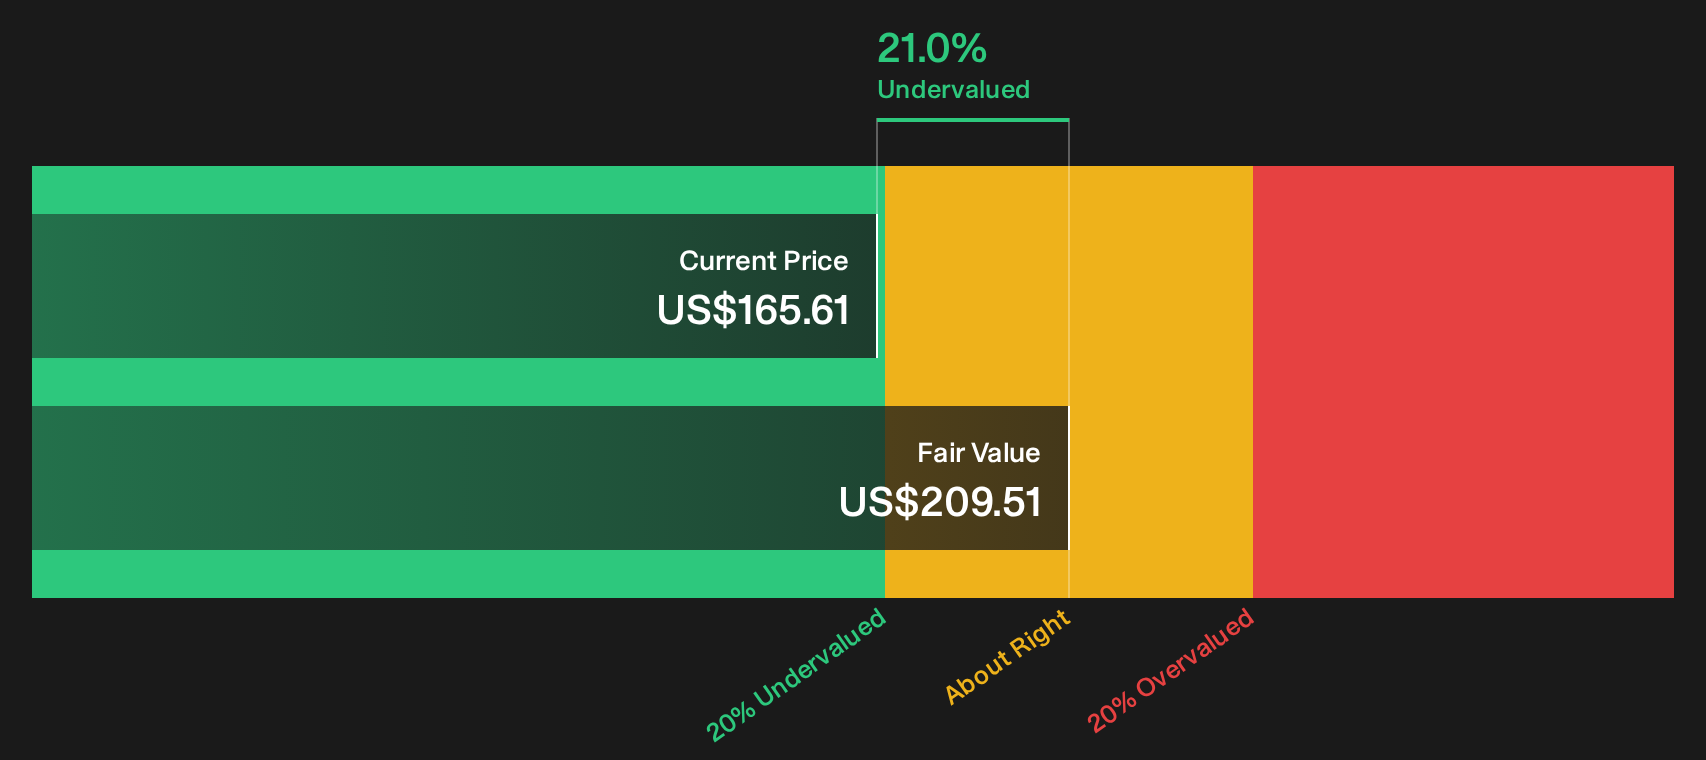
The user narrative pins Hershey at a fair value of $79.25 and calls the stock 109% overvalued. Our SWS DCF model points a different way. It estimates the future cash flow value at $209.51, which frames the current $165.61 price as discounted instead of stretched. Which lens do you trust more for a long holding period?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Hershey so far. If you want to move quickly and build your own conviction, go straight to the 4 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond Hershey?
If Hershey has your attention, do not stop here. A broader watchlist can sharpen your judgement and help you spot opportunities others ignore.
- Zero in on potential mispricings by scanning a curated pool of solid fundamentals with compressed valuations through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on companies with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Target income focused opportunities by reviewing a focused set of resilient payers in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com