
Earnings Guidance Might Change The Case For Investing In Old National Bancorp Stock
- Old National Bancorp reported third quarter 2026 net interest income of US$584.29 million and net income of US$253.99 million, with diluted EPS from continuing operations of US$0.66, and issued guidance for 2026 EPS growth exceeding 15%.
- The bank paired higher year to date profitability with US$222.91 million of share repurchases through September 2026. This reduced the share count and concentrated earnings across fewer shares, even as net charge offs for the quarter rose to US$34.09 million.
- We will now look at how Old National Bancorp's investment narrative is shaped by this strong EPS guidance and capital return.
Old National Bancorp Investment Narrative Recap
To own Old National Bancorp, you need to be comfortable with a straightforward banking story. The business leans on commercial lending, fee income and a relatively low net interest margin of about 3.5% that depends on solid loan production. The guidance for EPS growth above 15% in 2026 speaks directly to that engine and reinforces the near term earnings focus.
The sharper risk right now sits in credit quality and competition. Net charge offs of US$34.09 million show credit costs are active, and heavier pricing pressure in commercial real estate or broader lending could squeeze that 3.5% margin. If loan growth or pricing softens, the EPS trajectory and guidance could become harder to support.
The most relevant disclosure for this story is the 2026 EPS growth guidance above 15%. It anchors the current earnings narrative around middle market commercial production, fee income expansion and the repricing of roughly US$8b of fixed rate loans and securities at higher yields, which are all cited as key drivers for higher net interest income and a healthier margin.
This outlook sits beside a capital return program that has already retired 9,072,131 shares for US$222.91 million. That buyback, funded while maintaining a CET1 ratio just over 11% and ongoing dividends, increases the sensitivity of per share results to any swings in revenue growth or credit costs. This turns execution on loan pipelines and risk management into central catalysts for Old National Bancorp.
Old National Bancorp's narrative projects US$3.4b revenue and US$1.2b earnings by 2029. This implies 8.3% yearly revenue growth and an earnings increase of about US$329.9m from US$870.1m today.
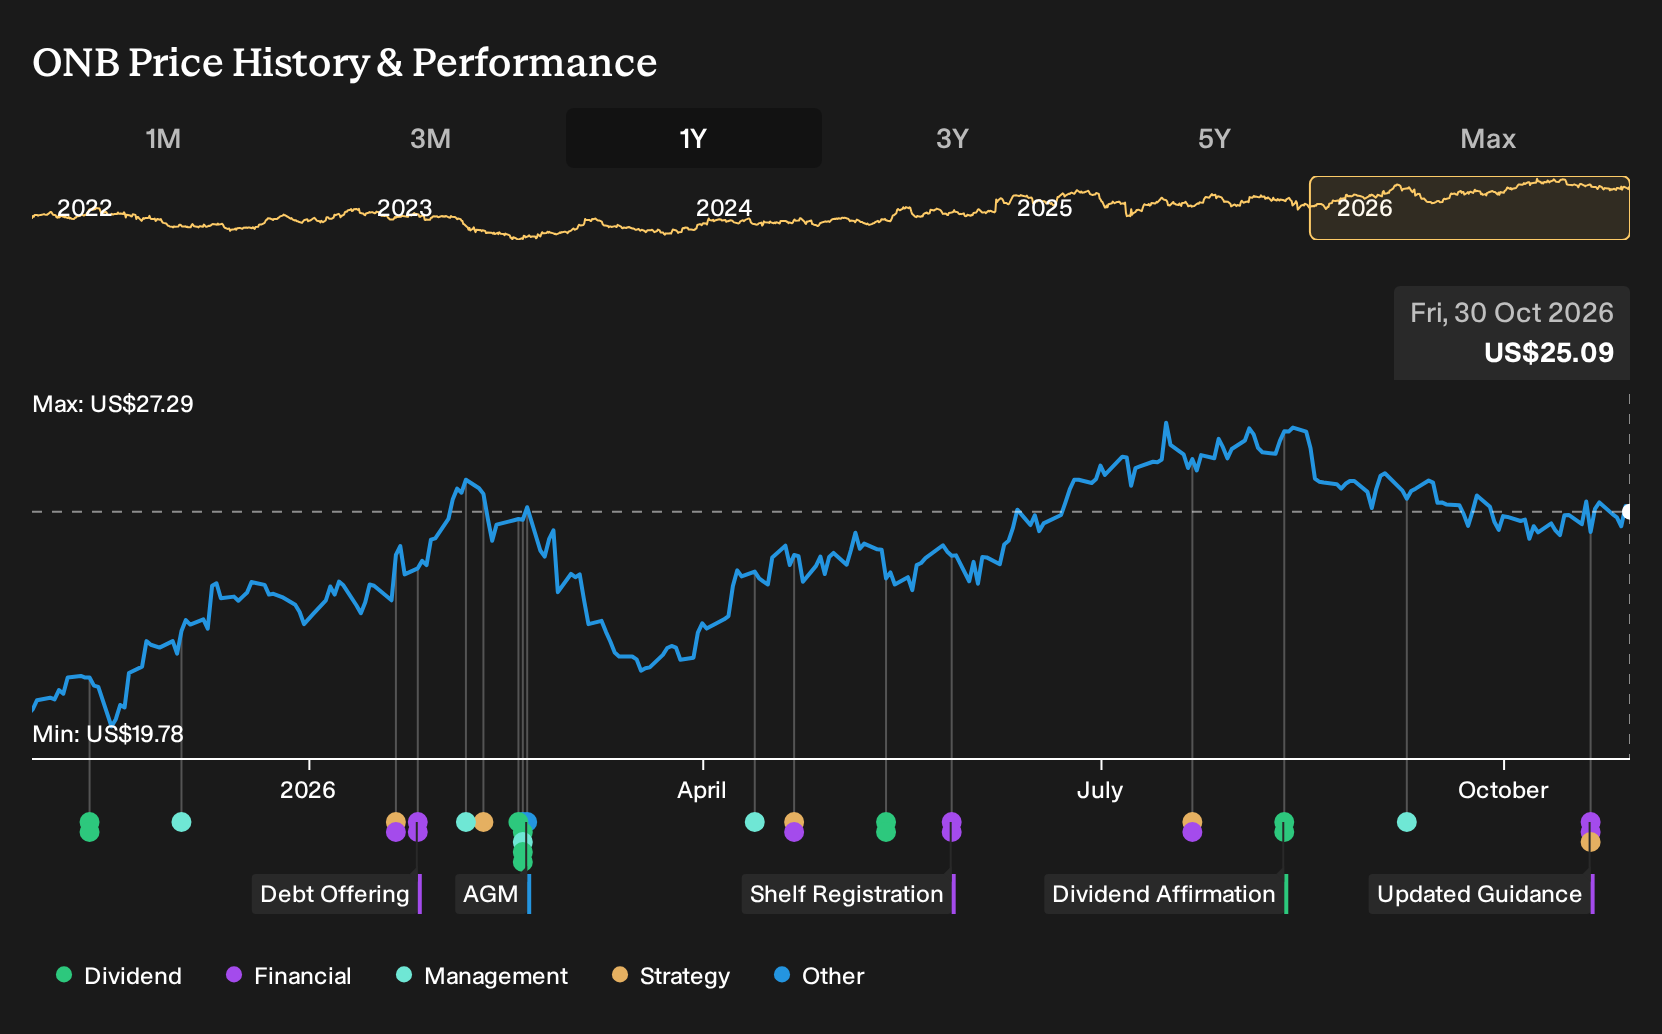
Uncover why Old National Bancorp's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Old National Bancorp from the Simply Wall St Community stretch from US$29.30 to about US$51.84 across 2 separate models, so you are seeing very different expectations from retail forecasters. When these are considered alongside rising net charge offs and a heavy capital return program, there is meaningful debate over how robust future profitability really is. Investor opinions can differ widely, so it is worth exploring several alternative viewpoints before forming a view on Old National Bancorp.
Explore another Old National Bancorp fair value estimate, including one that suggests as much as 107% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Old National Bancorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Old National Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old National Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Old National Bancorp?
Old National Bancorp may set the tone for your financial watchlist, but you can broaden that opportunity set by scanning other companies with solid fundamentals and different risk profiles using the Simply Wall St screener.
- If you want income to play a bigger role in your plan, you can start with higher yielding businesses that have paid out consistently by reviewing 5 dividend fortresses.
- If capital preservation matters most, you can focus on companies where financial strength is front and center by filtering for a list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced opportunities with quality metrics to back them up, you can cast the net wider with a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com