
Westinghouse Air Brake Technologies (WAB) After Strong Q3 Results Is The Undervalued Narrative Intact
How the latest earnings event reshaped the Westinghouse Air Brake Technologies story
Westinghouse Air Brake Technologies (WAB) just put fresh numbers on the table with third quarter results, updated full year revenue guidance, and a new shelf registration that expands its future financing options.
For the quarter ended September 30, 2026, the rail equipment specialist reported revenue of US$3,120 million compared with US$2,886 million a year earlier. Net income for the same period was US$409 million compared with US$310 million in the prior year quarter, with basic earnings per share from continuing operations at US$2.43 versus US$1.81.
On a diluted basis, earnings from continuing operations were US$2.42 per share, compared with US$1.81 in the same period last year. Over the first nine months of 2026, revenue came in at US$9,249 million compared with US$8,202 million a year ago, while net income was US$1,166 million compared with US$968 million.
Nine month basic earnings per share from continuing operations were US$6.88 versus US$5.66, and diluted earnings per share were US$6.86 compared with US$5.64. These figures give investors fresh reference points for how the Freight and Transit focused business is performing ahead of the year end.
Against that earnings backdrop, Westinghouse Air Brake Technologies shares closed at US$279.60, with the stock easing 2.1% on the day yet still delivering a 29.3% year to date share price return and a 3 year total shareholder return of about 1.6x. This points to momentum that has cooled in recent months but remains strong over longer horizons.
Spot 42 power grid technology and infrastructure stocks that, like Westinghouse Air Brake Technologies, are tied to rail and infrastructure demand and may be setting up their next move after earnings.That mix of strong reported figures and a cooler share price invites a tougher question. Are investors reassessing Westinghouse Air Brake Technologies fundamentals, or has sentiment simply moved ahead of what the current valuation can justify?
Most Popular Narrative: 15% Undervalued
On the narrative view, Westinghouse Air Brake Technologies carries a fair value of about $329.58 versus the latest close at $279.60. This puts the spotlight on what is supposed to drive that gap, namely backlog, higher margin offerings, and acquisitions feeding into future earnings.
Sustained global investment in rail infrastructure and modernization across freight and transit, including large international awards in regions such as Australia and Latin America, is feeding into Westinghouse Air Brake Technologies’ multiyear backlog above US$30b and could support more stable revenue and earnings over several years.
See why 23 investors see Westinghouse Air Brake Technologies as 15% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, insider selling around a roughly 37x P/E and management flagging tariffs as a major headwind both sit uncomfortably beside the bullish Westinghouse Air Brake Technologies narrative.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: What Westinghouse Air Brake Technologies’ P/E Is Telling You
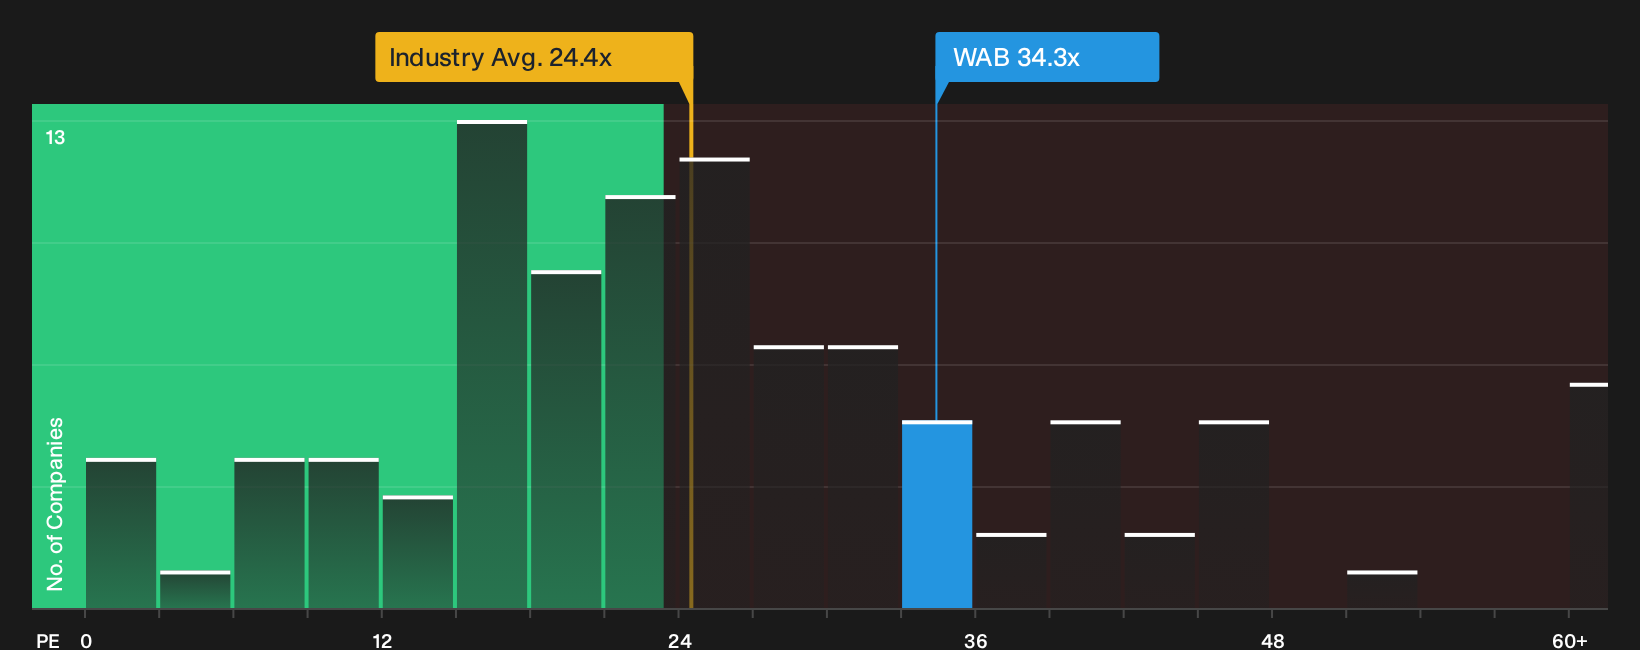
There is a very different message in the simple P/E check. Westinghouse Air Brake Technologies trades on roughly 34.3x earnings, compared with a peer average of 19.7x and a fair ratio estimate of 32x. That gap points to a richer price tag and leaves less room for error if expectations slip.
For investors weighing which signal to trust, it helps to see how that earnings multiple stacks up in detail and what would need to change for the P/E to drift closer to the fair ratio or the wider Machinery group. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data, or simply a reset after a strong run. Move quickly, review the details, and weigh up the 3 key rewards and 2 important warning signs.
Looking for more Westinghouse Air Brake Technologies sized ideas?
If Westinghouse Air Brake Technologies is on the watchlist, it makes sense to widen the lens and line up a few comparable opportunities before the next round of earnings hits.
- Target resilient growth by scanning a 33 high quality undervalued stocks that blend quality, cash generation, and pricing that still leaves room for upside.
- Strengthen income potential by reviewing a 5 dividend fortresses focused on companies combining higher yields with balance sheets that can support ongoing payouts.
- Protect the downside by filtering a 29 resilient stocks with low risk scores designed to surface businesses with steadier fundamentals and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com