
Is Softer Full Year Loss Guidance Altering The Investment Case For Boston Beer (SAM)?
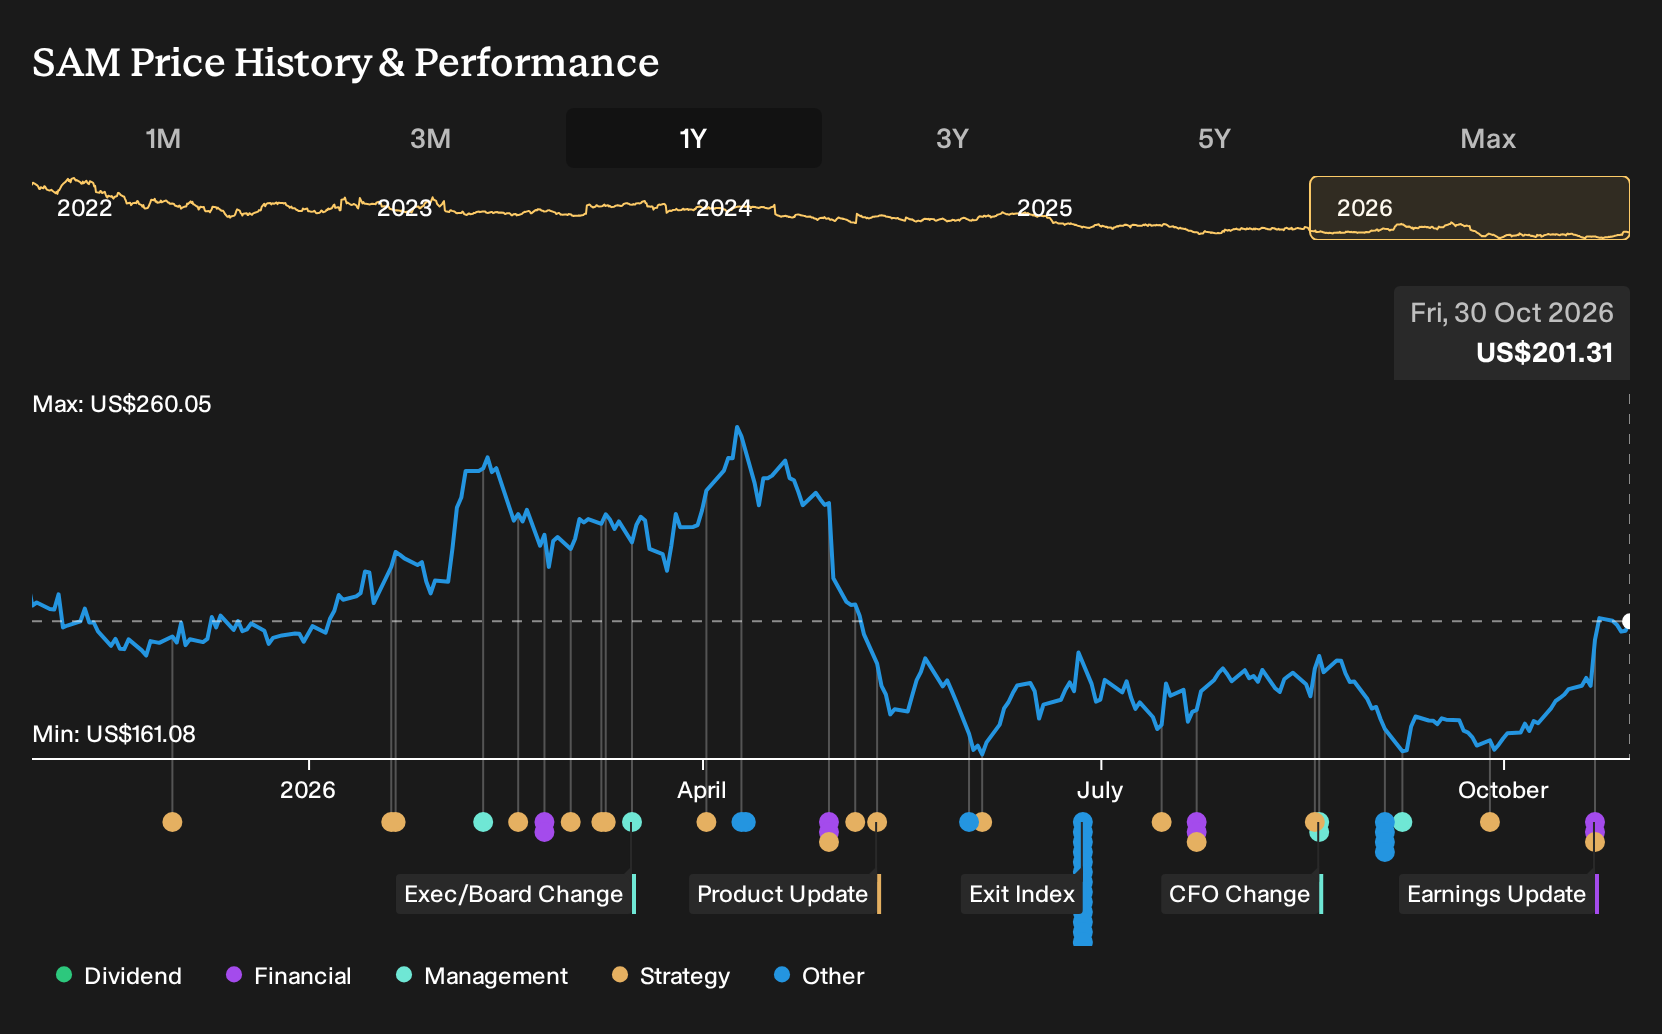
- Boston Beer Company reported third quarter 2026 sales of US$555.46 million and revenue of US$520.1 million, with net income of US$43.17 million and diluted earnings per share from continuing operations of US$4.21, alongside higher brewery asset impairment charges of US$2.89 million.
- Across the first nine months of 2026, Boston Beer Company moved from prior year profitability to a net loss of US$50.53 million. Management narrowed its expected full year GAAP loss per share range, reflecting a modestly more favorable internal assessment despite ongoing operational and cost pressures.
- The next section examines how Boston Beer Company's widened nine month loss but slightly improved full year guidance could influence its overall investment narrative.
Boston Beer Company Investment Narrative Recap
To own Boston Beer Company, you need to be comfortable with a business that is trying to fix profitability while its categories keep shifting. The big belief is that portfolio mix, productivity gains and more disciplined marketing can matter more than flattish volumes. The latest quarter kept that story intact, with solid quarterly profit sitting beside a much weaker year to date.
The key short term catalyst remains proof that higher margin offerings and cost work can pull full year results back toward breakeven. The widened nine month loss and brewery impairments underline the biggest risk right now. Execution missteps in Beyond Beer brands or further cost creep could leave margins under pressure for longer.
The updated 2026 GAAP loss per share guidance is the clearest new datapoint for that thesis. Management now expects a loss of US$5.76 to US$4.26 per share, compared with the prior range of US$6.23 to US$4.23. That is a modestly tighter outlook, not a transformation of the story.
For you as an investor, that slightly improved range points to some confidence in cost control and mix, even as year to date performance shows how fragile earnings still are. The risk is that category headwinds, brand fragmentation and the aluminum can dispute limit how quickly any operational progress can show up in cleaner, more consistent profit.
Boston Beer Company Consensus Assumptions
Analysts outline a Boston Beer Company outlook that emphasizes margin repair rather than rapid top line expansion. Revenue is assumed to stay roughly flat over the next three years, while profit margins are projected to move from a current loss position of 3.7% to a positive 5.6% in 2029. Consensus forecasts point to earnings of US$108.7 million, or US$11.64 per share, by that year, compared with a loss of US$70.4 million today. That change in profit is based on a mix of higher margin products, tighter cost control and a shrinking share count, with expectations that outstanding shares fall about 3.34% each year for the next three years.
Valuation assumptions build on that earnings bridge. For the analyst targets to hold, investors would need to accept Boston Beer Company trading on a P/E of 20.5x those 2029 earnings, which sits below the current 25.7x multiple referenced for the wider US beverage peer group. That framework also assumes a discount rate of about 7.2% to 7.24% when bringing those future cash flows back into today’s terms. None of this is based on aggressive revenue acceleration. It focuses instead on the income statement moving from red to black and then stabilising.
Boston Beer Company's narrative projects US$1.9b revenue and US$108.7 million earnings by 2029, which implies flat yearly revenue and an earnings increase of about US$179 million from a loss of US$70.4 million today.
Uncover why Boston Beer Company's fair value indicates that it is in line with its current price.
Exploring Other Perspectives
Some of the most optimistic Boston Beer Company analysts lean hard into the Sun Cruiser and RTD spirits catalyst. Before this earnings release, they were penciling in revenue of about US$2.0b and earnings of roughly US$153.2 million by 2029. Those bullish stories may evolve as this new quarter is absorbed.
Explore 2 other Boston Beer Company fair value estimates, including one that suggests as much as 53% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boston Beer Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Boston Beer Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Beer Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boston Beer Company?
If Boston Beer Company has sharpened your focus on risk, return and balance sheet strength, it can be useful to cast a wider net across other listed businesses that fit your preferred profile.
- For investors who prefer strong fundamentals at a reasonable entry point, scan through our 33 high quality undervalued stocks that combine quality with compressed valuations.
- If stability and capital preservation sit high on your checklist, sort companies by resilience using the 29 resilient stocks with low risk scores and focus on those with more defensive characteristics.
- When you want a mix of financial robustness and earnings support, widen your research universe with a curated 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com