
Tyler Technologies Stock Gains Focus After Earnings Beat And AI Progress
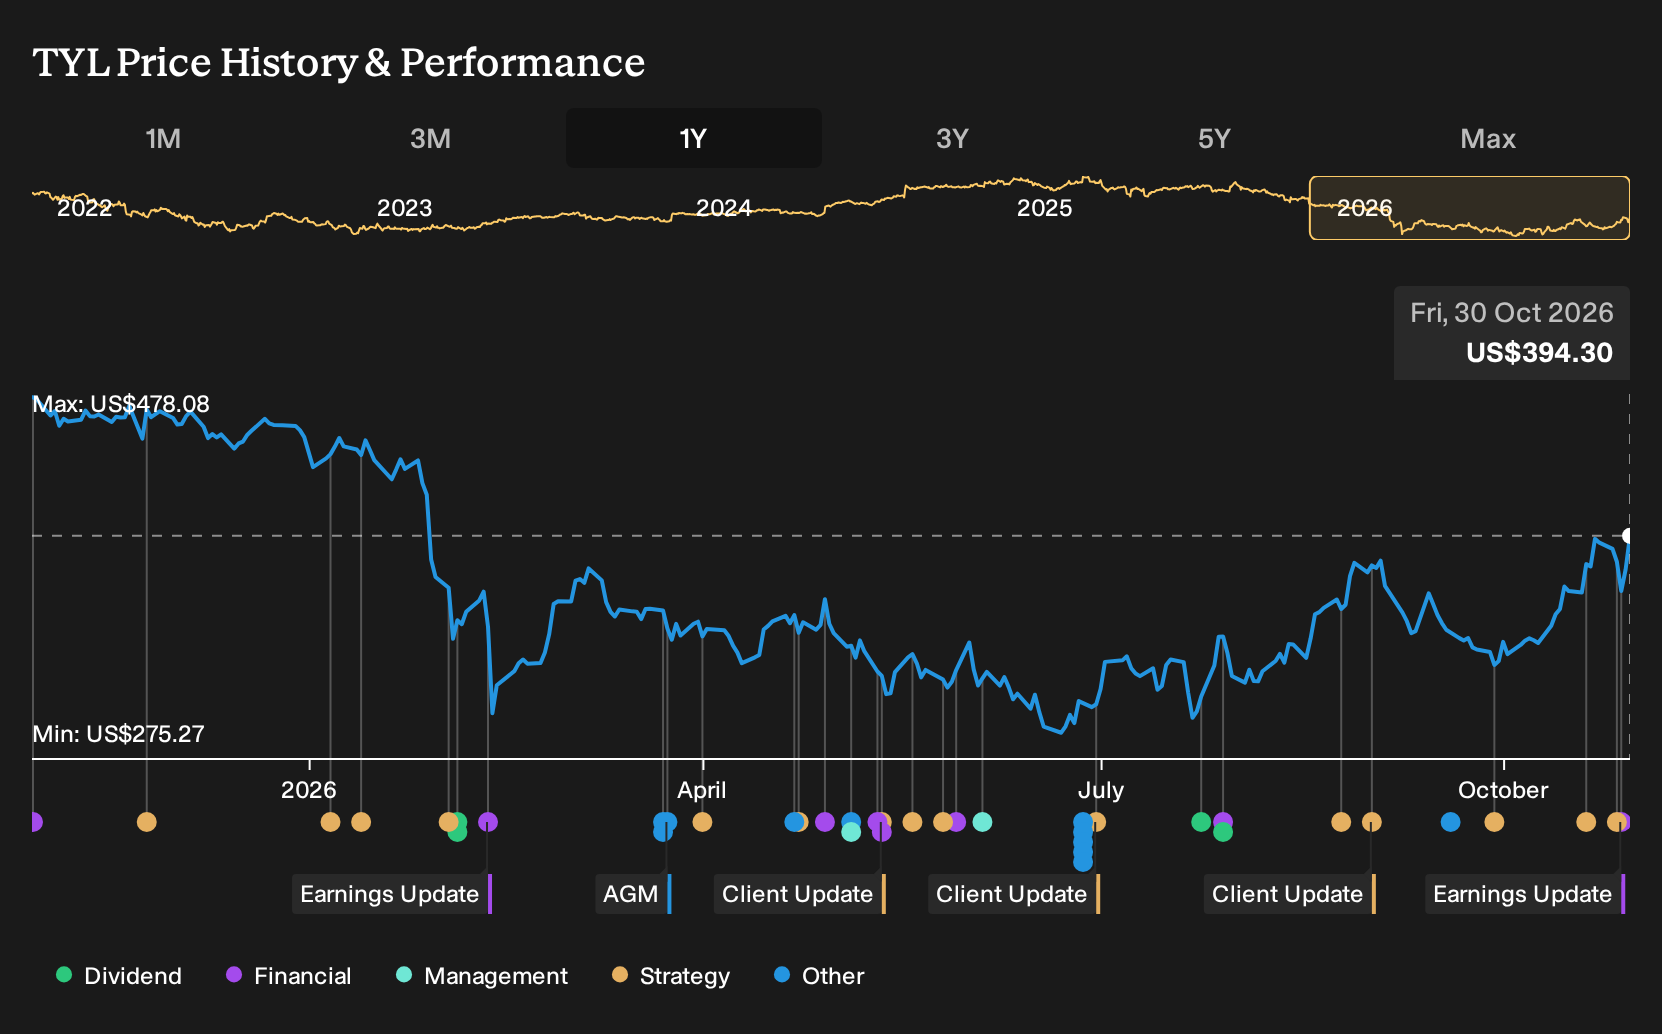
- Tyler Technologies reported third quarter 2026 revenue of US$647.57 million and net income of US$95.07 million, alongside record free cash flow, expanded operating margins, and continued growth in recurring and SaaS-based earnings.
- Recent client wins for Tyler’s AI-powered budgeting tools and Resident AI Assistant, combined with a completed US$379.01 million buyback of 1,148,389 shares, highlight how AI adoption and capital returns are shaping the company’s operating profile.
- The next area of focus is how Tyler Technologies’ strong quarterly results and expanding AI usage could influence the broader investment narrative.
Tyler Technologies Investment Narrative Recap
To hold Tyler Technologies, you need to believe its push into SaaS, AI agents and payments can translate current revenue and earnings momentum into steadier recurring economics and better operating efficiency. The latest quarter, with higher revenue, earnings per share and record free cash flow, supports that operating thesis rather than redefining it.
The most important short term catalyst is execution on cloud migration and AI commercialization without letting subscription growth slow meaningfully again. The key risk is that timing issues around implementations, conversions and margin uplift persist, which could keep reported growth choppy and leave investors questioning how much operating leverage is really emerging.
The Fairfax County launch of Ask Fairfax, built on Tyler’s Resident AI Assistant, is the clearest operational proof point for the current AI story. It shows Tyler Technologies embedding purpose built generative tools directly into government workflows, answering more than 40,000 resident questions from official data while keeping only anonymized metrics.
For you as a shareholder, that kind of deployment matters because the main catalysts are AI driven upsells, higher SaaS tiers and productivity gains. The execution test now is whether real world wins like Fairfax and the roughly 300 AI enabled deals mentioned by management translate into sustained recurring usage while avoiding new operational or privacy risks.
Tyler Technologies Consensus Forecasts in Context
Tyler Technologies' narrative projects US$3.2b revenue and US$533.9 million earnings by 2029. This is based on 9.0% yearly revenue growth and an earnings increase of about US$198.6 million from US$335.3 million today.
Uncover how Tyler Technologies' fair value indicates an 11% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view focuses on slower AI monetization. The most cautious Tyler Technologies analysts were modeling revenue at about US$3.2b and earnings near US$513.4 million by 2029, even before this quarter’s US$647.57 million revenue print. That more muted earnings path shows how far opinions can diverge. It is therefore worth exploring several viewpoints before deciding what this latest update might change.
Explore 6 other Tyler Technologies fair value estimates, including one that suggests as much as 56% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tyler Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tyler Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Tyler Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Tyler Technologies?
Once you have an opinion on Tyler Technologies, the next step is to widen your opportunity set and see how it compares with other businesses that match your risk, income, and quality preferences.
- If capital preservation is your priority, you could start with companies that pair resilience with measured growth by checking out 29 resilient stocks with low risk scores.
- For investors focused on finding potentially mispriced quality, our filters can help surface companies that mix strong fundamentals with appealing valuations through the 19 high quality undiscovered gems.
- If you care most about sturdy finances and cleaner balance sheets, you may want to focus your search using a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com