
Southside Bancshares (SBSI) Posted Stronger Third Quarter Earnings, Is It Still Undervalued?
Southside Bancshares (SBSI) just posted third quarter 2026 results that show higher net income and earnings per share, driven by net interest income and stronger loan and securities yields.
Southside Bancshares shares trade at US$33.66, with a 1-month share price return of 9.53% and a year to date share price gain of 10.54%. The 1-year total shareholder return of 25.41% points to building momentum, despite a slightly softer 5-year total shareholder return of a 4.26% decline.
Compare Southside Bancshares' earnings momentum and funding pressures with a curated list of regional banks that pair income growth with balance sheet resilience using the list of solid balance sheet and fundamentals (24 results).
The price has already moved on Southside Bancshares earnings step up, so the key question now is whether to pay the current price today or wait for a potentially lower entry as valuation stretches or compresses from here.
Most Popular Narrative: 100% Undervalued
Southside Bancshares closed at $33.66 versus a widely followed fair value estimate of $34. This frames the stock as modestly below that reference level while analysts focus on how balance sheet actions and Texas expansion shape the risk return trade off.
Previously, balance sheet positioning and capital deployment were not central. Now, Southside Bancshares is framed around active securities portfolio restructuring and subordinated debt redemption, with the impact on net interest income and earnings a key focus.
See why 7 investors see Southside Bancshares as 1% undervalued.
Result: Fair Value of $34 (UNDERVALUED)
Still, Southside Bancshares’ story can unravel if funding costs stay elevated, or if further deposit volatility limits balance sheet growth and earnings power.
Find out about the key risks to this Southside Bancshares narrative.
Another View: Southside Bancshares Through The P/E Lens
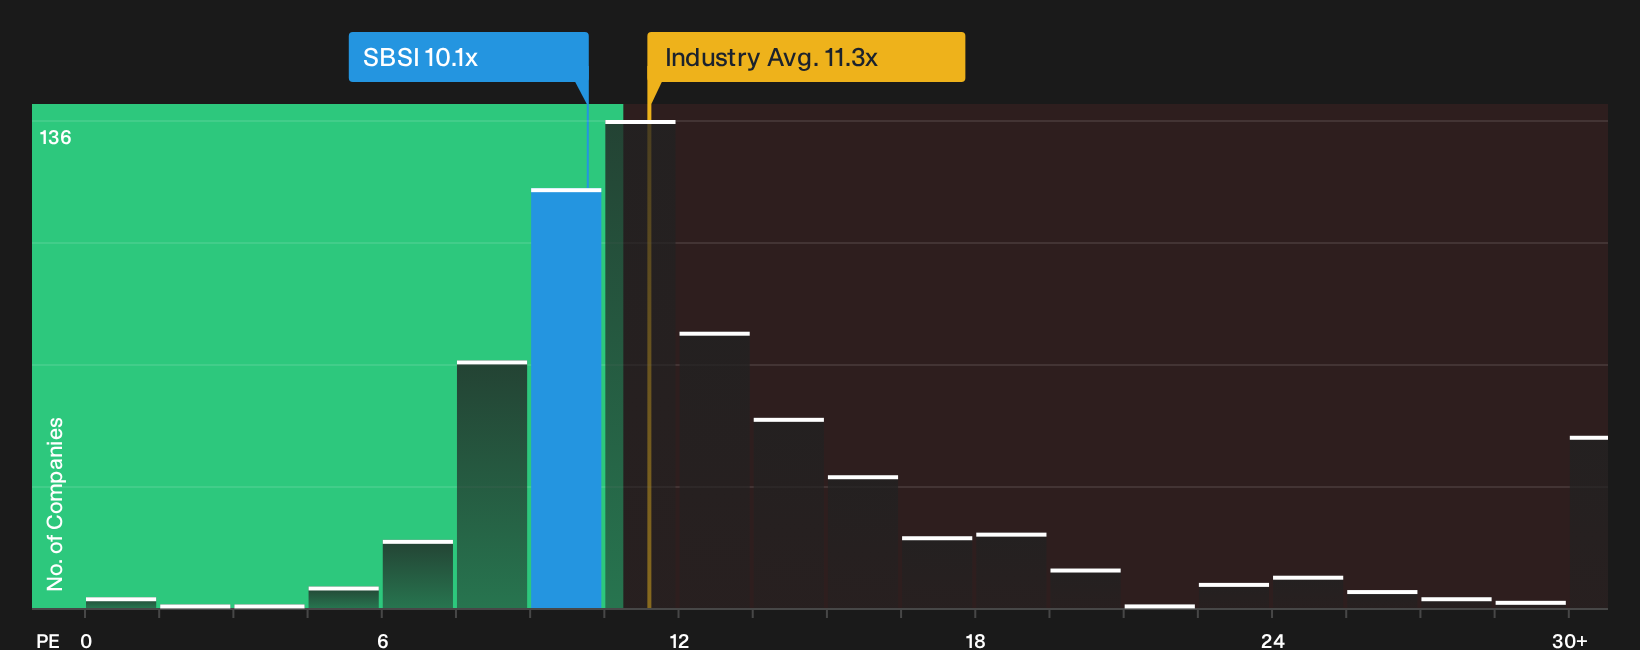
The DCF workup flags Southside Bancshares as good value, yet its P/E of 10.1x sits only slightly above a fair ratio of 10x and below both US Banks at 11.4x and peers at 12.8x. That gap suggests some valuation cushion, but how much comfort does a 1x margin really provide?
To see how this pricing gap could close in either direction, review the valuation breakdown using the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how Southside Bancshares compares with the sector on earnings multiples, refer to
Next Steps
If that mix of caution and optimism around Southside Bancshares resonates, move quickly to conduct your own research and carefully assess both the potential upside and downside. The easiest way to start is by reviewing the 3 key rewards.
Looking for more investment ideas beyond Southside Bancshares?
Do not stop your research with Southside Bancshares. Broaden your watchlist with structured ideas that balance reward potential with meaningful risk checks across different styles of opportunities.
- Target potential mispricing by scanning through 33 high quality undervalued stocks that combine quality fundamentals with prices that screen below their implied worth.
- Lock in potential income streams by reviewing 5 dividend fortresses that pair higher yields with businesses aiming to maintain regular cash returns.
- Prioritise capital protection by focusing on 29 resilient stocks with low risk scores that screen for steadier finances and fewer red flags before trouble shows up in headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com