
Jack Henry & Associates (JKHY) Expands Digital Banking Partnerships, Is It Already Fully Valued?
Partnerships reshape Jack Henry & Associates’ digital banking reach
Jack Henry & Associates (JKHY) is in focus after a run of fintech partnerships, as Nuuvia, Greenlight and StrategyCorps integrations expand the Banno and core platforms into youth banking, family finance and rewards programs.
These partnerships arrive after a sharp 13.2% 30 day share price return. Jack Henry & Associates remains down 9.5% on a year to date share price basis, while longer term total shareholder returns of 8.7% over one year and 15.7% over three years point to steadier compounding in the background.
Scan a curated set of fintech and digital banking peers by starting with 19 high quality undiscovered gems, which echo Jack Henry & Associates’ focus on platforms, integrations, and long-term client relationships.
After a sharp 30 day move and a double digit gap to both analyst targets and intrinsic value estimates, where does fair value for Jack Henry & Associates really land now?
Most Popular Narrative: 1% Undervalued
Jack Henry & Associates closed at $161.34, while the most followed narrative pegs fair value at $163.69, leaving only a narrow gap that still leans to the cheap side based on future cash flow assumptions.
The FY2027 guidance framing contained the call''s most careful navigation. Carsley guided 20 to 40 basis points of margin expansion against a year that delivered 92. She described the reset as prudent conservatism consistent with the company''s starting-gate philosophy, and noted the 2026 outperformance was partly attributable to one-time tailwinds. What she did not say: that the 75 to 95 basis point raised range from May represented any kind of new baseline. The word "floor" that characterized margin guidance language in May was replaced in August with "cautiously optimistic that we can increase that range as the year progresses." Same directional posture, materially lower anchor.
See why 3 investors see Jack Henry & Associates as 1% undervalued.
Result: Fair Value of $163.69 (UNDERVALUED)
Still, Jack Henry & Associates relies heavily on US banking clients, and management’s shifting margin story introduces execution risk around cost control and profitability mix.
Find out about the key risks to this Jack Henry & Associates narrative.
Another view on Jack Henry & Associates’ valuation
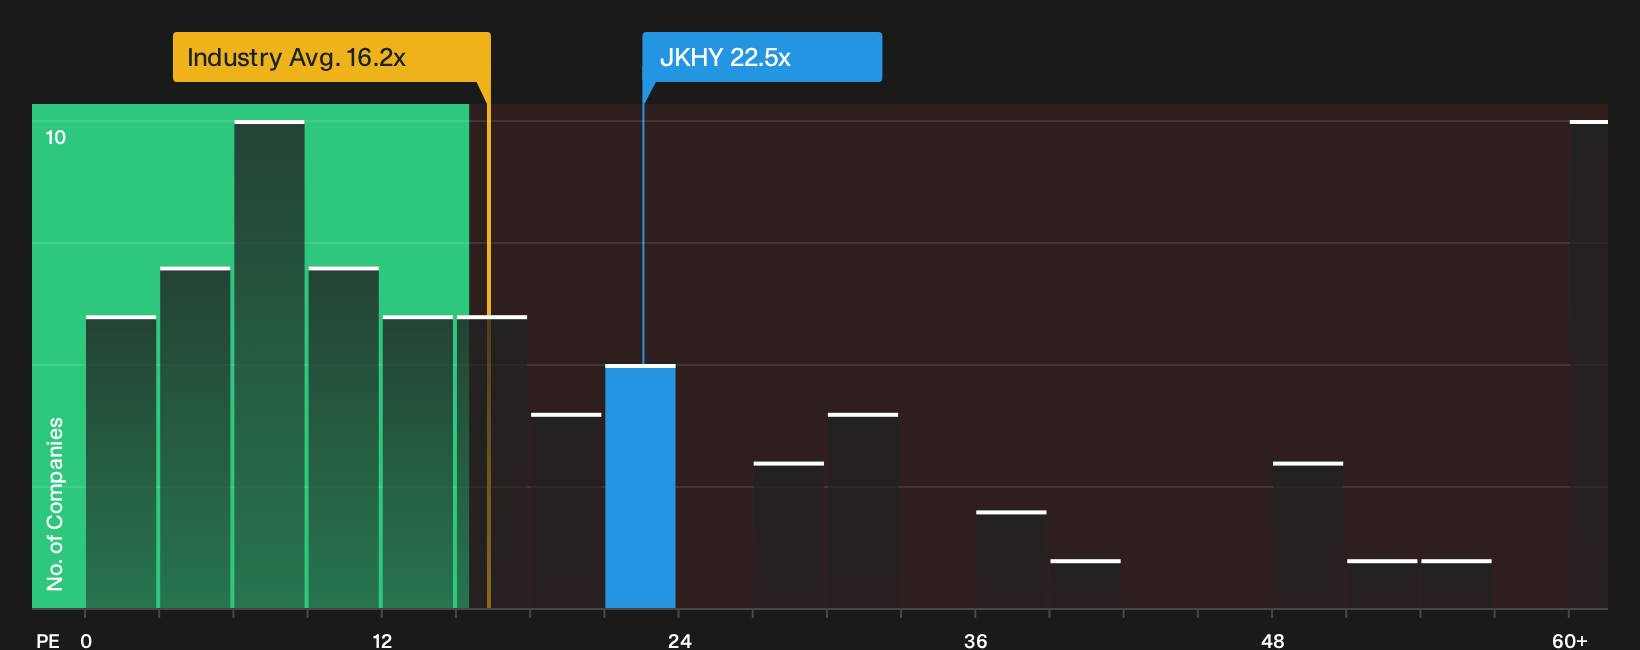
The user narrative leans on future cash flows and lands on Jack Henry & Associates being slightly undervalued at $163.69, close to the current $161.34 price. The market’s own yardstick tells a very different story. On a P/E of 22.5x, the stock trades well above the US Diversified Financial industry at 16.2x, peers at 13.7x, and even our fair ratio of 13.1x. That gap suggests investors are paying a clear premium today, so the key question is whether the quality of the business and its execution record are enough for you to stay comfortable with that kind of valuation risk.
To see how that premium compares across competitors, and where the numbers point, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across Jack Henry & Associates is mixed, and that is exactly why your own read of the data matters. If you want to see the specific upside factors supporting this view, start with the 4 key rewards
Looking for more Jack Henry & Associates style investment ideas?
If you only stop at Jack Henry & Associates, you miss a wider set of opportunities that match different risk levels, income needs, and balance sheet preferences.
- Target potential mispricing by reviewing companies that screen as quality yet underappreciated using the 33 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night holdings by scanning the 29 resilient stocks with low risk scores that filter for steadier profiles.
- Chase dependable income streams by reviewing the 5 dividend fortresses focused on higher yielding businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com