
Maplebear (CART), Why Is It Back In The Spotlight?
Maplebear (CART) is in the spotlight after DoorDash agreed to acquire the grocery delivery platform in a largely cash deal that values the target at about US$16b.
Recent trading has been choppy for Maplebear. The share price has slipped over the past week and day, yet the 30 day share price return of 27.57% and year to date gain of 28.56% suggest momentum has been building, backed by a 1 year total shareholder return of 50.77% and 3 year total shareholder return of 106.70% as investors react to the DoorDash deal, fresh quarterly results, new commercial partnerships, and the recent regulatory settlement.
Scan other potential grocery and delivery beneficiaries of the DoorDash and Maplebear tie-up by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Maplebear now has a clear buyer and fresh earnings on the table. The real tension is simple: Does the current price already capture that story, or is the market still applying a discount?
Most Popular Narrative: 2% Undervalued
At a last close of $56.45, the most followed Maplebear narrative points to a fair value of $57.90, which keeps the stock only modestly below that implied level while still treating future execution as critical.
The continued shift of grocery and essential goods shopping to digital channels, with Instacart reporting GTV of US$10.35b in Q2 2026 and three consecutive quarters of 14% year over year GTV growth, supports the view that a larger online grocery base can feed future revenue and earnings.
See why 20 investors see Maplebear as 2% undervalued.
Result: Fair Value of $57.90 (UNDERVALUED)
Still, rising labor and regulatory pressures, along with higher publisher payments on Carrot Ads, could squeeze Maplebear margins and weaken the current fair value story.
Find out about the key risks to this Maplebear narrative.
Another View: What Multiples Say About Maplebear
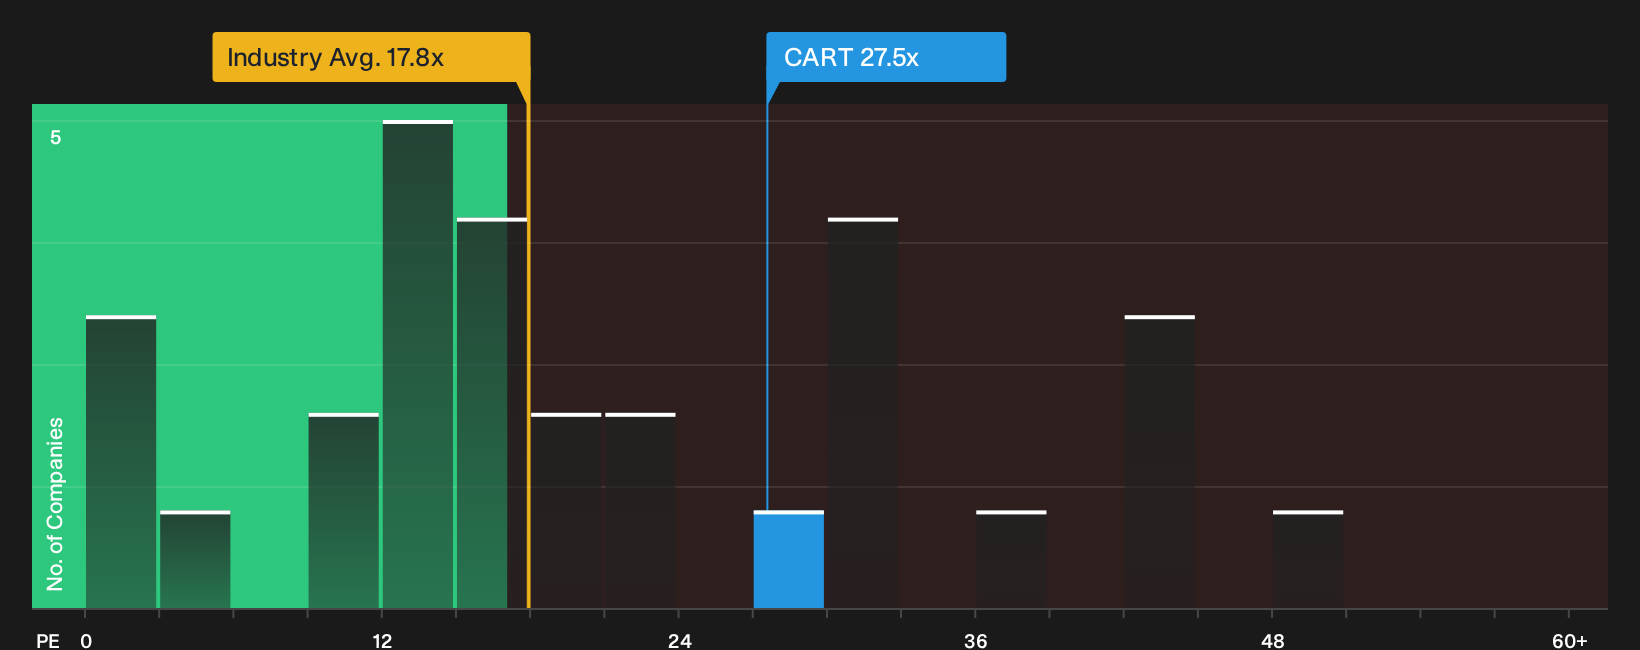
The DCF narrative points to Maplebear as undervalued. The market ratio story is less generous. At a P/E of 27.5x, CART trades above the US Consumer Retailing group on 17.8x and above its own fair ratio of 26.2x, which raises the risk that sentiment, not fundamentals, is doing more of the heavy lifting. How comfortable are you paying a premium if that gap closes from the top down rather than the bottom up?
To pressure test that premium against earnings, peers and the fair ratio that the market could move toward, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Maplebear is clearly mixed, with bulls pointing to upside and bears flagging pressure on the story. Act while the data is fresh and test the case from both sides by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Maplebear investment ideas?
Do not stop with Maplebear. Use fresh screeners to spot other opportunities that fit your style before the crowd pays attention to them.
- Target resilience by checking companies that pair healthy finances with durable operations through our 29 resilient stocks with low risk scores.
- Hunt for mispriced quality by scanning a curated list of potential bargains using the 33 high quality undervalued stocks.
- Review stocks with stronger payout profiles using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com