
National Beverage (FIZZ) Rebounds, But Does The Valuation Case Still Hold?
National Beverage: Recent Returns Put The Spotlight On Fundamentals
Recent share price moves have pushed National Beverage (FIZZ) into sharper focus for investors. The stock has shown a 16.4% gain over the past month and an 11.1% rise over the past 3 months.
The recent 30 day share price return of 16.4% has started to rebuild momentum for National Beverage, although the 1 year total shareholder return of 17.4% contrasts with declines over the 3 and 5 year periods. That pattern suggests that investors are reassessing growth prospects and risks around the current US$35.30 share price, rather than reacting to a single short term headline.
Scan beyond National Beverage and compare this rebound with 33 high quality undervalued stocks, which also combines recent share price momentum with solid fundamentals.
National Beverage now trades near US$35.30 while analyst and intrinsic value estimates sit lower. Is the recent run a stretch above fair value, or a signal those benchmarks lag reality?
Preferred P/E of 18.9x: Is it justified?
On valuation, National Beverage carries a P/E of 18.9x, which prices the stock below peer levels but above both its industry and an estimated fair multiple.
The P/E ratio compares the current share price to earnings per share. For a consumer drinks group like National Beverage, it is a quick way to see how much investors are paying for each dollar of profit in a category where brands, margins and cash generation matter as much as raw growth.
Against direct peers, the gap is wide. National Beverage trades on a P/E of 18.9x, while the peer average sits at 57.5x. This signals the market is assigning a far lower earnings multiple than comparable companies. At the same time, that 18.9x is described as expensive compared to the global beverage industry average of 17x, which points to a richer valuation than the wider sector. The ratio is also above an estimated fair P/E of 15.2x, so the current pricing runs ahead of a level the market could reasonably move towards if expectations cool.
Explore the SWS fair ratio for National Beverage.
Result: Price-to-earnings of 18.9x (OVERVALUED)
Still, if analyst targets remain below the current US$35.30 level and estimated fair value multiples point lower, any slip in National Beverage’s earnings strength or pricing power could quickly pressure that premium.
Find out about the key risks to this National Beverage narrative.
Another View: National Beverage Through The DCF Lens
The earlier P/E discussion painted National Beverage as expensive relative to an estimated fair ratio of 15.2x, yet our DCF model points in a different direction. On that cash flow view, FIZZ at $35.30 trades about 1.8% below an estimated $35.95 fair value. Is this a small margin of safety or just noise around fair pricing?
Look into how the SWS DCF model arrives at its fair value.
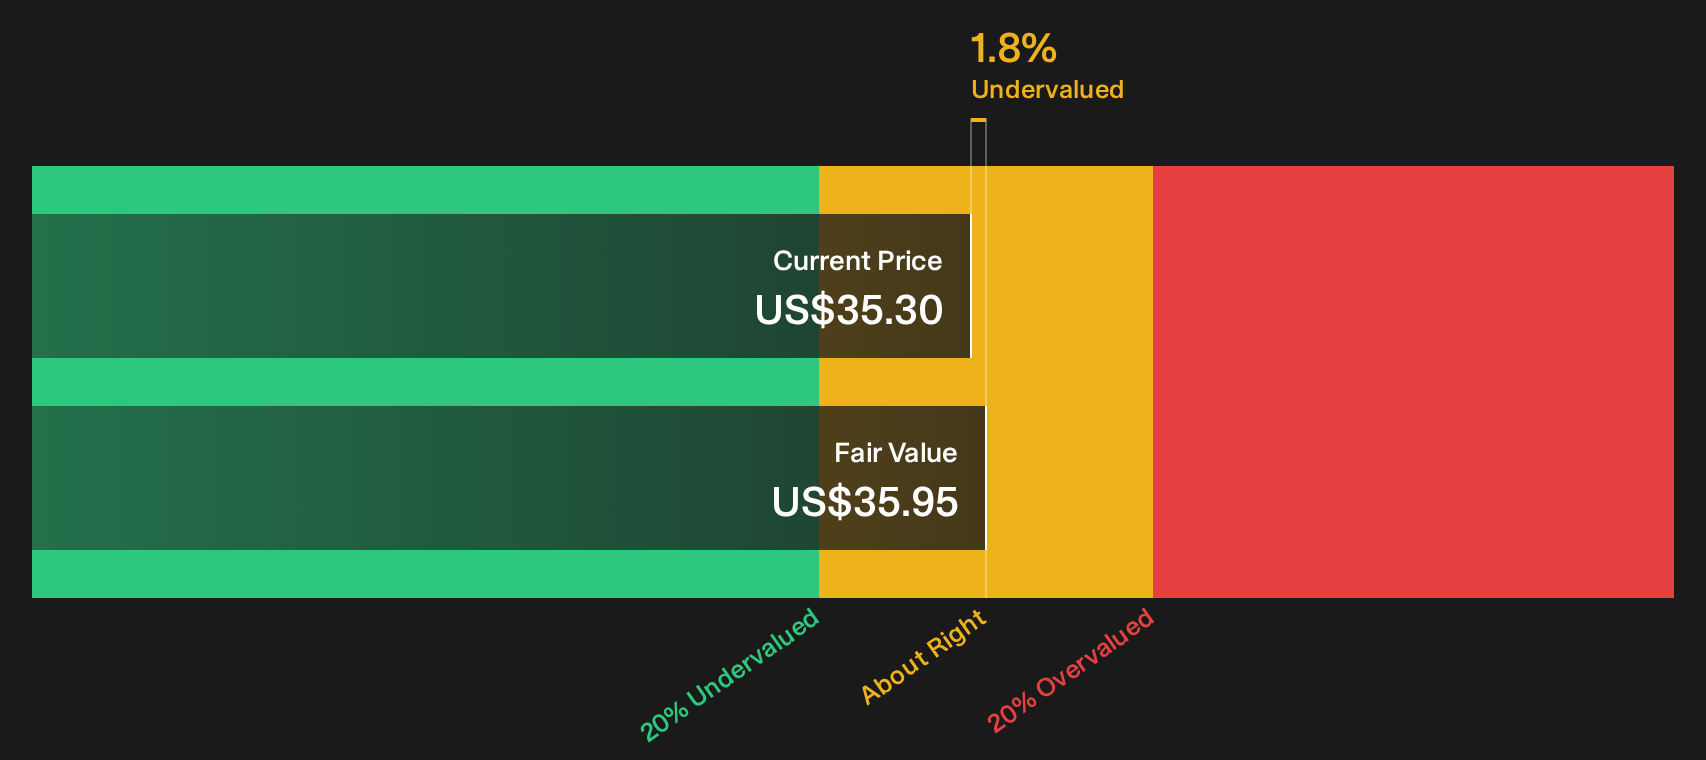
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out National Beverage for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around National Beverage is mixed on value, yet the data is all there for you to stress test that story yourself. Act quickly, weigh the potential upsides directly and ground your own thesis in the 2 key rewards
Looking for more investment ideas beyond National Beverage?
National Beverage offers one data point. Broader context comes from lining it up against other opportunities that share strong balance sheets, value, or income appeal.
- Target resilience by focusing on companies that pair robust finances with measured risk through the 29 resilient stocks with low risk scores.
- Hunt for mispriced quality using the 33 high quality undervalued stocks to spot businesses where fundamentals and pricing appear out of sync.
- Build a stronger income stream by scanning companies in the 5 dividend fortresses that aim to combine higher yields with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com