
How Investors Are Reacting To Reliance (RS) Strong Earnings And Dividend
- Reliance, Inc. reported third quarter 2026 sales of US$5,213.2 million and net income of US$402.9 million, while the board declared a US$1.25 per share cash dividend for stockholders of record on November 20, 2026.
- Basic earnings per share from continuing operations were stronger, at US$7.90 for the quarter and US$19.34 for the first nine months of 2026. This highlights how Reliance is currently converting its diversified metals exposure into earnings and ongoing cash distributions.
- We will now look at how Reliance's earnings per share profile may reshape the existing investment narrative built around steady demand.
Scan how Reliance's latest earnings and dividend profile compares with other metals focused operators by reviewing our curated list of list of solid balance sheet and fundamentals (24 results) in similar capital intensive sectors.
Reliance Investment Narrative Recap
To stay in Reliance, you need to believe this metals service center can keep turning heavy, capital intensive exposure to infrastructure, data centers and defense work into resilient earnings and cash. The latest quarter backs up that idea, with US$5,213.2 million of sales and US$402.9 million of net income supporting value added processing and government contract execution.
The near term catalyst still sits in how Reliance manages pricing and volumes while LIFO expense and aluminum tariffs pressure reported margins. That risk has not gone away. Trade policy, metal cost swings and tariff shifts remain the biggest threat to this earnings profile, even with current demand looking supportive.
The dividend affirmation is the announcement that ties closest to this earnings release. A US$1.25 per share quarterly payout, together with higher basic EPS from continuing operations at US$7.90 in the quarter and US$19.34 for the first nine months of 2026, shows Reliance turning current profitability into direct cash returns.
For you as a shareholder, the practical question is whether the business can keep funding that dividend while handling tariff driven margin compression and higher non cash LIFO charges. The combination of large government projects, processing heavy revenues and a still volatile input cost backdrop keeps execution on pricing and inventory the key operational swing factor.
What Consensus Expectations Say About Reliance
Analysts looking at Reliance are not baking in a big top line swing. Revenue is expected to stay broadly flat over the next three years, with forecasts calling for around US$17.5b of sales by 2029. That is paired with only a small shift in profit margin assumptions, from 6.4% today to 6.3% in three years, which keeps the earnings outlook anchored to where the business is now.
On current estimates, earnings today are about US$1.1b, or US$22.86 per share, and consensus calls for roughly the same profit level by 2029. Put differently, the analyst view does not hinge on a higher earnings base. It relies on Reliance maintaining its present earnings power while working through tariff costs, LIFO expense and volume swings tied to infrastructure and defense work.
That stability driven story filters directly into the valuation math. The analyst price target of US$418.67 assumes Reliance trades on a P/E of 23.3x those US$1.1b 2029 earnings, compared with about 19.3x today and an industry multiple of 18.1x for US metals and mining peers. For you, the question is less about earnings growth and more about whether Reliance deserves that richer earnings multiple given its contract exposure, processing mix and balance sheet.
With the current share price around US$417.92 and the consensus target only 0.2% higher, the market price already lines up closely with that scenario. Any shift in your view on revenue resilience, margin pressure from tariffs or the sustainability of government project volumes can easily move your own estimate of fair value above or below that analyst mark.
Reliance's narrative projects about US$17.5b of revenue and US$1.1b of earnings by 2029. This assumes revenue stays broadly flat, with earnings holding near current levels of roughly US$1.1b rather than requiring a material increase or decline.
Uncover why Reliance's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
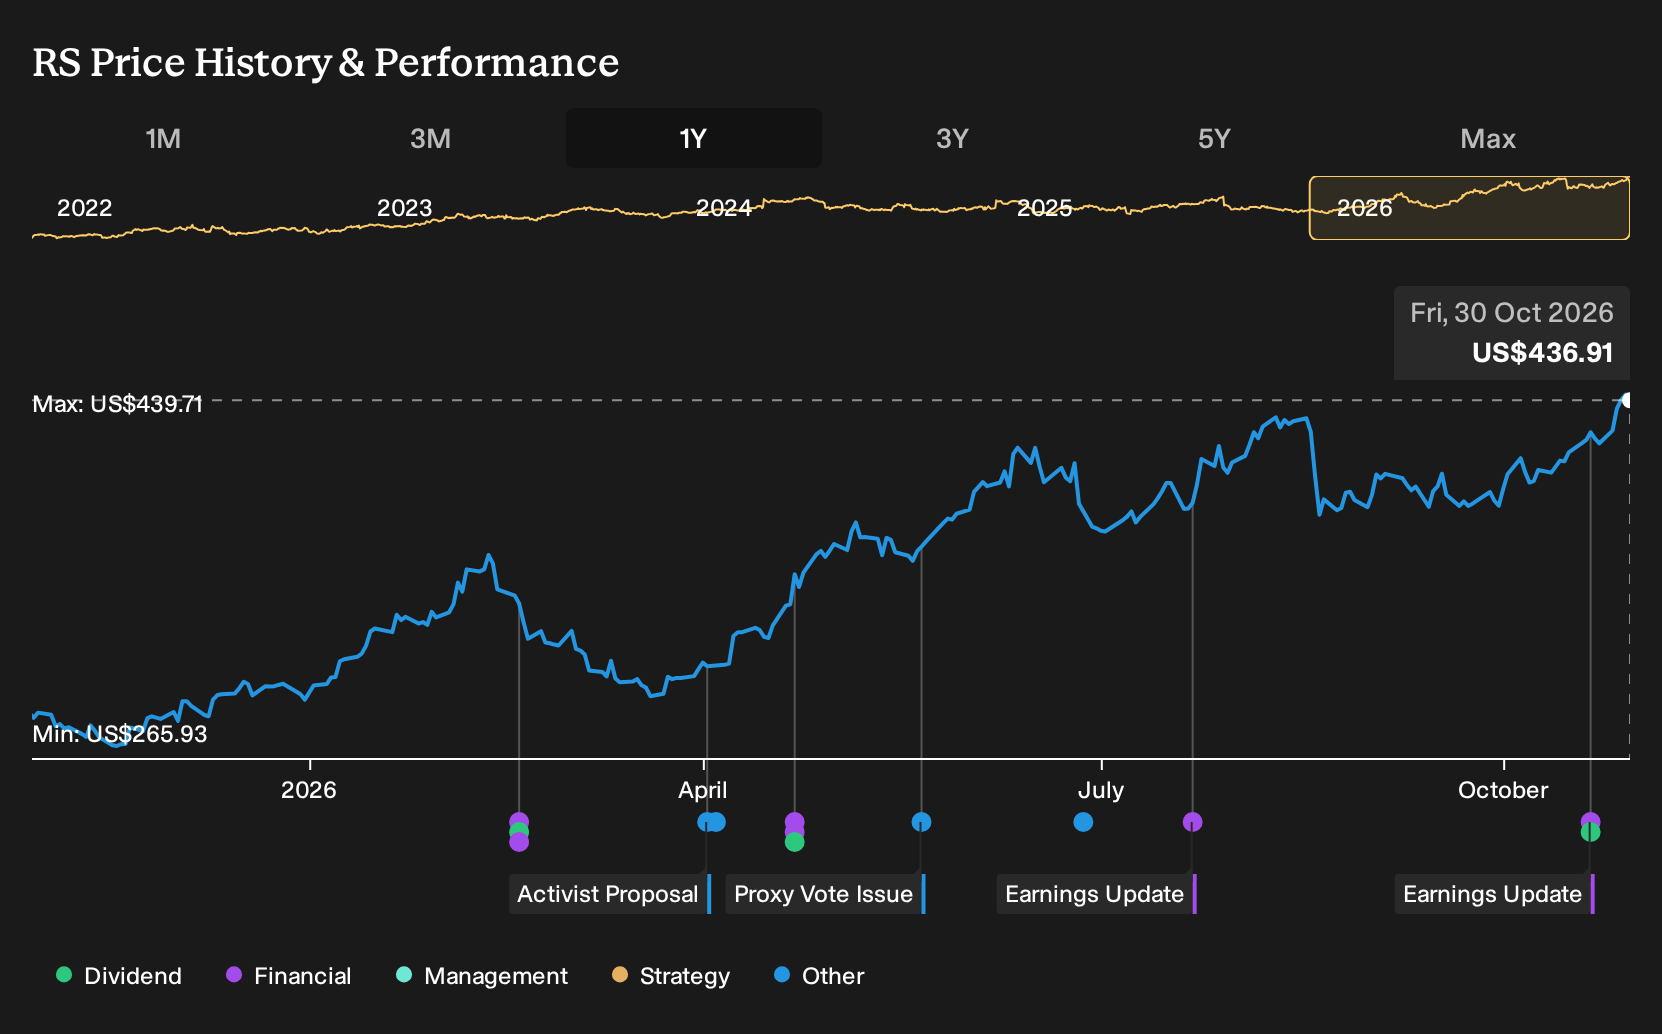
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$169 per share to roughly US$419, which already matches the analyst target band mentioned earlier. That spread shows how differently private investors weigh Reliance’s tariff exposure, LIFO charges and government projects. Use those contrasting views to test your own assumptions.
Explore another Reliance fair value estimate, including one that suggests it could be worth as much as $418.67.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Reliance research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for Reliance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Reliance's overall financial health at a glance.
Looking For More Ideas Beyond Reliance?
If Reliance has sharpened your view on metals exposed businesses but you want a wider bench of possibilities, use the Simply Wall St Screener to filter for stocks that better match your risk tolerance, income needs and balance sheet preferences.
- If capital preservation comes first for you, scan a curated 29 resilient stocks with low risk scores that aims to keep downside risk in check.
- If income is the priority, review a focused 5 dividend fortresses that concentrates on payout strength and sustainability.
- If you want to widen the research funnel, survey a handpicked 19 high quality undiscovered gems that pairs strong fundamentals with less crowd attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com