
Mirion Technologies (MIR) Raised Revenue Outlook, Is The Stock Still Cheap?
Mirion Technologies (MIR) linked stronger third quarter figures to a higher full-year revenue outlook, after reporting increased sales and net income and providing guidance for 24% to 25% revenue growth for 2026.
Mirion Technologies shares trade at US$18.37 after a sharp 7 day share price return of 23.12% and a 30 day share price gain of 25.82%. However, the stock is still down 22.91% on a year to date basis, and the 1 year total shareholder return has fallen 37.54%, even though the 3 year total shareholder return is up more than 2x, which suggests recent momentum has picked up again following the upgraded 2026 revenue guidance and October earnings update.
Scan how Mirion Technologies compares with other radiation and nuclear infrastructure plays by reviewing our curated list of 16 nuclear energy infrastructure stocks riding similar demand trends.
After a 23% weekly jump and a 21% discount to the average analyst target, Mirion Technologies now sits between past pessimism and refreshed optimism. Where does a reasonable fair value range actually land on that spectrum?
Most Popular Narrative: 22% Undervalued
Mirion Technologies is priced at $18.37 while the most followed narrative anchors fair value at $23.55, which points to a sizeable gap that analysts are tying to nuclear demand, software mix and margin rebuilding.
The accelerating global shift toward expanded nuclear power generation, coupled with rising capital budgets for modernization, life extensions, and increased capacity of the existing reactor fleet, is described as a driver of sustained double-digit organic revenue growth and an expanding higher-margin installed base business for Mirion in coming years. Commentators also highlight strong momentum in advanced nuclear projects, including utility-scale new builds and rapid activity in the small modular reactor (SMR) market, which has materially broadened Mirion's pipeline of large, multi-year opportunities and created potential for significant step-changes in future order intake, backlog, and top-line revenue.
See why 8 investors see Mirion Technologies as 22% undervalued.
Result: Fair Value of $23.55 (UNDERVALUED)
Still, concentration in nuclear projects and reliance on acquisitions leave Mirion Technologies exposed if reactor pipelines slow or integrations fail to deliver expected benefits.
Find out about the key risks to this Mirion Technologies narrative.
Another View on Mirion Technologies Valuation
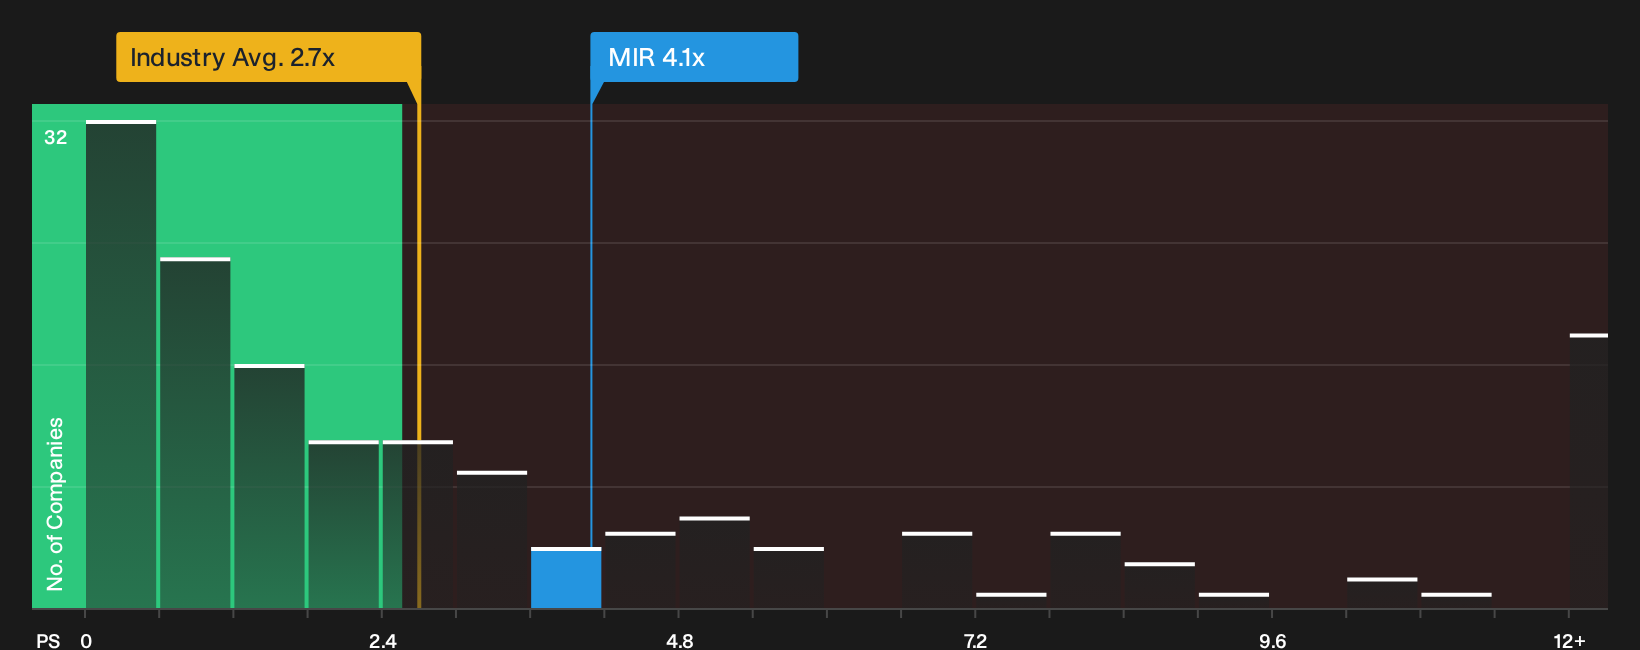
Analysts lean on earnings forecasts to support Mirion Technologies at $23.55, yet the current P/S ratio of 4.1x tells a different story when compared with the US Electronic industry on 2.7x and a fair ratio of 2.7x. Is this simply growth optimism, or is investors' margin for error getting thin?
For a closer look at how those sales multiples compare and what the fair ratio implies for future repricing risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There have been mixed messages in the Mirion Technologies story so far. Use the full data set, not just the headlines, and pressure test your own thesis with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Mirion Technologies?
Do not stop at Mirion Technologies. Fresh opportunities sit across sectors, and a few focused screens can help you spot quality setups before the crowd moves.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with attractive valuations using 36 high quality undervalued stocks.
- Strengthen your defensive side by filtering for businesses that pair resilient finances with lower risk profiles through the 29 resilient stocks with low risk scores.
- Get ahead of the herd by reviewing a focused 19 high quality undiscovered gems list that surfaces strong fundamentals before they hit most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com