
Cellebrite DI (CLBT) Unveils Its Autumn 2026 AI Release, Is The 21% Undervaluation Real?
What Cellebrite DI’s Autumn 2026 AI Release Means For Investors
Cellebrite DI (CLBT) has put artificial intelligence at the center of its Autumn 2026 Release, headlined by the Genesis solution that aims to catch digital evidence missed by manual review.
The launch is paired with expanded access to more devices and new tools across Pathfinder, Corellium and Guardian. Together, these offerings reshape how agencies can collect, organize and act on growing volumes of digital data.
Against that product backdrop, Cellebrite DI’s share price sits at US$12.15, with a roughly 10% 1 month share price gain following the Autumn 2026 Release, set against steeper 90 day and year to date share price declines. However, the 3 year total shareholder return of about 68% still points to a materially stronger longer run outcome than the past year’s drop of around 27%.
Scan how Cellebrite DI’s AI push compares with other tech-driven opportunities by running through the hand picked 41 profitable AI stocks that aren't just burning cash.
Cellebrite DI’s recent rebound after a tougher 12 months could either be the first sign that its AI push is feeding into fundamentals, or just a brief reset in sentiment before the next swing. How does the current price compare with the underlying business?
Most Popular Narrative: 21% Undervalued
On the most followed narrative, Cellebrite DI is valued at a fair value of about $15.36 compared with the recent $12.15 share price, which frames the Autumn 2026 AI release inside a broader long term growth story built on recurring software economics.
The continued transition to a recurring, subscription-based revenue model, with over 90% of revenues now from subscriptions and growing SaaS/cloud penetration, improves revenue visibility, predictability, and operating leverage, which is already translating into higher EBITDA and free cash flow margins and is likely underappreciated in current valuations.
See why 20 investors see Cellebrite DI as 21% undervalued.
Result: Fair Value of $15.36 (UNDERVALUED)
Still, analyst confidence in Cellebrite DI’s long term AI and cloud story runs into two big pressure points: slower federal contract momentum and ongoing regulatory scrutiny around data access.
Find out about the key risks to this Cellebrite DI narrative.
Another Angle On Cellebrite DI’s Valuation
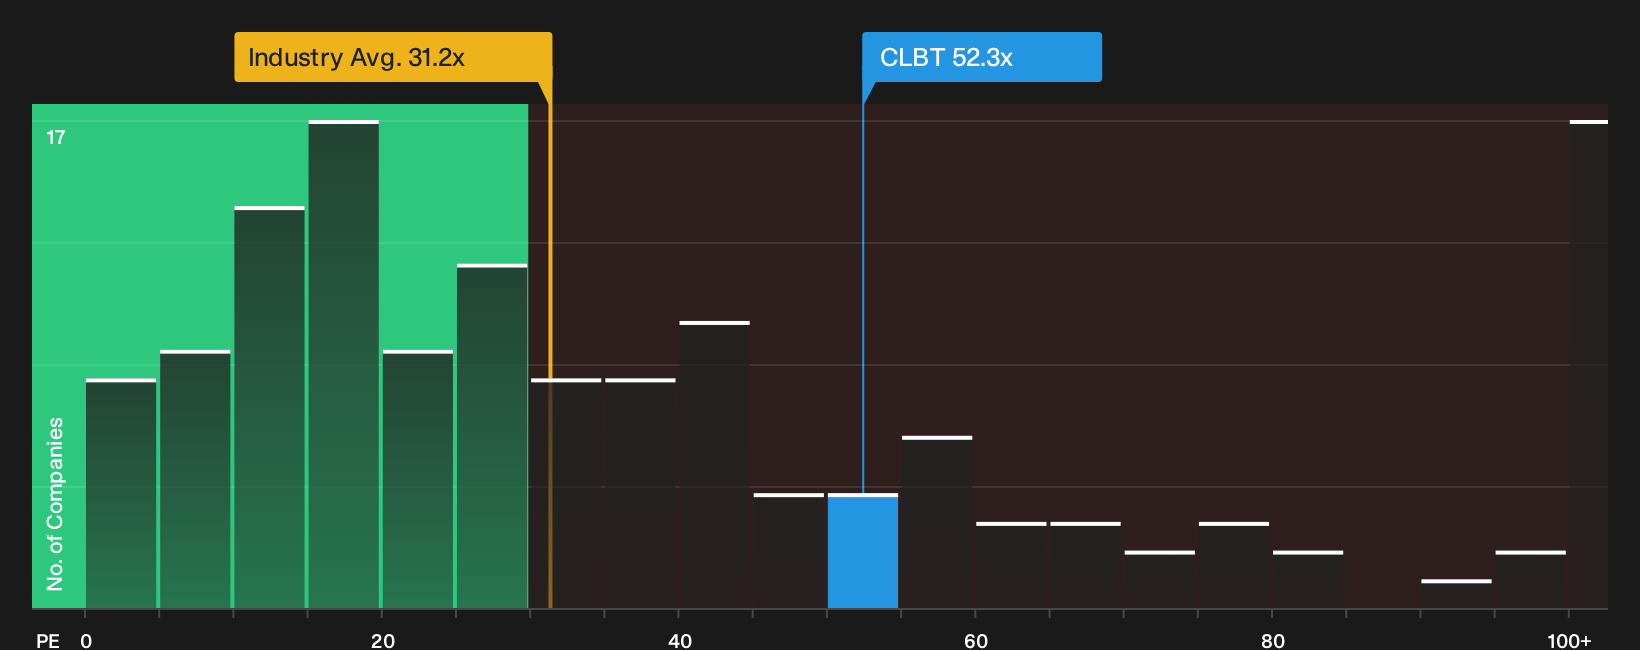
On price tag alone, Cellebrite DI looks cheap against the US$15.36 fair value estimate. On earnings multiples it tells a different story, with a current P/E of 52.3x versus a fair ratio of 34.3x, the US Software sector at 31.2x, and peers at 45x. That kind of premium can reward patience if growth keeps pace, but it also raises the question of how much good news is already baked in.
To pressure test whether that premium multiple still makes sense for you, go through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Cellebrite DI’s story so far. If you want to act while sentiment is still forming, weigh both sides through the 4 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Cellebrite DI?
Cellebrite DI might be on your radar, but your next strong move could come from widening the search with a few focused, high quality stock ideas.
- Target resilient balance sheets and skip fragile stories by scanning a curated list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center for your shortlist.
- Hunt for value where quality and price still line up by running through a focused 36 high quality undervalued stocks before the crowd starts paying closer attention.
- Lock in potential portfolio ballast with reliable income streams by reviewing a hand picked 5 dividend fortresses that screens for higher yields and sturdier payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com