
Ciena (CIEN) Lifted Its Guidance, Is The Stock Fully Priced?
Ciena (CIEN) has moved back into focus after reporting 37% year-over-year revenue growth in Q3, lifting its full-year outlook and committing US$200 million to an AI-focused Ciena Ventures program.
Recent trading tells a more cautious story. The share price fell 8.2% in the last session and is down 18.1% over the past month and 22.0% across three months, even though the year to date share price return is 30.3% and the one year total shareholder return is 69.2%. This points to strong longer term gains but fading short term momentum as investors reassess how much of Ciena’s AI and networking opportunity is already reflected in the current US$320.72 price.
Compare Ciena's renewed AI momentum with other potential opportunities by scanning a curated mix of quality-focused candidates in our 36 high quality undervalued stocks.
Ciena now looks like a strong franchise facing a tougher question: Is this recent pullback handing you quality at a sensible price, or simply marking a reset after an overheated run higher?
Most Popular Narrative: 38% Undervalued
The most followed narrative on Ciena pegs fair value around $513, well above the recent $320.72 close, which puts the current pullback against a long runway built on AI driven optical demand, margin ambitions and heavy reinvestment.
Planned capital deployment that includes US$2.5 to 3.0b of R&D over three years, roughly US$20b of available M&A capacity and a commitment to return at least 70% of free cash flow to shareholders absent large deals, creates several potential levers for Ciena to influence future revenue growth, earnings and per share cash returns that are not fully reflected in current results.
See why 59 investors see Ciena as 37% undervalued.
Result: Fair Value of $512.99 (UNDERVALUED)
Still, the Ciena narrative depends heavily on hyperscalers sustaining current spending patterns and on component bottlenecks easing enough for that US$10b backlog to convert cleanly.
Find out about the key risks to this Ciena narrative.
Another View: Ciena Through The P/E Lens
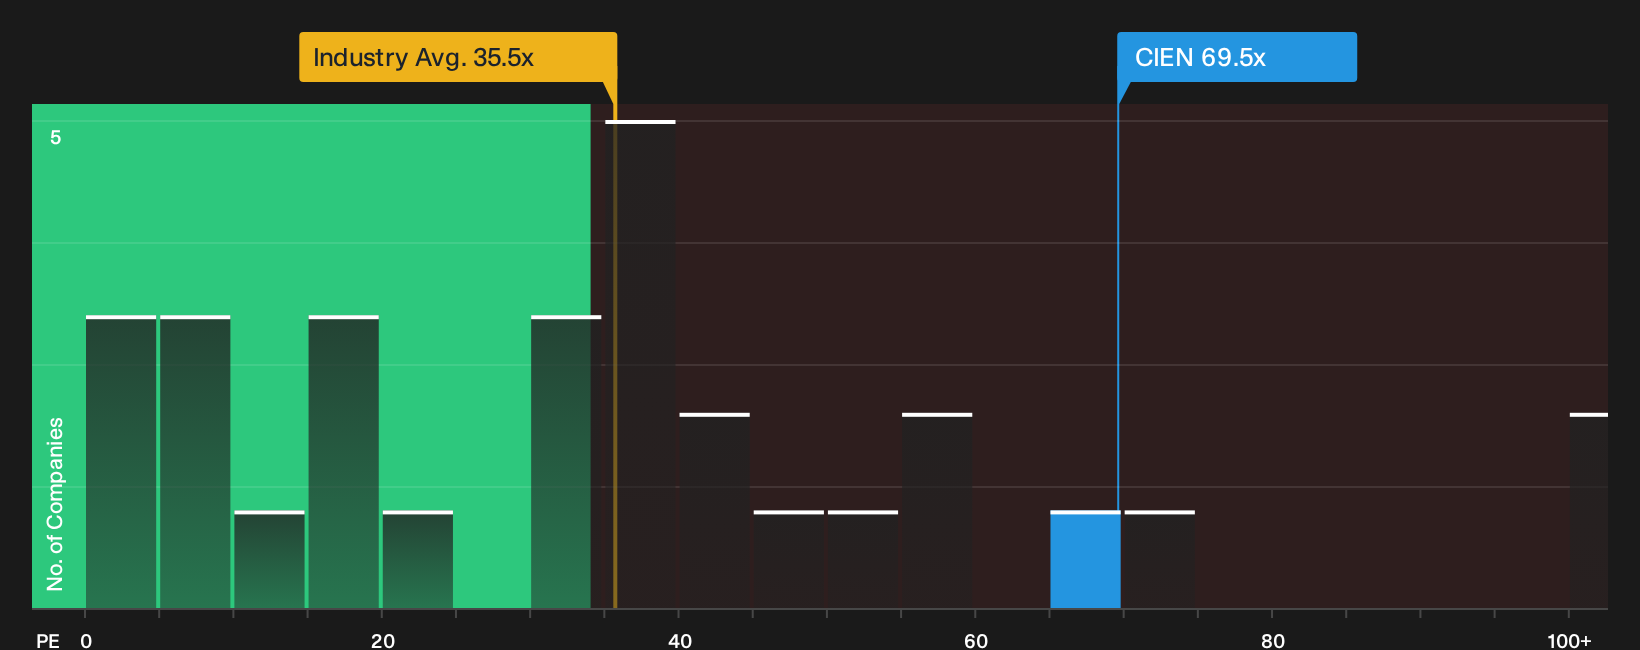
Ciena may look attractively priced on intrinsic value models, yet the current P/E of 69.5x tells a different story. That figure sits well above the US Communications industry at 35.5x and a fair ratio of 41.9x, which points to meaningful valuation risk if sentiment cools.
The gaps between today’s P/E, peers, and the fair ratio mean any stumble in execution or AI demand could hit the share price even if earnings keep progressing. The real question is how much optimism you are willing to pay for Ciena today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Ciena feels familiar, act while the data is still fresh and shape your own view. To weigh the upside against the concerns, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ciena?
If Ciena has sharpened your focus, do not stop here. Broaden your watchlist with fresh angles that can round out your portfolio and surface new opportunities.
- Target resilient balance sheets and steadier fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financial strength before excitement.
- Hunt for mispriced opportunities by reviewing the 19 high quality undiscovered gems that highlights companies with strong fundamentals that the market may be overlooking.
- Prioritise capital preservation alongside returns by using the 29 resilient stocks with low risk scores to focus on businesses with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com