
What Welltower Stock's Raised Earnings Outlook Means For Shareholders
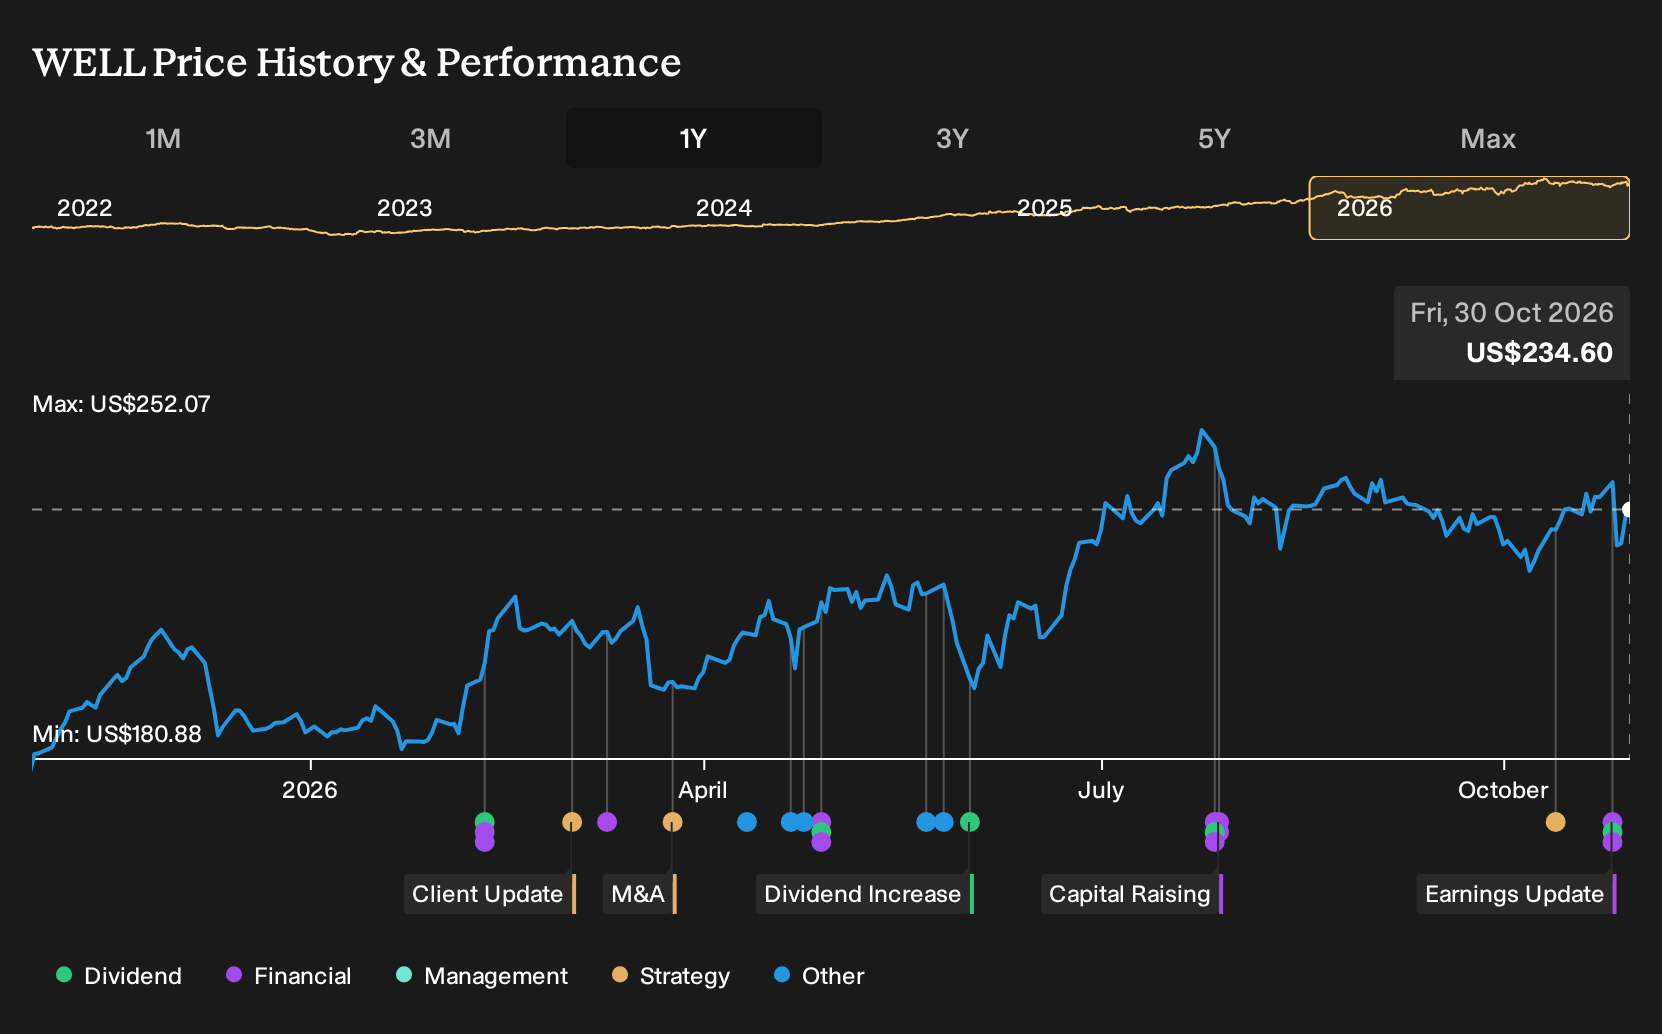
- Welltower reported third quarter 2026 net income of US$396.59 million and diluted EPS from continuing operations of US$0.54, alongside nine month net income of US$1,570.26 million and diluted EPS of US$2.16.
- The board’s decision to declare a 222nd consecutive quarterly dividend of US$0.85 per share highlights Welltower’s ongoing focus on returning cash to shareholders while reporting higher net income and earnings per share year to date.
- We will now look at how Welltower's investment narrative could be influenced by its higher full year earnings guidance and recent profitability.
Scan beyond Welltower and see how other income focused real estate stocks shape up by reviewing our hand picked 5 dividend fortresses alongside this latest earnings and dividend update.
Welltower Investment Narrative Recap
To own Welltower, you need to believe its senior housing focus can keep turning resident demand and operating efficiency into consistent earnings, even as macro conditions and interest costs stay unpredictable. The latest results show revenue and net income for the quarter and first nine months at levels that support this narrative, although one off items still affect reported profit quality.
The raised full year earnings guidance puts short term attention on execution across the large senior housing operating portfolio and the new fund management platform. The biggest near term risk remains that higher living costs or rates slow move ins into communities, which would pressure occupancy and undercut the benefit of recent capital recycling.
The most relevant new data point is the revised 2026 net income guidance. Management now expects US$3.31 to US$3.37 per diluted share for common stockholders, up from US$3.11 to US$3.19, and a higher net income range of US$2.47b to US$2.515b. That gives a fresh reference for how the business sees its earnings capacity after recent portfolio changes.
For you, the guide up ties directly into the main catalysts. It frames how improved margins in senior housing, contribution from the private funds platform and stabilization of newly acquired properties might show up in reported net income. It also sharpens the risk that any slowdown in occupancy, expense control or fee income would make this higher range harder to achieve.
What the Long Range Forecasts Assume for Welltower
Welltower's narrative projects US$19.3 billion revenue and US$2.9 billion earnings by 2029. That implies 14.8% yearly revenue growth and an earnings increase of about US$1.3 billion from US$1.6 billion today.
Uncover how Welltower's fair value indicates a 12% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One bullish twist on Welltower focuses on how quickly under occupied senior housing could fill. Before this earnings beat and guidance lift, the most optimistic analysts were already pencilling in revenue of about US$22.5b and earnings near US$3.9b by 2029. Those projections were set without seeing today’s numbers, so those narratives may evolve.
Explore 5 other Welltower fair value estimates, including one that suggests as much as 24% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Welltower research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Welltower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Welltower's overall financial health at a glance.
Looking for more investment ideas beyond Welltower?
If the Welltower story has sharpened your thinking, use that momentum to compare it with other opportunities. A focused screener can help you quickly spot companies that match the income profile, risk tolerance, or balance sheet strength you prefer.
- For investors who want potential upside with a margin of safety, start with a curated set of companies trading below estimated value through our 36 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, narrow your search to businesses with stronger risk scores using the 29 resilient stocks with low risk scores.
- To widen your watchlist beyond widely followed large caps, review a hand picked 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com