
Does Saucony Sales Growth Change The Bull Case For Wolverine (WWW)?
- Saucony, owned by Wolverine World Wide, reported US$533.1 million in 2025 revenue with 31.1% growth, which supported management's decision to raise the full year outlook and highlighted running footwear as a key contributor.
- The CEO framed Saucony and Merrell as primary growth drivers within Wolverine World Wide, indicating where future brand investment and execution focus may concentrate across the portfolio.
- This analysis examines how Wolverine World Wide's investment narrative is influenced by Saucony's reported revenue performance and updated outlook.
Scan for other footwear and apparel stocks with similar brand momentum by checking the hand picked 19 high quality undiscovered gems that share some of Wolverine World Wide's portfolio-driven potential.
Wolverine World Wide Investment Narrative Recap
To own Wolverine World Wide, you need to believe the portfolio can keep leaning on Saucony and Merrell while management tidies up weaker labels and a still heavy wholesale mix. The Saucony revenue update supports the idea that core performance brands can carry more weight. The near term swing factor remains execution on this brand elevation plan rather than a single quarter.
The key risk is that strong Saucony demand fails to offset slower progress in legacy lines and the cost of higher marketing and SG&A. Wholesale dependence, at roughly three quarters of the business, also leaves Wolverine exposed if retailers tighten orders or push back on pricing.
With no fresh regulatory filings or deal announcements tied directly to this update, the most relevant information is still management’s earlier focus on brand elevation and portfolio optimisation. Saucony’s 2025 revenue of US$533.1 million, with 31.1% growth, aligns with that message and indicates where effort has been concentrated operationally.
For you as an investor, the link is straightforward. Stronger Saucony performance gives Wolverine more room to continue investing in marketing, digital and international expansion while working through high debt and underperforming units such as Sweaty Betty and the Work Group. Execution against these priorities remains the core catalyst and also the main operational test.
Wolverine World Wide's current analyst narrative points to revenues of US$2.3b and earnings of US$183.1 million by 2029, based on revenue growth of 5.5% per year and an earnings increase of about 73% from US$105.6 million today.
Uncover why Wolverine World Wide's fair value indicates a 17% potential upside to its current price that could narrow quickly.
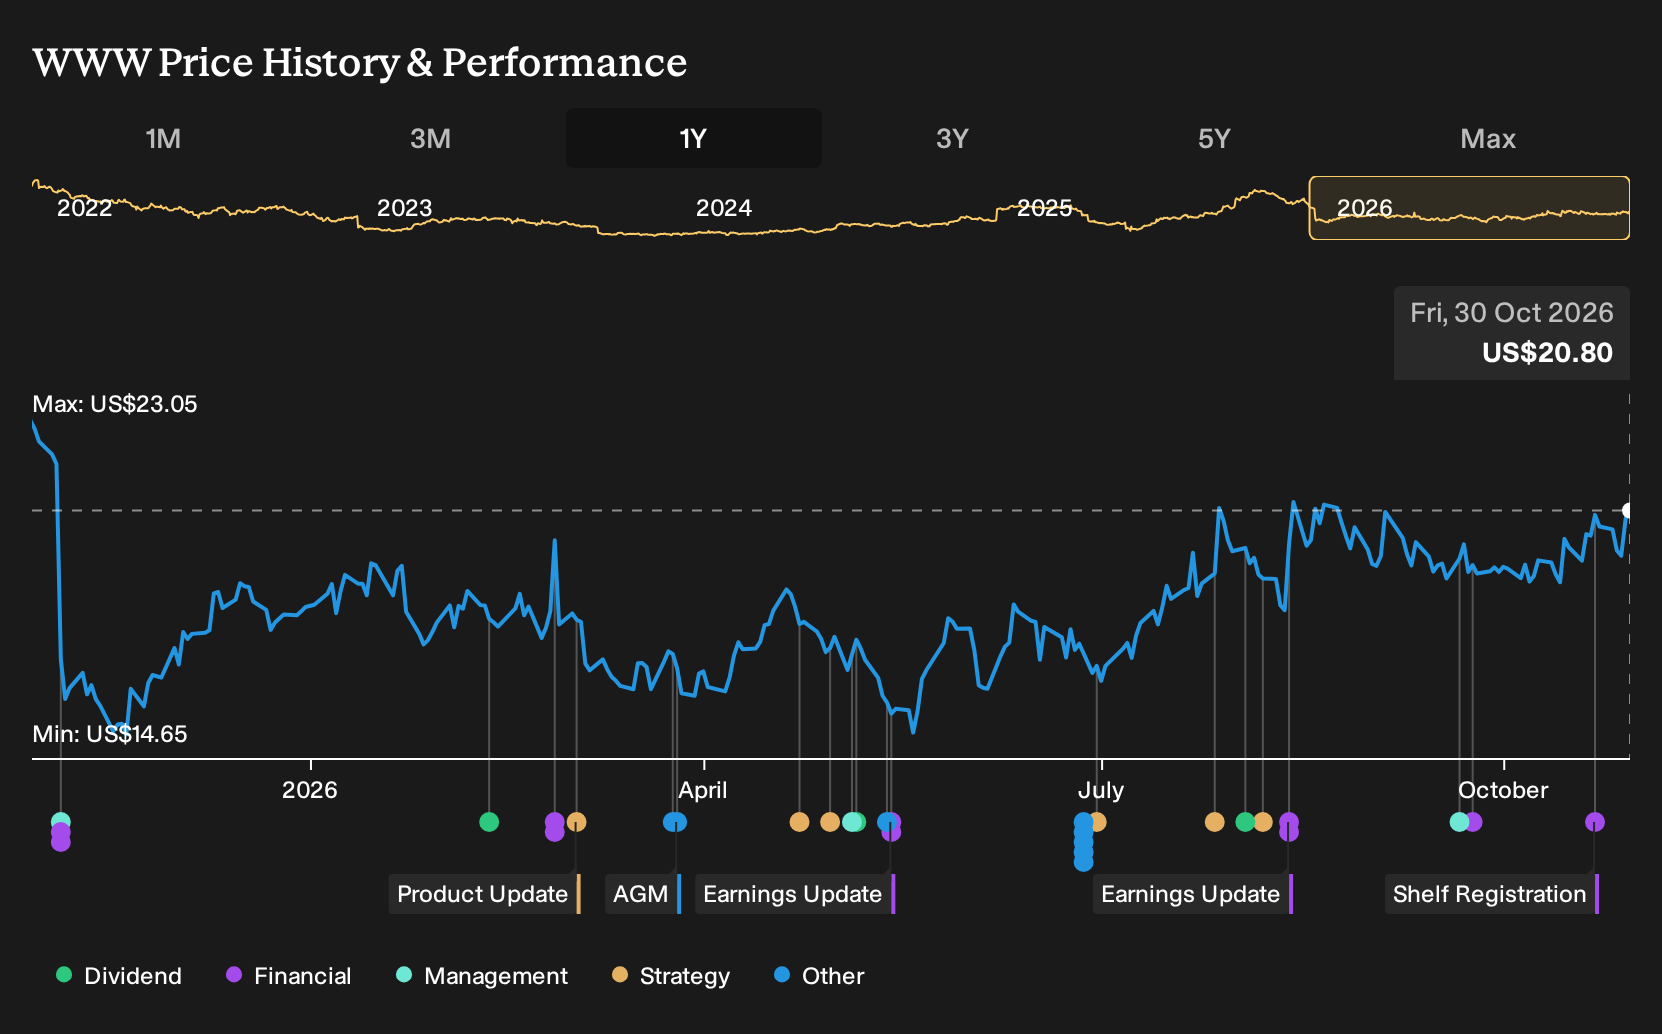
Exploring Other Perspectives
One bullish twist on Wolverine World Wide focuses less on Saucony’s sales jump and more on a faster margin reset. Before this update, the most optimistic analysts were already modelling US$2.4b of revenue and US$189.3 million of earnings by 2029. That is a higher bar than consensus, and this Saucony news may push those projections to shift again.
Explore 3 other Wolverine World Wide fair value estimates, including one that suggests as much as 49% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Wolverine World Wide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wolverine World Wide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wolverine World Wide's overall financial health at a glance.
Looking For More Ideas Beyond Wolverine World Wide?
If you want to keep building a watchlist around themes similar to Wolverine World Wide, the Simply Wall St Screener can help you quickly spot other businesses with balance sheet strength, income potential, or quieter momentum stories that the wider market may not be focused on yet.
- For investors who care most about resilience and capital protection, start with a 29 resilient stocks with low risk scores that might better match your comfort with volatility.
- If steady income matters to your plan, use the 5 dividend fortresses to find candidates that combine higher yields with more durable payout records.
- When the goal is to uncover quieter opportunities with room to prove themselves, scan the 19 high quality undiscovered gems and see which profiles fit your process.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com