
CDW (CDW) Adds AI Veteran To Its Board, But Is The Growth Story Already Priced In?
CDW (CDW) stock is in focus after the company added Saranga (Sam) Balaji to its board of directors, bringing decades of experience in artificial intelligence, cloud, cybersecurity and large-scale technology advisory work.
Despite the latest board appointment drawing fresh attention to CDW, recent trading has been choppy, with the share price down 6.9% on a 1-day basis and lower by 5.8% over the past week, even after a 15.4% 30-day share price return and a 15.5% year to date gain. That mixed pattern sits against a softer long view, where total shareholder return is only 1.4% over one year and remains down over three and five years. This can signal that investors are still reassessing both growth potential and risk as CDW leans further into AI, cloud and cybersecurity projects.
Scan for other underowned beneficiaries of AI, cloud and cybersecurity demand by reviewing the hand-picked 54 AI infrastructure stocks that sit closest to CDW’s core opportunity set.
CDW trades about 3% below the average analyst target and at a materially larger discount to one fair value estimate, even after the recent pullback. Is that caution justified by the track record investors have lived through?
Most Popular Narrative: 3% Undervalued
CDW closed at $153.79, while the most followed narrative pegs fair value around $158.67. This suggests a modest valuation gap that leans on specific growth, margin, and cash flow assumptions.
Expansion of CDW's software, professional, and managed services capabilities, now reinforced by the Lovelytics data and AI acquisition that adds over 600 specialists, supports a shift toward higher value recurring services that can influence mix, margins, and earnings as customers move from AI hardware buildouts into deployment and ongoing management.
See why 13 investors see CDW as 3% undervalued.
Result: Fair Value of $158.67 (UNDERVALUED)
Still, the CDW story can break if hardware-heavy demand continues to pressure gross margins or if services and cash conversion lag the narrative for longer.
Find out about the key risks to this CDW narrative.
Another View: CDW On Earnings Multiples
The first fair value story for CDW focused on future cash flows and landed on a $218.33 estimate, which puts the current $153.79 price at a steep discount. Look at earnings multiples though and the picture is less one sided.
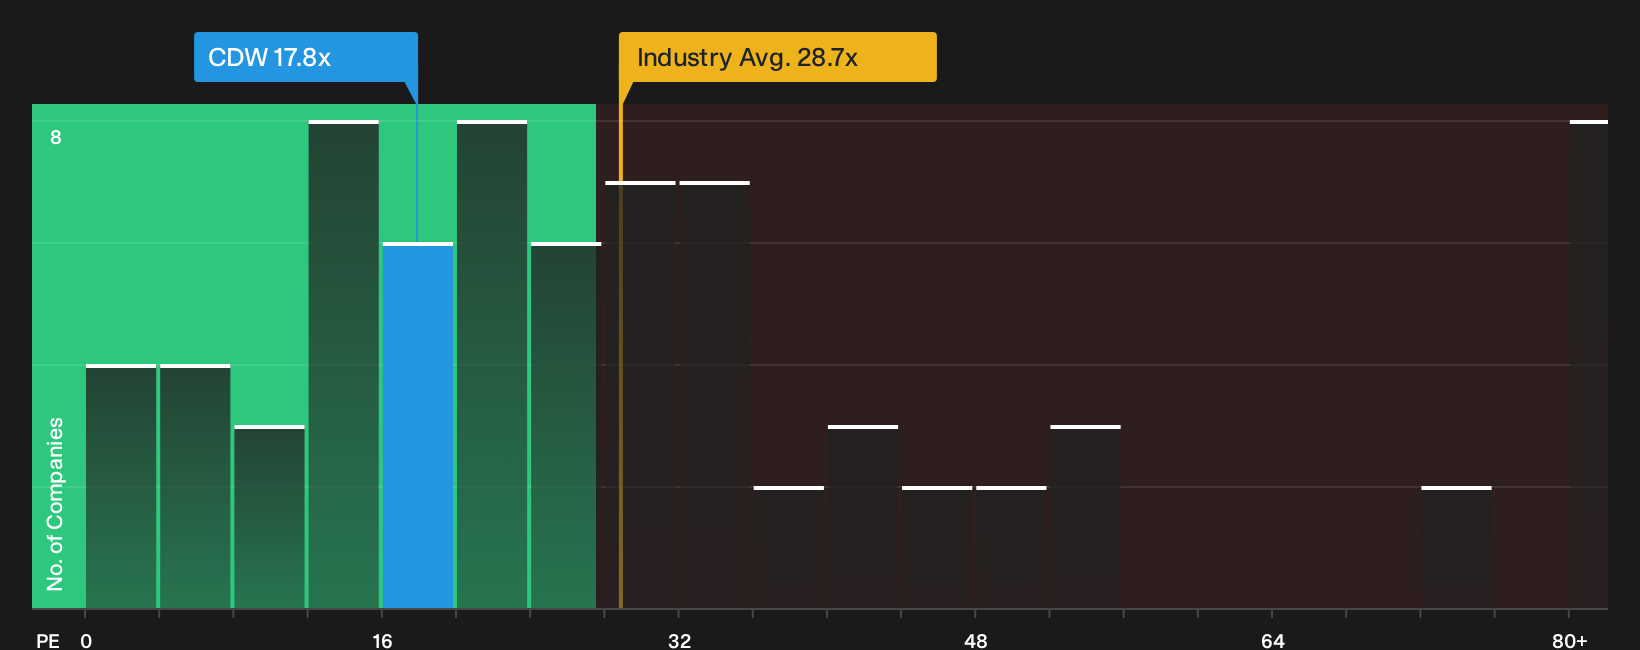
CDW trades on a P/E of 17.8x. That is cheaper than the broader US Electronic industry at 28.7x, yet richer than peers at 15.8x and below a fair ratio of 25.1x that the market could move toward over time. Is that a margin of safety or a signal that expectations still need a reset?
For a closer read on what the earnings-based view implies about valuation risk, and how it lines up against other tools investors use, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CDW so far, or just a complicated set of trade offs that need fresh eyes. Act quickly, review the full picture, and pressure test the upside and downside using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CDW?
If you stop with CDW, you risk missing other opportunities that fit your goals, so put a small block of time aside to scan fresh ideas now.
- Target higher quality at sensible prices by reviewing the 36 high quality undervalued stocks that combine solid fundamentals with attractive valuation metrics.
- Strengthen your income toolkit by checking the 5 dividend fortresses that focus on companies offering substantial yield alongside resilient business profiles.
- Prioritize resilience by running through the 29 resilient stocks with low risk scores tailored to highlight businesses with more durable balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com