
Sun Life Financial And 2 Canadian Dividend Stocks To Watch
High oil prices have pushed up energy bills and squeezed household budgets, so regular cash payouts from solid Canadian dividend payers can feel especially valuable. A yield above 3% that is backed by well covered, stable and growing dividends can help smooth those bumps. This article walks through three higher yielding Canadian stocks from our income screen and explains why each may deserve a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding businesses with well covered, stable and growing dividends. However, if you want the standouts, these 3 dividend aristocrats stocks are the most outstanding.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial is a global insurer and asset manager that provides life and health coverage plus investment and retirement solutions.
Operations: Sun Life Financial generates revenue mainly in Canada at CA$15.7b, the U.S. at CA$13.0b, Asia at CA$2.6b and SLAM at CA$7.7b.
Market Cap: CA$63.0b
Sun Life Financial fits the Dividend Powerhouses theme because its 3%+ yield is supported by recurring profits from insurance and fee based asset management, not just one cyclical line of business.
"Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth."
The real swing factor is how one pressure on the wider fee and underwriting mix ultimately feeds through to earnings resilience.
That resilience question is exactly what the full narrative for Sun Life Financial unpacks, separating steady insurance cash flows from fee income swings and explaining where that could leave dividend capacity over time.

Magna International (TSX:MG)
Overview: Magna International designs, engineers and builds high volume automotive components and complete vehicles for global carmakers, generating cash flows that support its 3%+ dividend.
Market Cap: CA$23.6b
For income investors, Magna International offers something different to banks or pipelines, since its manufacturing footprint and content per vehicle help tie a recurring dividend stream to everyday car production rather than purely financial assets.
"Magna International is continuing its operational excellence and factory of the future programs, with management pointing to roughly 200 bps of EBIT margin improvement from 2023 through the 2026 outlook and a target of 35 to 40 bps of annual margin expansion, which supports expectations for further progress in net margins and earnings."
The real hinge for dividend strength is whether that efficiency push fully offsets one unresolved pressure within global vehicle production plans.
If that margin story is what matters most, read the full narrative for Magna International to see how Magna International’s efficiency drive could reshape cash generation and dividend headroom.
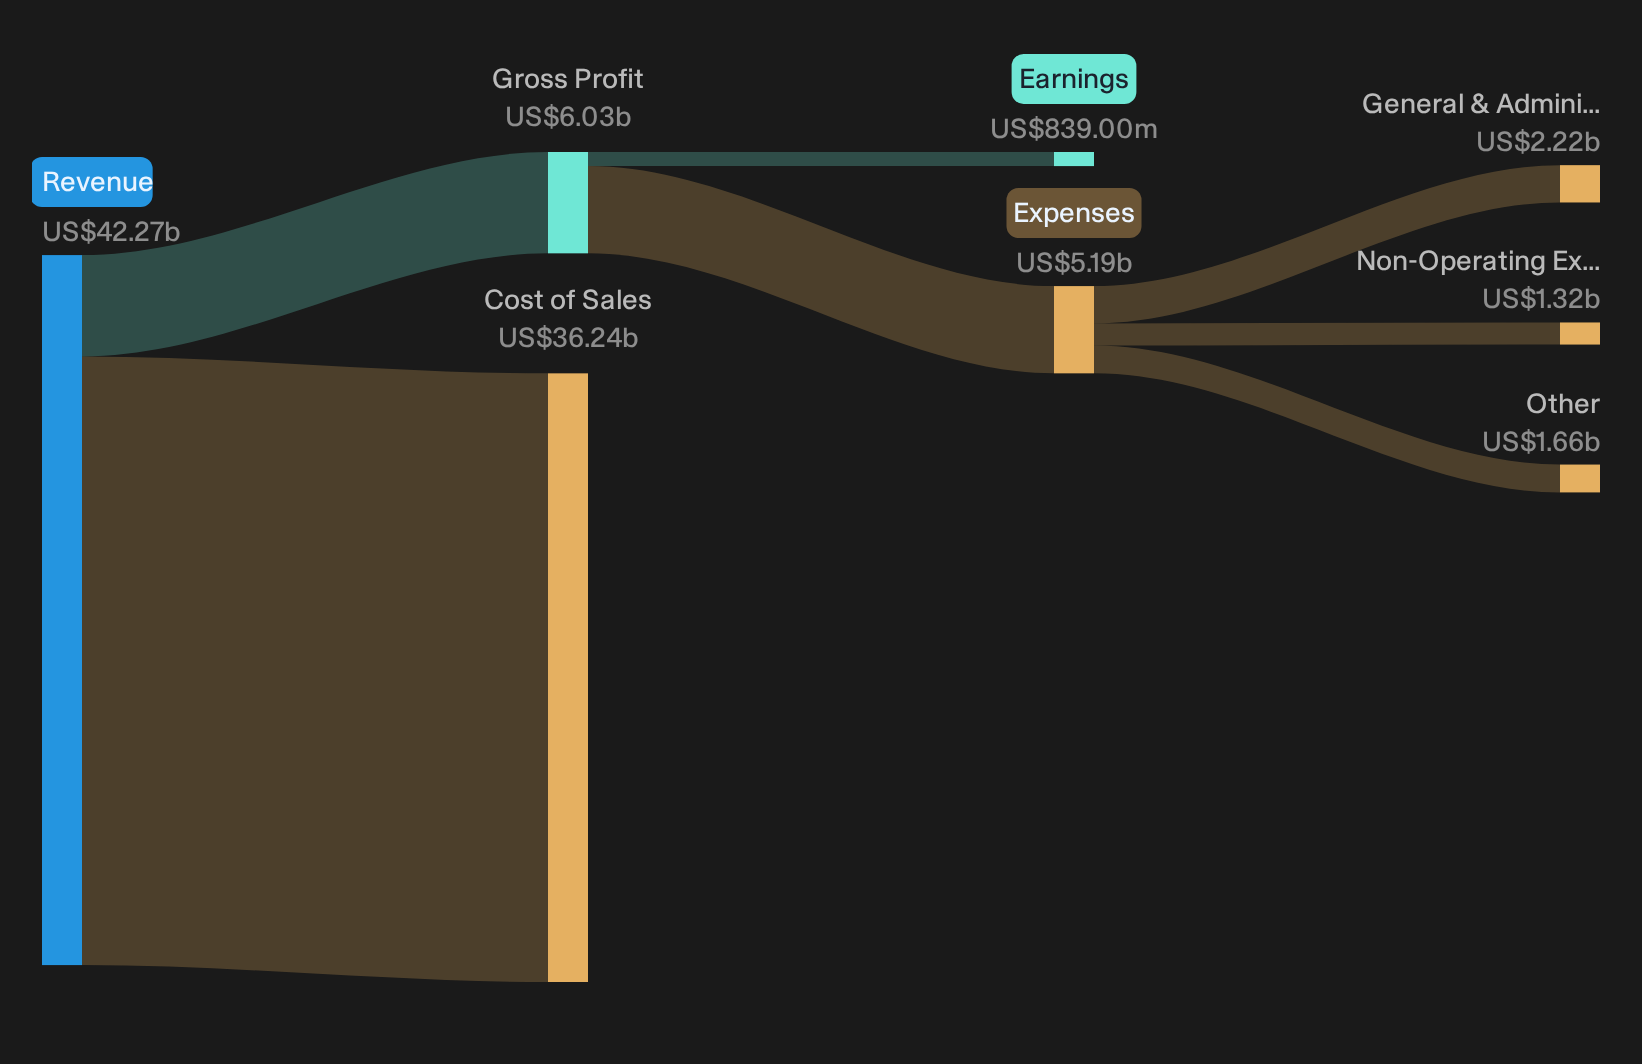
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a diversified North American and international bank whose Canadian and International Banking divisions anchor its 3%+ dividend theme fit through steady fee and interest income from everyday retail and commercial customers.
Operations: Bank of Nova Scotia generates most of its CA$37.1b revenue from Canadian Banking at CA$11.9b and International Banking at CA$9.6b, with additional contributions from Global Wealth Management and Global Banking and Markets.
Market Cap: CA$159.5b
Bank of Nova Scotia matters for this Dividend Powerhouses screen because everyday banking relationships across Canada and key international markets help keep cash flowing to support a consistent payout above 3%.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver, with International Banking revenue and loan growth in these regions and ROE above 16%. This points to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
The real test is whether one quiet shift in how risk and capital are managed ultimately decides how much headroom that dividend really has.
That quiet shift is exactly what the full narrative for Bank of Nova Scotia unpacks, showing how Bank of Nova Scotia’s capital decisions could be quietly reshaping dividend flexibility and long term earnings power.

Seeking Fresh Alternatives For Your Income?
Markets move fast and potential new income ideas may not stay unnoticed for long. Scan for fresh momentum, identify what is still under the radar for now, and consider your next steps promptly.
- Focus on higher-yield candidates with potential staying power by checking the curated 3 dividend fortresses before those payouts are widely reflected in prices.
- Follow developing infrastructure themes by reviewing the hand picked 42 power grid technology and infrastructure stocks while the grid upgrade story is still evolving.
- Explore future-oriented mining exposure by reviewing the focused 33 best rare earth metal stocks before critical metals ideas become more widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com