
ConocoPhillips (COP) Stock Looks About Right On Its 141% Run
ConocoPhillips has been on a long run, and with the stock recently around US$154 the real question for investors is how much of its earnings story is already reflected in that price.
- Over the past 5 years, ConocoPhillips has delivered a total return of 140.8%, which raises the stakes for judging whether the current valuation is still grounded in its earnings power.
- The upcoming first earnings release under new CEO Andy O'Brien can shape market expectations for future profitability and capital allocation, which feeds directly into how investors frame the stock's earnings base and potential durability.
- Your read on ConocoPhillips is one view; the desks covering it have another. See what analysts think ConocoPhillips's shares could be worth.
The stock's next move may depend on whether today's share price lines up with the earnings that ConocoPhillips is generating right now and is expected to produce in the years ahead.
For context on ConocoPhillips and the wider earnings story in energy, it can help to compare it with other producers using 34 elite gold producer stocks
Does ConocoPhillips Look Fairly Valued on Earnings?
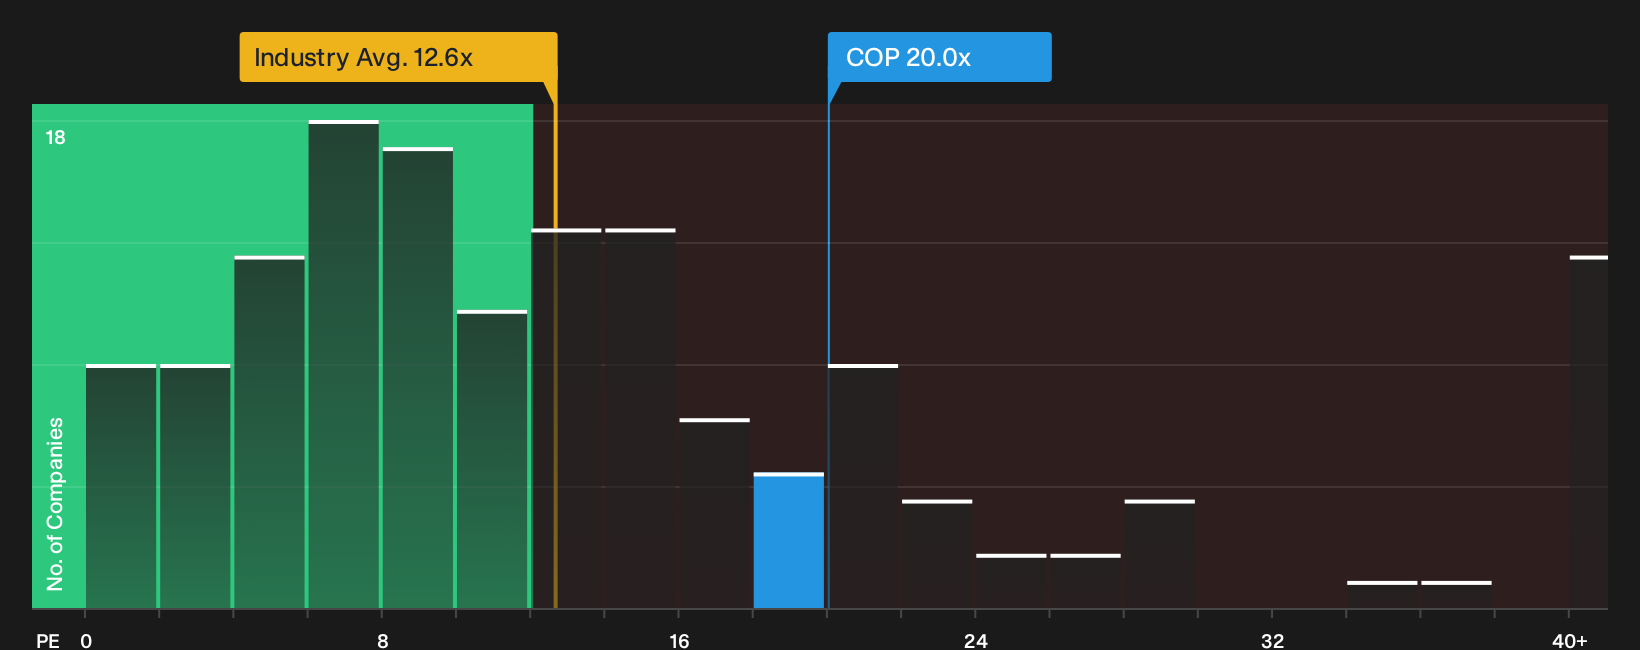
The P/E ratio is a useful yardstick for ConocoPhillips because earnings remain a core yardstick for how investors frame upstream producers. At roughly 20.0x earnings, the stock trades close to the level implied by a tailored fair multiple that already factors in its sector, scale and risk profile. Compared with the broader Oil and Gas industry on about 12.6x, ConocoPhillips carries a clear premium, but against a peer group closer to 20.7x it looks more in line with other large producers that investors view as higher quality or lower risk within the space.
Recent excitement around ConocoPhillips heading into the first quarterly report under new CEO Andy O'Brien means the current multiple already bakes in a fair amount of optimism about the earnings base. That leaves the P/E pointing to a valuation that is neither clearly cheap nor obviously stretched versus a calibrated benchmark. The key question for you is whether the upcoming results and capital allocation signals justify paying roughly this level for each dollar of profit today. Explore the numbers behind ConocoPhillips's P/E valuation.
The ConocoPhillips Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ConocoPhillips pick up where the P/E discussion leaves off. Narratives spell out which combinations of future growth, margins and earnings would need to occur for ConocoPhillips' valuation to move meaningfully higher or lower than it is today. Each narrative anchors a fair value estimate to a particular mix of possible catalysts and risks so you can track over time which version of the story is actually unfolding on the Community page.
Community views on ConocoPhillips are split between those who see more upside baked into long term cash flow plans and those who think expectations already look full.
Bull case: 14% undervalued
"The company describes a multiyear improvement in free cash flow that is already underway, targeting a total inflection of US$7b by 2029..."
Discover why this Narrative puts ConocoPhillips at 14% undervalued.
Bear case: roughly fairly valued
"The company's long term growth strategy is still heavily reliant on large, capital intensive projects such as Willow in Alaska and LNG start ups..."
Explore why this Narrative puts ConocoPhillips at roughly fairly valued.
One more angle on ConocoPhillips that could reshape the story
Share price and earnings only tell part of the story for ConocoPhillips, because the people setting priorities and how they are rewarded can tilt risk, discipline and resilience in very different directions. See who runs ConocoPhillips and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com