
Is Record Fundraising Altering The Investment Case For Blue Owl Capital (OWL)?
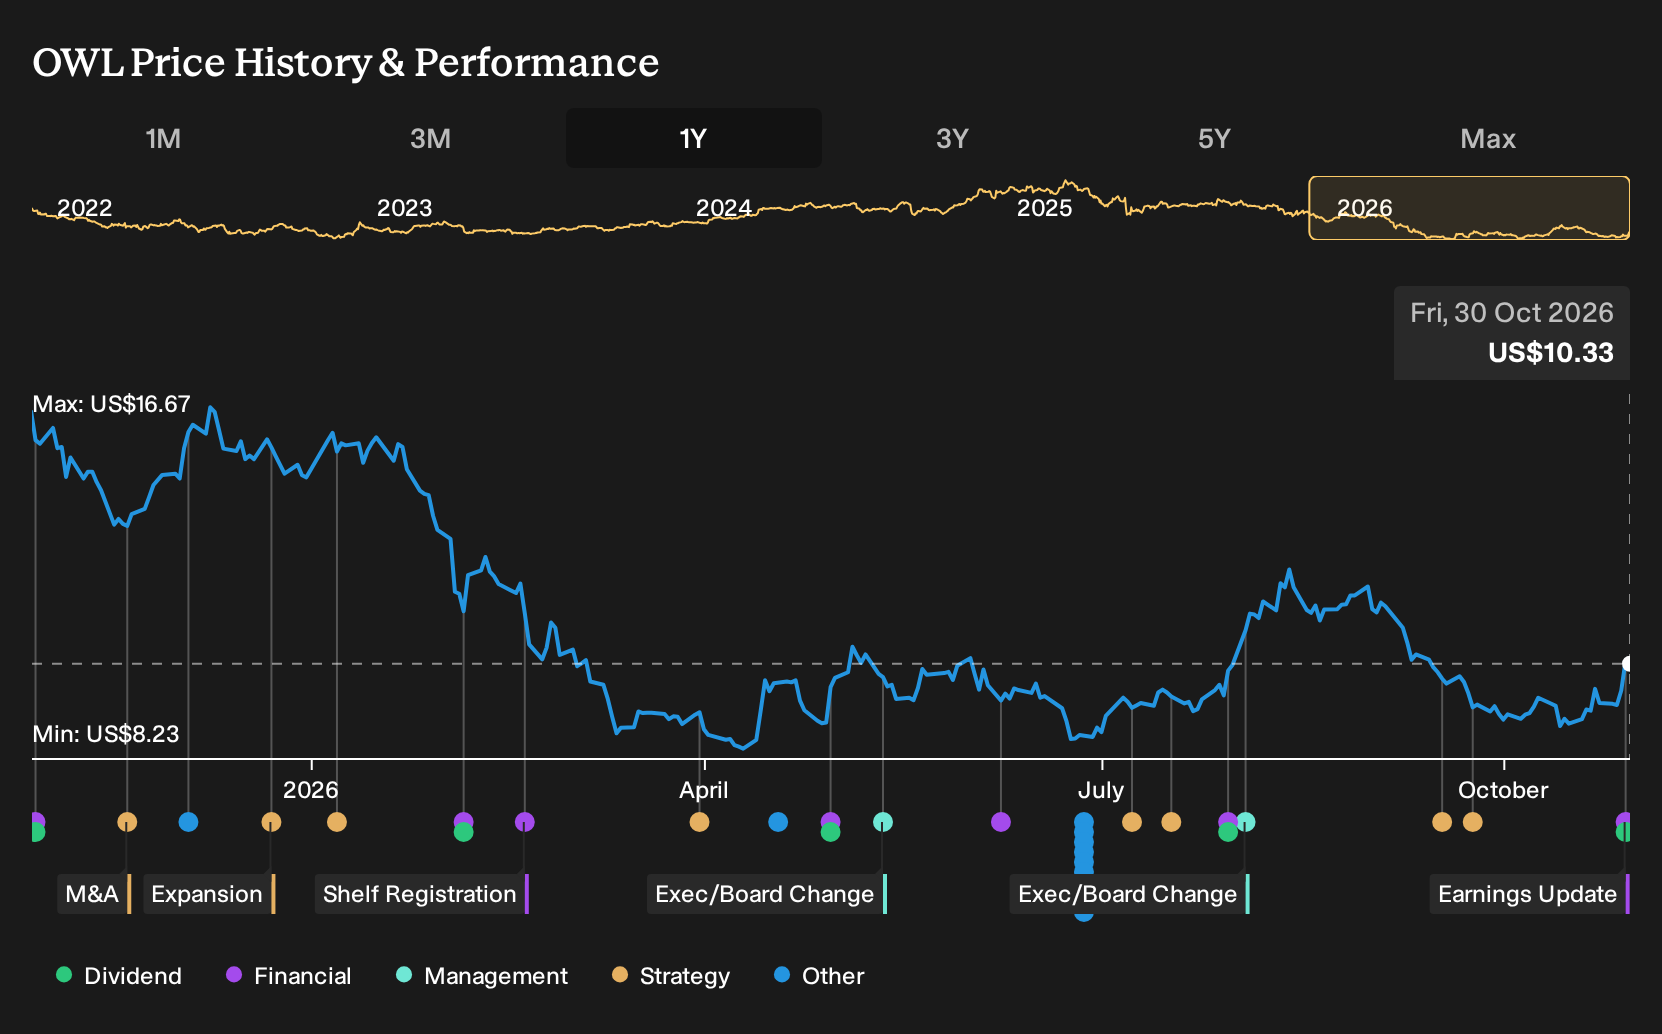
- Blue Owl Capital reported third quarter 2026 revenue of US$806.53 million and net income of US$19.96 million, with basic and diluted earnings per share from continuing operations of US$0.03, and a quarterly dividend of US$0.23 per Class A share declared for payment on November 23, 2026.
- Record institutional fundraising of US$12.6 billion in the quarter and nearly US$50 billion over twelve months highlighted broad demand for Blue Owl Capital’s multi product platform and reinforced the role of permanent capital vehicles and private credit in supporting fee related earnings.
- We will now look at how Blue Owl Capital's record institutional fundraising reshapes the investment narrative built around its fee-based platform.
Compare Blue Owl Capital's fee based model with other asset managers riding similar fundraising momentum by scanning our curated list of 36 high quality undervalued stocks.
Blue Owl Capital Investment Narrative Recap
To own Blue Owl Capital, you need to buy into a simple idea. The fee based platform keeps attracting long term capital fast enough to more than offset any pockets of redemption pressure in private credit and timing issues in digital infrastructure. The third quarter update, with higher revenue and net income plus record fundraising, points to a business still growing fee potential rather than stalling it.
The near term swing factor remains how quickly those committed assets turn into fee paying AUM, while redemption caps and legal costs stay contained. The biggest risk sits in prolonged redemption stress or a negative outcome from the BDC liquidity lawsuit, which could dent margins and fundraising appetite at the same time.
The most relevant datapoint for this story is the reaffirmed US$0.23 quarterly dividend for November 2026. For a stock flagged as having a dividend that is not well covered by earnings or free cash flow, that payout level keeps the funding of distributions firmly in focus. Investors are being asked to trust future fee growth and earnings to close that gap.
That dividend decision also ties directly into the main catalyst. If record institutional fundraising and expanding permanent capital vehicles translate into stronger fee related earnings, coverage could improve and support the current distribution without stretching the balance sheet. If private credit redemptions, project delays, or legal outcomes eat into profitability instead, the dividend could shift from attraction to pressure point.
Blue Owl Capital's current earnings of US$80.9 million sit against analyst projections of US$847.0 million by 2029, which implies roughly a 10x earnings increase. This ties into a revenue path that targets US$3.5b and assumes 5.8% yearly revenue growth over that same forecast period.
Uncover why Blue Owl Capital's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle puts the spotlight on digital infrastructure execution risk. Before this Blue Owl Capital update, the most cautious analysts were working off slower revenue growth of about 3.9% a year and earnings of roughly US$1.0b by 2029. That camp already viewed the stock as fully valued, so this quarter could force a rethink in either direction.
Explore 7 other Blue Owl Capital fair value estimates, including one that suggests as much as 85% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Blue Owl Capital research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Blue Owl Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Blue Owl Capital's overall financial health at a glance.
Looking for more investment ideas beyond Blue Owl Capital?
Once you have formed a view on Blue Owl Capital, it can help to widen the lens and compare its risk and income profile with other listed businesses using the Simply Wall St Screener.
- If capital preservation is front of mind, review 29 resilient stocks with low risk scores that combine steadier risk scores with resilient fundamentals.
- For investors who care about getting paid while they wait, scan 5 dividend fortresses that focus on higher yielding payouts.
- If you are hunting for under followed stories with room for the thesis to spread, check out 19 high quality undiscovered gems that pair quality metrics with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com