
Surprised By Pague Menos's Slide? What Investors Overlooked
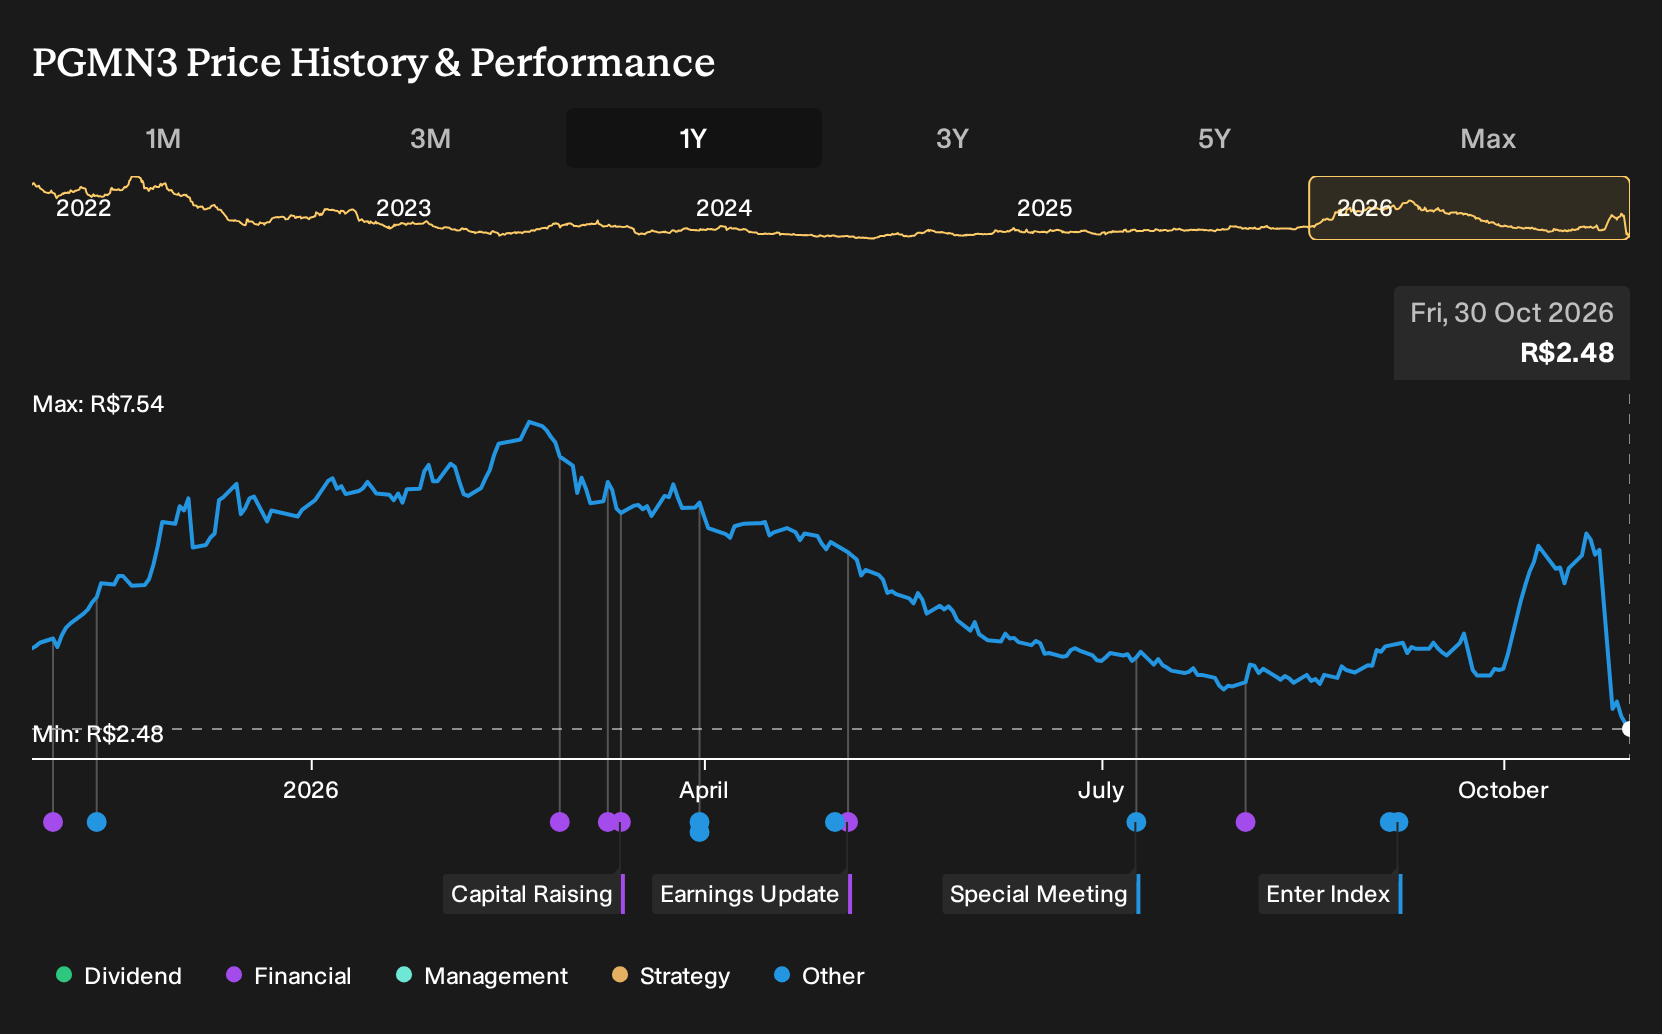
If you backed Empreendimentos Pague Menos for its pharmacy rollout and digital push, the share price outcome has been harsh. Investors who held Empreendimentos Pague Menos over the past year are down 35.0%, including dividends. If that decision date in late October 2025 was yours, the obvious puzzle is this: With revenue and net income both higher by Q2 2026 and net margin at 1.8%, which of the original assumptions proved too optimistic?
Empreendimentos Pague Menos has already moved. See which of 193 high quality undervalued stocks still trade below our estimates.
The Argument Investors Faced On Empreendimentos Pague Menos
The shares cost R$3.84 at the start of the period, and anyone looking at Empreendimentos Pague Menos had to choose between two very different stories about where value might sit.
The upbeat view pointed to a Fair Value of R$4.8, a notional upside level if revenue grew 12.1% with profit margin at 1.6% and the future P/E reached 21.2x over about three years.
The more cautious camp worked off a Fair Value of R$3.4 and focused on rising digital health competition as a threat to store volumes and to any benefits from further physical expansion.
What The Results Changed For Empreendimentos Pague Menos
The clearest update came from Empreendimentos Pague Menos reporting Q2 2026 revenue of R$3,987.177m and net income of R$71.109m, ahead of Q2 2025 levels, with net margin at 1.8%. That earnings profile sits closer to the optimistic case on profitability. However, the cautious view on competitive pressure remains untested by these figures alone, so the period cut both ways.
The main lesson is about margins versus stories. When a thesis hinges on better profitability, track net margin and absolute earnings in each report and test whether they move toward the original target or stall.
What Empreendimentos Pague Menos Buyers Are Really Paying For Now
Empreendimentos Pague Menos trades at R$2.48 today after a share price decline of 35.0% over the past year. The selected Narrative sees a Fair Value above that level and ties the gap to how well chronic care, GLP-1 products, and digital channels reshape the business mix.
For anyone paying today’s price, the key consideration is whether productivity and margin programs, from procurement to logistics and store telemetry, actually deliver the efficiency the Narrative incorporates into its higher figure.
"Expanding participation of high frequency chronic care patients through the Continuous Care Client base, which now accounts for roughly 72% of Empreendimentos Pague Menos revenue and has shown growth in both customers and average ticket, can keep lifting same store sales and support earnings quality."
One Narrative disagrees with today's price. → See where this Narrative says Empreendimentos Pague Menos should trade
One Step Beyond Pague Menos
Empreendimentos Pague Menos is pushing deeper into chronic care, loyalty programs and store telemetry. Your watchlist does not need to stop there.
Pharmacies seeking higher quality earnings often look for steadier shopper traffic and better basket economics. Another retailer is working on similar goals from a broader general merchandise base.
It is investing in refreshed stores, priority categories and sharper price perception. Digital traffic is influenced by AI tools that shape search, wish lists and conversion.
These moves address challenges similar to those facing Pague Menos. The unknown is how a wider retail format might alter long term mix and operating efficiency.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 23% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com