
Air China (SEHK:753) Swings To A Loss, Is The Valuation Discount Justified?
Why Air China’s Latest Earnings Matter For Shareholders
Air China (SEHK:753) just released nine month results to September 30, 2026, showing higher reported sales in renminbi terms but a swing from profit last year to a loss this period.
The airline recorded CNY 140,962.68 million in revenue compared with CNY 129,826.18 million in the same stretch of 2025, while net income moved from CNY 1,869.84 million in profit to a CNY 2,015.29 million loss.
Basic and diluted earnings per share from continuing operations also flipped, with both measures shifting from CNY 0.11 in earnings a year ago to a CNY 0.11 loss per share in the latest filing.
That swing into loss has come against a weak share price backdrop, with Air China’s share price down 49.02% year to date and the 1 year total shareholder return declining 38.97%, even though the stock has rebounded 3.72% over the last day and 4.92% across the past week.
Scan beyond Air China’s swing into loss and see how other airlines and transport stocks with sturdier fundamentals stack up in the list of solid balance sheet and fundamentals (197 results).
Air China’s shares have fallen sharply while reported sales rose and earnings slipped into a loss. Does that slide mostly reflect weaker fundamentals, or has sentiment swung further than the business justifies as you weigh valuation next?
Preferred Price-to-Sales Multiple of 0.3x: Is It Justified For Air China?
On valuation terms, Air China trades on a P/S of 0.3x, which sits well below several reference points and reflects the current HK$3.63 share price against its revenue base.
The P/S ratio compares the market value of the equity with the annual sales that the business generates. For an airline like Air China, where earnings can be volatile and currently sit in loss territory, investors often look at this revenue based measure to gauge how much they are paying for each unit of top line rather than for current profit.
That 0.3x multiple is far lower than the estimated fair P/S level of 0.7x that the SWS model suggests the market could gravitate toward over time. The same 0.3x ratio also screens well against reference groups, sitting below the Asian Airlines industry average of 0.6x and sharply under the 2.2x peer average highlighted in the checks. This signals that the market price is placing a heavy discount on Air China’s revenue compared with similar businesses.
Explore the SWS fair ratio for Air China.
Result: Price-to-sales of 0.3x (UNDERVALUED)
Still, the recent loss, multi year total returns that remain weak, and a reported decline in net income resulting in a loss of CNY 5,655.52 million could keep pressure on Air China.
Find out about the key risks to this Air China narrative.
Another View Of Air China’s Valuation
The DCF work presents a very different picture. Air China at HK$3.63 is identified as trading well below an estimated future cash flow value of HK$21.99 using the SWS DCF model. This suggests a substantial valuation gap that long term investors will need to assess carefully.
That kind of spread can indicate potential opportunity or may simply reflect the underlying business risks and execution challenges between today’s losses and the cash flows in the model. Which side of that trade off do you think the market is currently pricing in?
Look into how the SWS DCF model arrives at its fair value.
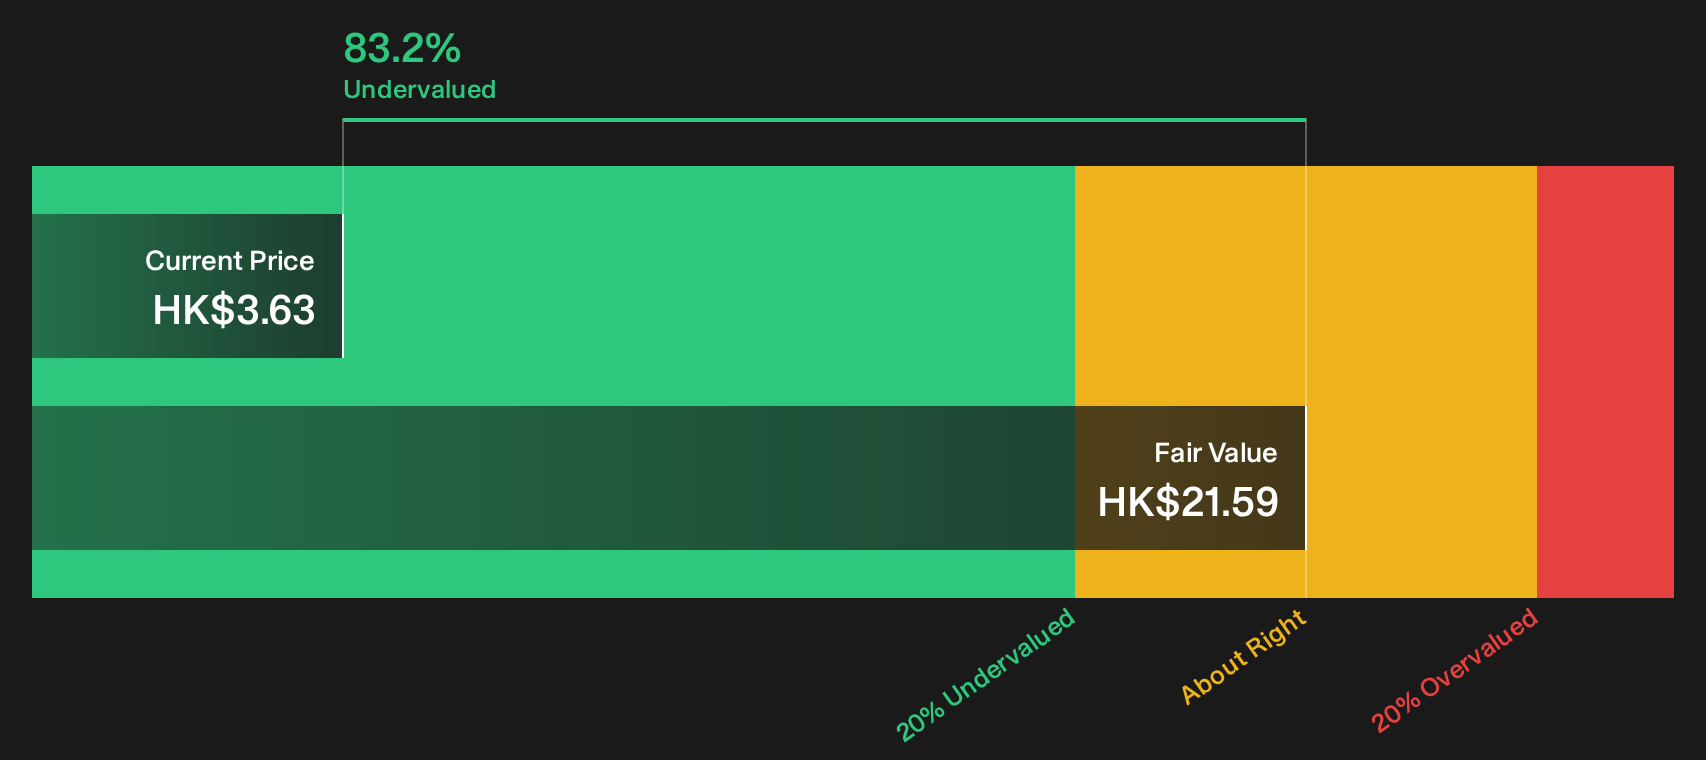
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Air China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Air China can feel confusing, so move quickly from headlines to hard numbers and shape your own stance by weighing the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Air China?
If you stop with Air China, you only see one angle. Broaden your watchlist with other ideas that match your risk, income, and value preferences.
- Target potential value opportunities before the crowd by scanning the 194 high quality undervalued stocks that combine quality fundamentals with discounted prices.
- Lock in potential income streams by reviewing the 222 dividend fortresses that focus on higher yielding payouts with supporting balance sheets.
- Dial down risk while staying invested by checking the 218 resilient stocks with low risk scores that highlight companies with more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com