
Does Raised Guidance Change The Bull Case For Tenable Stock (TENB)?
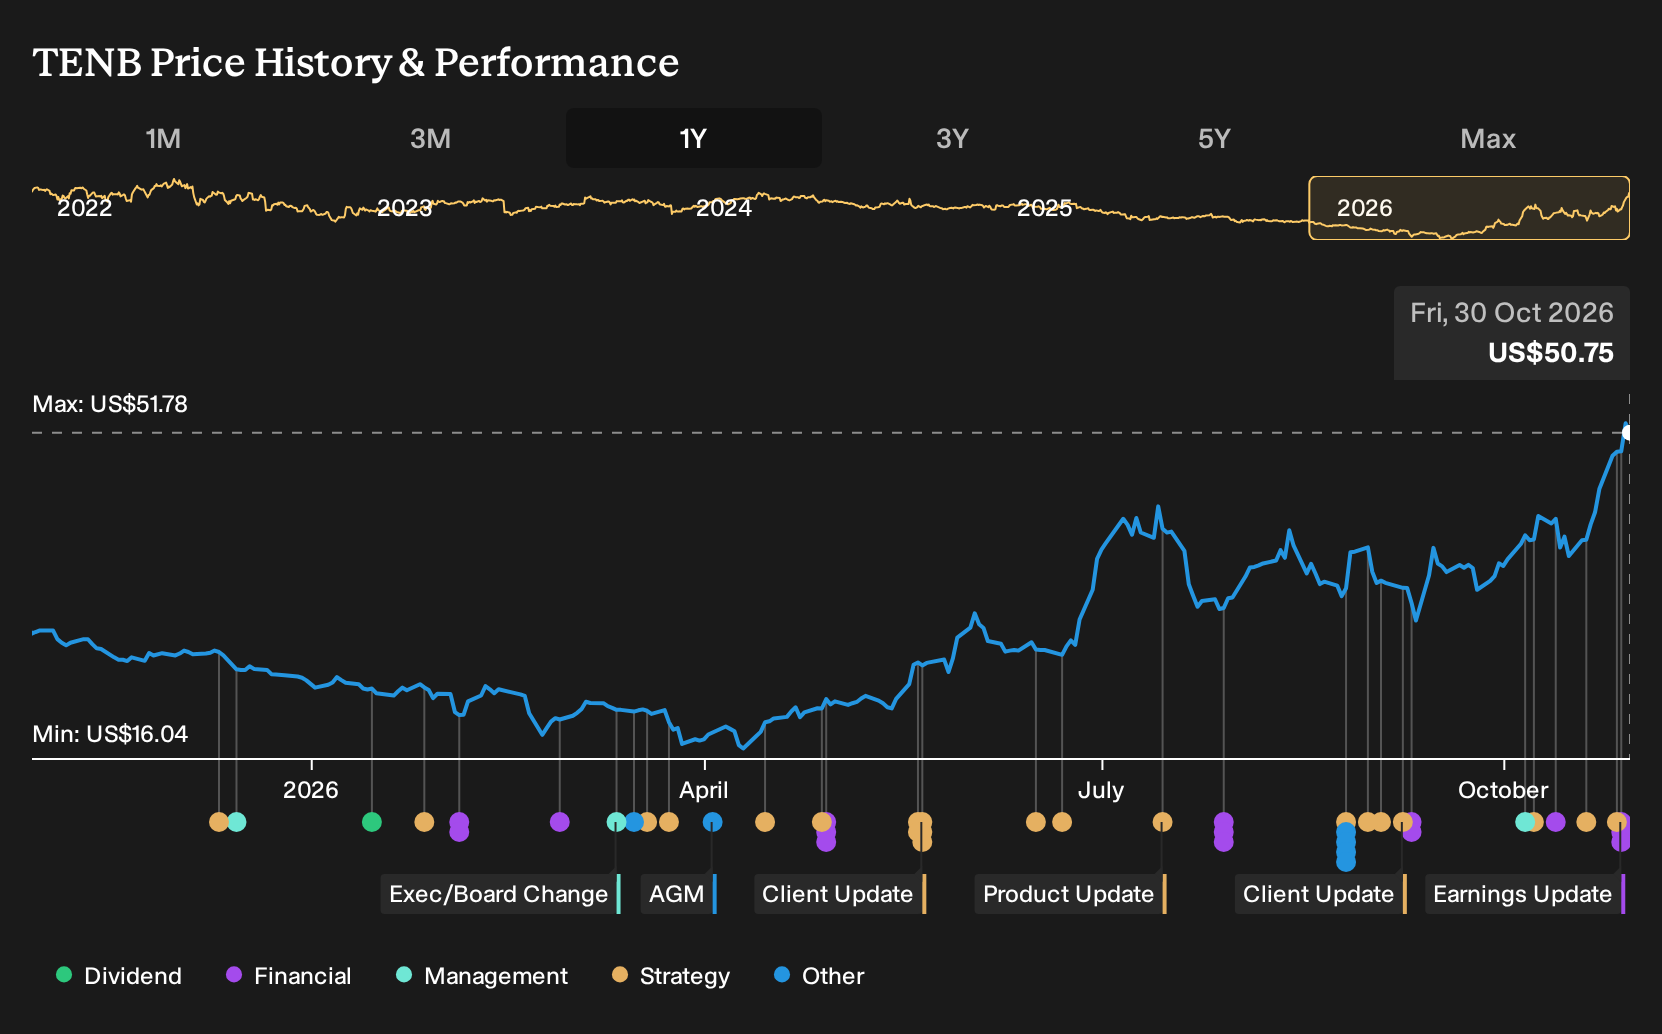
- Tenable Holdings reported third quarter 2026 revenue of US$276.39 million and net income of US$11.3 million, and lifted full year guidance alongside new AI-focused product and client announcements.
- Atos’ decision to use Tenable One for its global Continuous Threat Exposure Management service highlights how Tenable’s AI driven platform is gaining traction in large, complex security environments.
- We will now look at how Tenable Holdings' raised full year guidance could reshape the broader investment narrative around the business.
Scan how Tenable Holdings’ AI driven security story compares with other potential breakouts in 39 AI small caps across the market right now.
Tenable Holdings Investment Narrative Recap
For a shareholder in Tenable Holdings, the core belief is that exposure management and AI driven security can support durable demand, even as competition in platform security heats up. The latest quarter delivered US$276.39 million in sales and US$11.3 million in net income, and management lifted full year revenue and earnings guidance. That update keeps the near term story centered on execution rather than repair.
The key near term catalyst is continued traction for Tenable One and AI exposure products with large enterprises and public sector customers. The biggest risk is that higher spending on AI, integrations, and acquisitions outpaces monetization, especially given high debt, negative shareholders equity, and the potential for slower expansion if renewals or upsells soften.
The raised full year outlook sits alongside Tenable OPEN for AI, which brings a broad partner ecosystem directly into Tenable’s exposure data. For you as an investor, that matters because it speaks to how embedded Tenable can become in day to day security workflows rather than remaining a single point tool.
If partners such as SentinelOne, Snyk, Corelight, and BeyondTrust see sustained adoption of these AI workflows, that could reinforce the Tenable One platform as a central decision layer for clients. Execution risk is real, since deeper integrations and cross vendor AI use cases are complex to manage, but strong Q3 profitability and updated guidance show that management is currently balancing investment and earnings discipline.
Tenable Holdings' current assumptions point to revenue reaching US$1.3b and earnings of US$68.4 million by 2029, based on analysts' expectations. That outlook implies 6.5% yearly revenue growth and an earnings increase of about 9x from US$6.7 million today.
Uncover why Tenable Holdings' fair value indicates a 28% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate narrative zeroes in on profitability risk. The most cautious analysts, working off forecasts made before this AI and Atos news, were only penciling in about US$1.2b of revenue and US$40.8 million of earnings by 2029. That is far below the consensus path, and it shows how sharply views on Tenable Holdings can diverge. You can use these gaps as a prompt to explore multiple scenarios, then decide which assumptions feel more realistic to you.
Explore 2 other Tenable Holdings fair value estimates, including one that suggests as much as 28% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tenable Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tenable Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tenable Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Tenable Holdings?
Once you have a view on Tenable Holdings, it can help to broaden your watchlist with companies that fit different risk, quality, and income profiles using the Simply Wall St Screener.
- If you want to focus on quality at a discount, start with a curated pool of 36 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them yet.
- For investors who care most about resilience, filter for stability first and build out from a universe of 29 resilient stocks with low risk scores to see which businesses align with your risk tolerance.
- If balance sheet strength is your anchor, begin with a list of solid balance sheet and fundamentals (24 results) so you are only comparing companies that already pass a basic financial sturdiness check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com