
TTM Technologies Stock In Focus After Strong Earnings And Upbeat Outlook
- TTM Technologies reported third quarter 2026 sales of US$1,203.86 million and net income of US$84.8 million, alongside a new US$100 million share repurchase authorization running through October 27, 2027.
- Stronger earnings per share from continuing operations in both basic and diluted terms, together with ongoing buybacks, highlight how TTM Technologies is pairing operational momentum with active capital return.
- We will now look at how TTM Technologies' investment narrative could be affected by this earnings strength and fresh buyback plan.
Scan how TTM Technologies’ fresh buyback sits alongside other potential opportunities by reviewing our hand picked list of 36 high quality undervalued stocks in similar cash generative territory.
TTM Technologies Investment Narrative Recap
To own TTM Technologies, you need to be comfortable with a business leaning into AI data center, networking and defense demand while carrying higher debt and heavy capex. The recent Q3 2026 results, with year to date sales of US$3,053.89 million and net income of US$217.84 million, show the current plan supporting both revenue and earnings.
The short term swing factor is execution on that build out, especially filling new capacity and integrating Epiq Solutions without squeezing margins. The biggest risk is that demand or cash generation comes in softer than expected, which would leave TTM Technologies managing higher interest costs and a less flexible balance sheet.
The fresh US$100 million share repurchase authorization through October 27, 2027, coming right after completing a US$100 million program, is the announcement that ties closest to this earnings release. It indicates that TTM Technologies is willing to return capital even while funding an intensive expansion and acquisition agenda.
For you as a shareholder, the key question is whether buybacks compete with or complement that heavy investment cycle. If operational execution on AI focused facilities, defense programs and the Epiq integration remains on track, the new authorization can tighten the share count around those catalysts. If leverage or capex risk starts to rise, this plan may become less important than maintaining balance sheet flexibility.
TTM Technologies' current analyst narrative points to US$9.6b in revenue and US$1.4b in earnings by 2029. That profile is based on an assumed 35.9% yearly revenue growth rate and an earnings increase of about US$1.1b from US$268.5m today.
Uncover why TTM Technologies' fair value indicates a 124% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
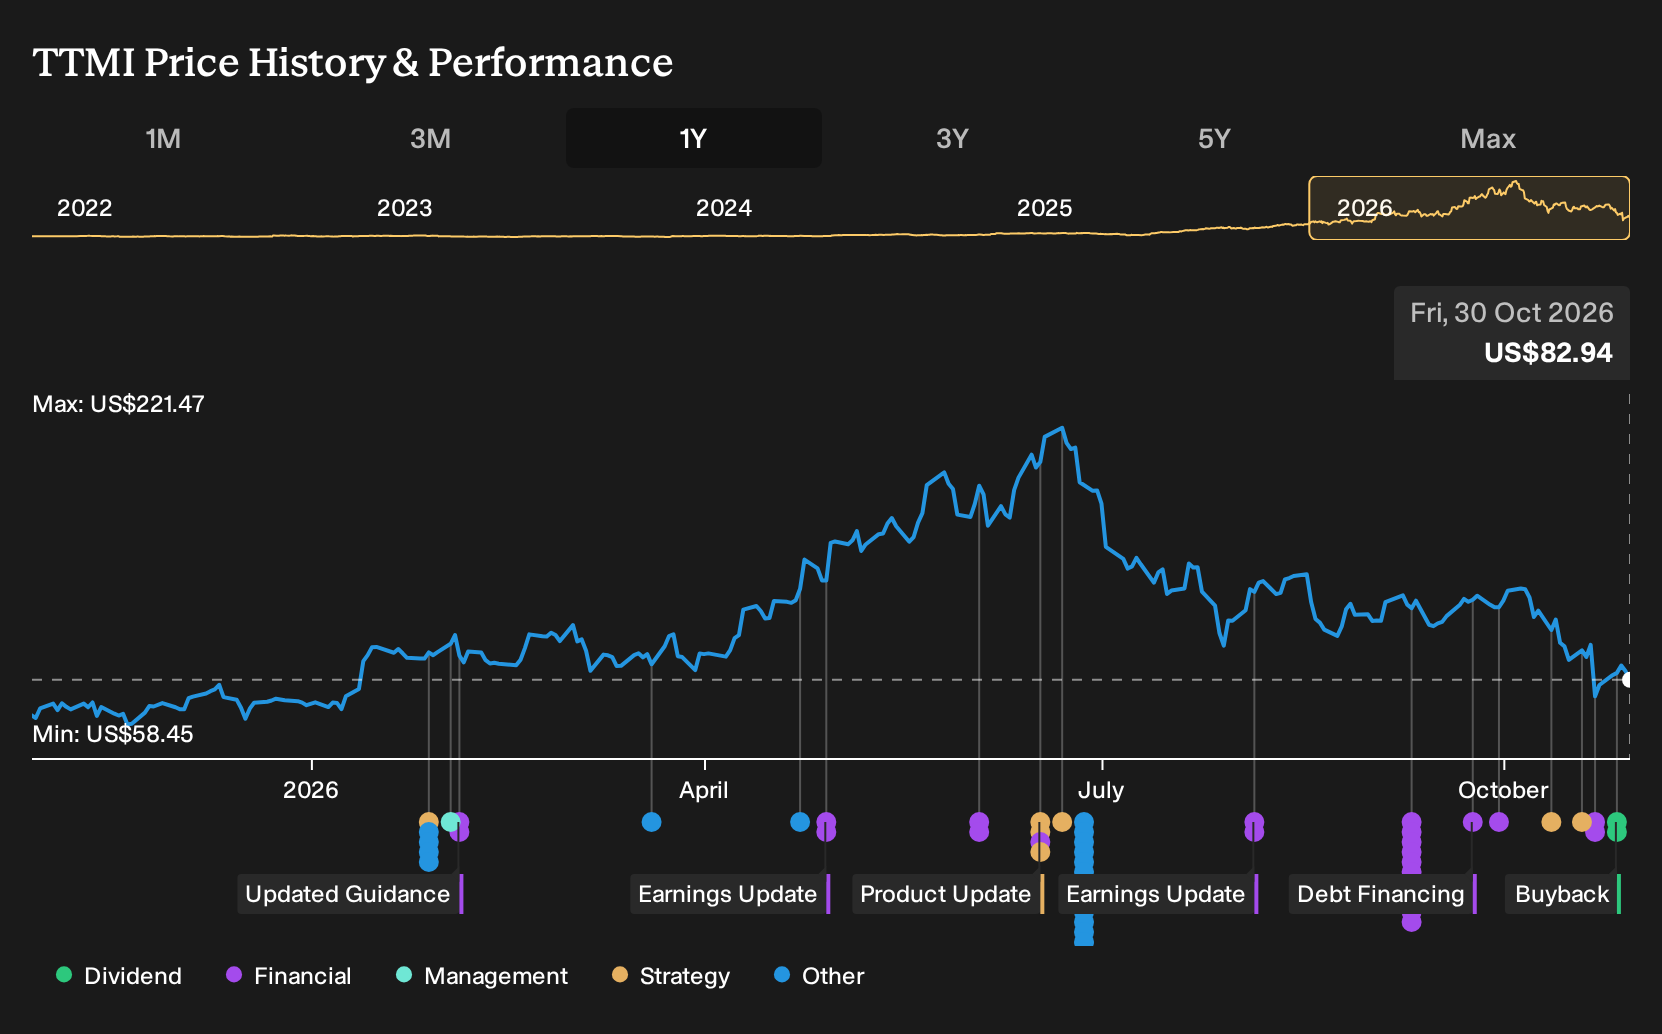
Exploring Other Perspectives
One alternate view puts more weight on concentration risk for TTM Technologies. The most cautious analysts were working off revenue assumptions of about US$9.1b and earnings near US$1.3b by 2029, which already sit below consensus. The fresh US$100 million buyback and recent Q3 numbers may shift those expectations, so explore both narratives before deciding.
Explore 4 other TTM Technologies fair value estimates, including one that suggests it could be worth just $150.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TTM Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TTM Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TTM Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TTM Technologies?
If this TTM Technologies story has sharpened your thinking, you can use that same lens across the wider market by scanning for other businesses that match your risk and return preferences through the Simply Wall St Screener.
- For readers who want potential mispricing combined with quality fundamentals, start with a curated set of 36 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and balance sheet strength sit at the top of your checklist, you can filter the market using our 29 resilient stocks with low risk scores to narrow down the field.
- Investors hunting for less crowded opportunities can comb through a hand picked pool of 19 high quality undiscovered gems that might not yet be on every watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com