
Banc of California (BANC) Stock May Be 8% Undervalued As Private Banking Launches
Banc of California has seen a mixed share price story, with a strong multi year swing capped by recent gains. That raises a straightforward question for investors about whether the current valuation lines up with the returns the bank earns on its capital. With the stock at US$18.23, the key issue is how that price stacks up against the profitability the business can generate on the capital it deploys into loans, securities and new initiatives.
- Over the past 5 years, Banc of California shares have declined 72.3%, which puts the focus squarely on whether the capital the bank invests today can earn enough to justify rebuilding long term shareholder value.
- Recent balance sheet repositioning and the launch of a private banking offering aimed at high net worth clients can influence future returns on capital by shifting the mix toward higher yielding assets and fee rich relationships.
- If you'd rather focus on book value, this one's for you. See why Banc of California's 1.0x P/B tells a different valuation story.
The stock's next move may depend on whether the returns Banc of California earns on its capital are strong enough, relative to the industry average, to make today's share price look sensible.
If you are weighing Banc of California against other capital efficient plays in the market, it can help to line it up beside 36 high quality undervalued stocks.
Does Banc of California Look Fairly Valued on Excess Returns?
The Excess Returns model looks at how profit on equity compares with the cost of that equity. For Banc of California, stable earnings are modeled at $1.56 per share against a book value base of $17.99 per share and a long run average return on equity of 7.67%. The estimated cost of equity is $1.59 per share, which means the bank is modeled to generate a small shortfall in excess returns of about $0.03 per share rather than a surplus.
Analysts expect book value to trend toward $20.40 per share over time, so the framework relies on gradual balance sheet growth rather than aggressive profit expansion to support the current $18.23 share price. The recent balance sheet repositioning and move into private banking, including the Q3 2026 launch targeting high net worth clients, helps explain why the market is willing to price Banc of California broadly in line with what these modeled returns on capital support. Find out what Banc of California could be worth using our Excess Returns estimate.
The Banc of California Narrative: What Would Justify Today's Price?
Narratives on Banc of California pick up where the valuation puzzle leaves off by explaining which paths for future growth, margins and earnings would need to hold for the shares to be worth meaningfully more or materially less than today's level on Simply Wall St's Community page. Instead of a single output from a ratio or model, they describe the future those numbers rely on so you can watch how management decisions and reported results line up against that picture over time.
One of the top community narratives on Banc of California: 5% undervalued
"Some analysts with a negative view expect Banc of California to continue to face earnings pressure, pointing to the Q2 2026 net loss…"
Discover why this Narrative puts Banc of California at 5% undervalued.
One more Banc of California check that sits outside the valuation maths
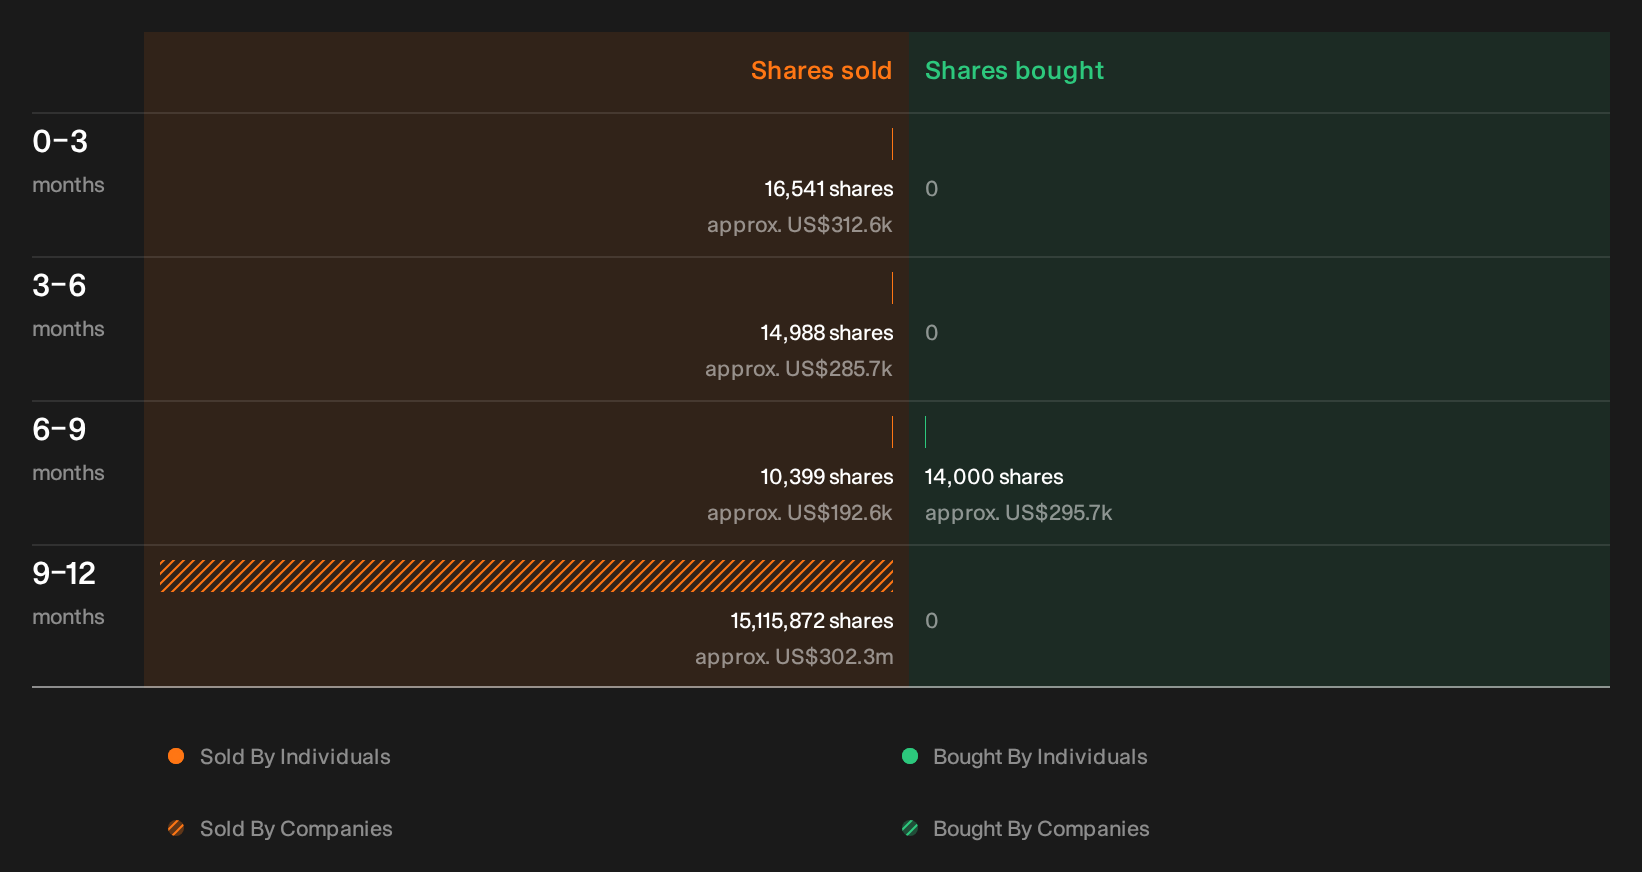
Price, returns on equity and book value only tell part of the story, because recent trades by Banc of California insiders can offer an extra clue about how decision makers act with their own holdings. See the recent insider selling flagged for Banc of California.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com