
Tencent Holdings (SEHK:700) Expands Payments And AI Ties, Is The Stock Cheap?
Tencent Holdings (SEHK:700) has just completed a multi currency note issuance under its global medium term note programme. This funding move puts fresh focus on the stock’s debt profile and capital allocation choices.
The new multi currency notes arrive at a time when Tencent Holdings’ share price has been under pressure, with the stock down 37.05% on a year to date share price basis and the 1 year total shareholder return also down 36.82%, even though the 3 year total shareholder return is positive at 29.14%.
Recent trading has been choppy. The 1 day share price return of 2.24% and 7 day gain of 1.50% sit against a 30 day share price decline of 6.89% and a 90 day slide of 19.57%. This points to fading momentum despite today’s HK$392.2 level.
Over the past few weeks, attention has also turned to other moves by Tencent Holdings. TenPay Global’s agreements with UnionPay International and Mastercard to broaden cross border remittances and payment options, together with Tencent Cloud’s partnership with OmniOps in Saudi Arabia, give investors fresh information to weigh against the softer share price trend and the company’s decision to issue long dated debt.
Scan beyond Tencent Holdings and see how other payment and AI infrastructure plays are setting up right now with the hand picked 54 AI infrastructure stocks.
The debt issue and Tencent Holdings’ payment and AI partnerships point in one direction, while the share price slide points in another. Is the market reacting to sentiment swings or to something more fundamental that should feed into valuation work next?
Most Popular Narrative: 6% Overvalued
The most followed Tencent Holdings narrative puts fair value at HK$370, slightly below the last close of HK$392.2, so the current price sits above that anchor and forces investors to ask what they are really paying for.
This is NOT:
“AI reduces costs → margins expand”
This IS:
“AI increases costs → hoping revenue grows enough to compensate”
🔥 This completely changes the DCF profile:
• FCF ↓ (short term)
• capex ↑
• margins ↓
• optionality ↑
See why 39 investors see Tencent Holdings as 6% overvalued.
Result: Fair Value of HK$370 (OVERVALUED)
Still, two issues could flip that 6% overvaluation story fast: the evolving China AI rulebook and any escalation of U.S. restrictions on Tencent Holdings.
Find out about the key risks to this Tencent Holdings narrative.
Another View: Tencent Holdings Through The Earnings Lens
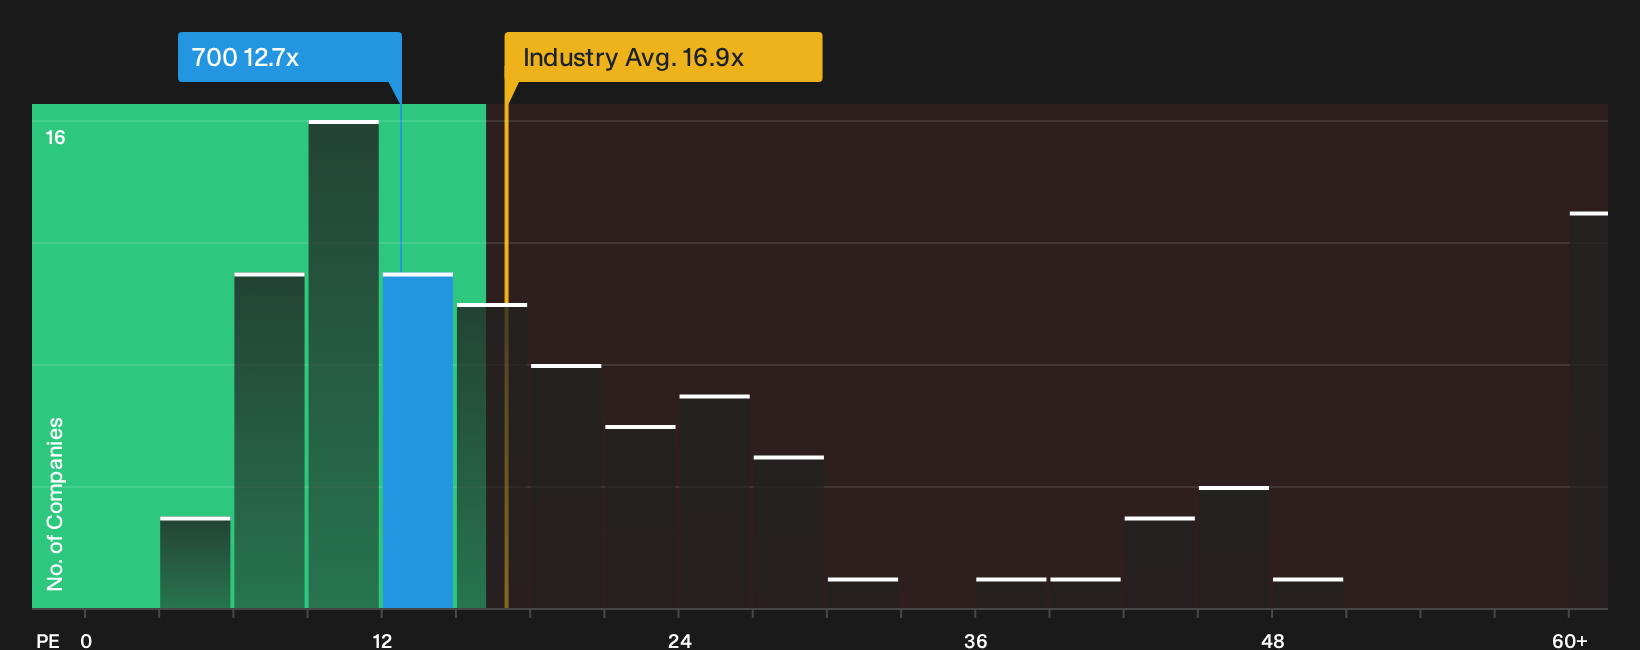
That 6% overvaluation narrative leans heavily on a HK$370 fair value, yet the earnings ratios tell a softer story. Tencent Holdings trades on a P/E of 12.7x, below both its own fair ratio of 14.3x and the Asian Interactive Media and Services sector at 16.9x. For investors, that kind of discount can either flag a valuation cushion or hint that the market still prices in extra risk.
The question is whether you see that gap as a margin of safety or as a warning sign that something has not yet been fully reflected in the numbers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Tencent Holdings story tilts cautious, so do not just rely on headlines and ratios. Move quickly and review the underlying data yourself. To see what optimistic investors are focusing on right now, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Tencent Holdings?
If Tencent Holdings has sharpened your thinking, broaden your watchlist now. Fresh ideas often show up where most investors are not yet looking.
- Target potential mispricing by scanning the 193 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Prioritise resilience by checking the list of solid balance sheet and fundamentals (197 results) that aim to keep debt in check and financial flexibility intact.
- Hunt for future market leaders early by reviewing the 603 high quality undiscovered gems before attention and capital crowd in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com