
Match Group’s (NASDAQ:MTCH) Q3 2026 earnings results: revenue in line with expectations but payers fall
Dating app company Match (NASDAQ:MTCH) met Wall Street’s revenue expectations in Q3 2026, but revenue fell by 2.5% year on year to $891.2 million. The company expects next quarter’s revenue to be around $870 million, close to analysts’ consensus estimates. Its GAAP profit of $0.73 per share was 2.1% above analysts’ consensus estimates.
For more on Match Group, read our free full research report.
Match Group (MTCH) Q3 2026 highlights:
- Revenue $891.2 million vs S&P analysts’ consensus estimates of $892.8 million (2.5% year-on-year decline, in line)
- EPS (GAAP) $0.73 vs analysts’ consensus estimates of $0.71 (2.1% beat)
- Adjusted EBITDA $344.5 million vs analysts’ consensus estimates of $331.9 million (38.7% margin, 3.8% beat)
- Revenue guidance $870 million at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- EBITDA guidance $330 million at the midpoint for Q4 2026, in line with analyst expectations
- Operating margin 30.1%, up from 24.2% in the same quarter last year
- Free cash flow margin 34.2%, down from 41.3% in the previous quarter
- Payers 13.8 million, down 727,000 year on year
- Market capitalization $9.51 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Match Group’s revenue grew at a sluggish 2% compounded annual growth rate over the last three years. That result fell short, but there are still things to like about Match Group.
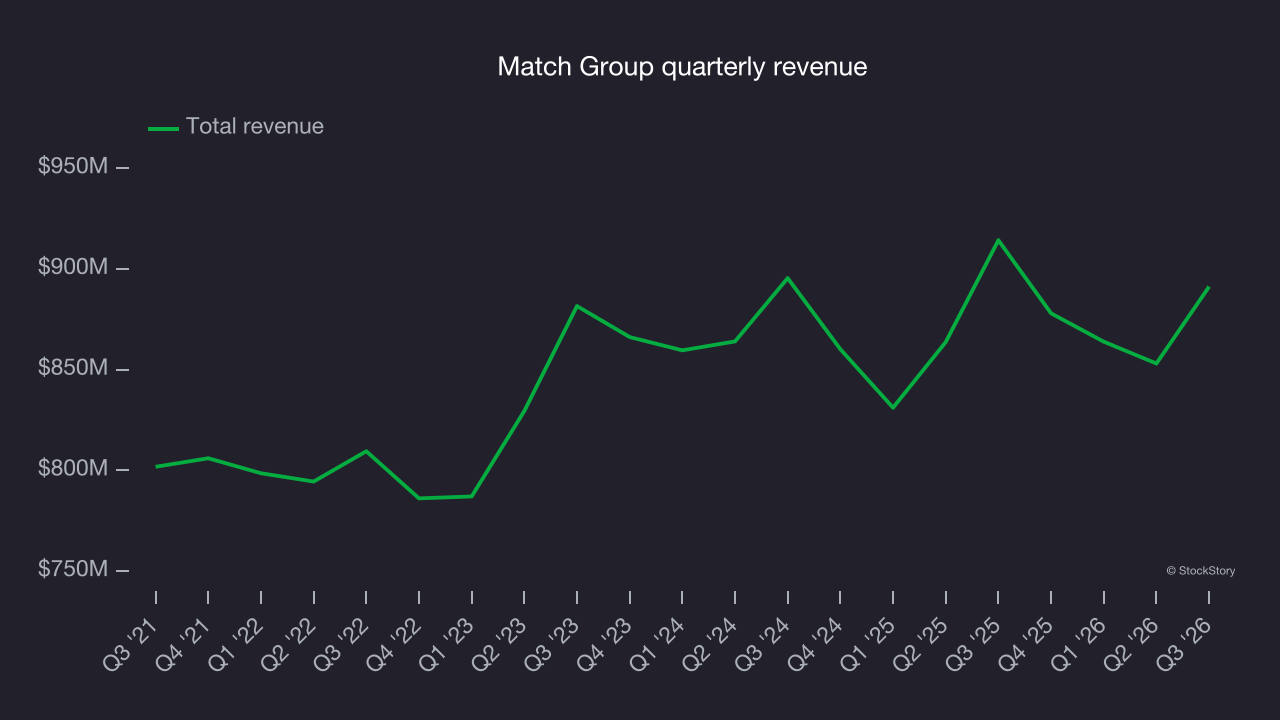
This quarter, Match Group reported an uninspiring 2.5% year-on-year revenue decline to $891.2 million, in line with Wall Street’s consensus estimates. Management is guiding for flat revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 2.2% over the next 12 months, according to S&P, similar to its three-year rate. This projection is underwhelming and indicates its newer products and services will not accelerate its top-line performance yet. Still, the company is tracking well in other measures of financial health.
Payers
User growth
As a subscription-based app, Match Group generates revenue growth by expanding both its subscriber base and the amount each subscriber spends over time.
Match Group struggled with new customer acquisition over the last two years as its payers declined by 4.8% annually to 13.8 million in the latest quarter. The decline is a concern because internet usage is secular, meaning there are typically unaddressed market opportunities. If Match Group wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 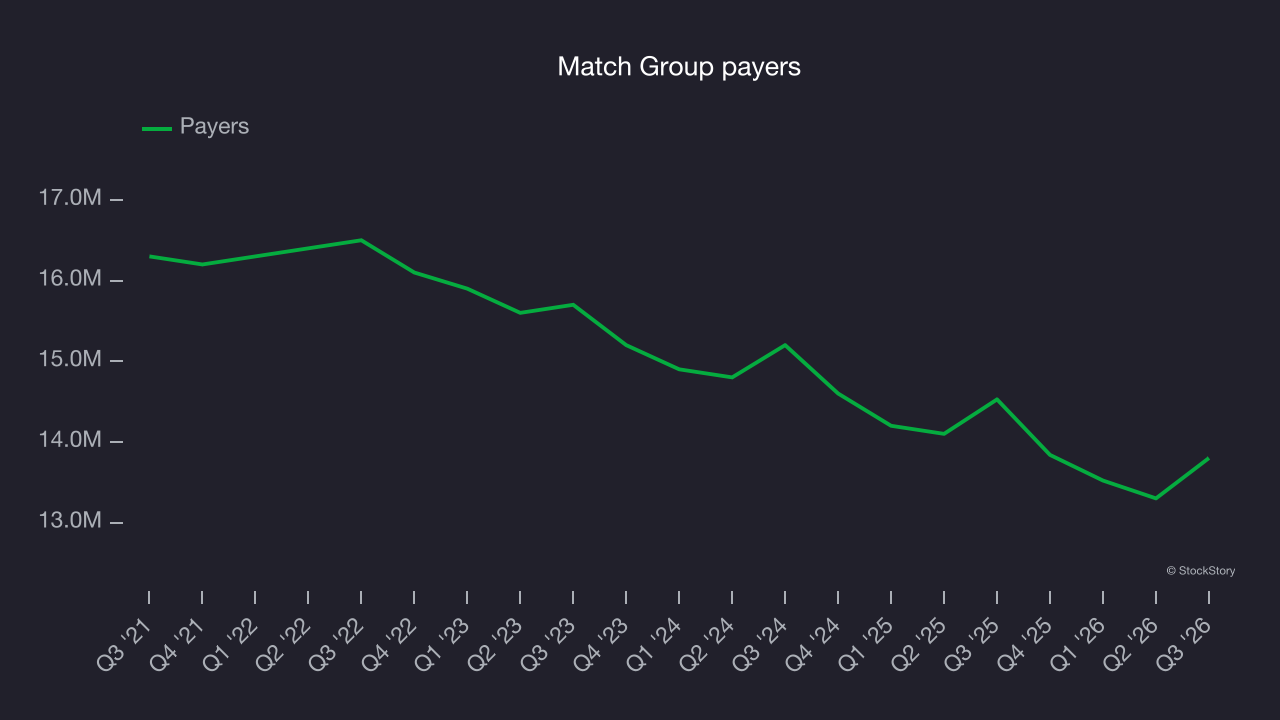
In Q3, Match Group’s payers once again decreased by 727,000, a 5% drop since last year. The quarterly result is similar to its two-year trend, suggesting its new initiatives aren’t accelerating user growth yet.
Revenue per user
Average revenue per user, or ARPU, is a critical metric to track because it measures how much the average user spends. ARPU is also a key indicator of how valuable its users are and can become over time.
Match Group’s ARPU growth has been decent over the last two years, averaging 5.2%. Although its payers shrank during this time, the company’s ability to increase monetization demonstrates its platform’s value for existing users. 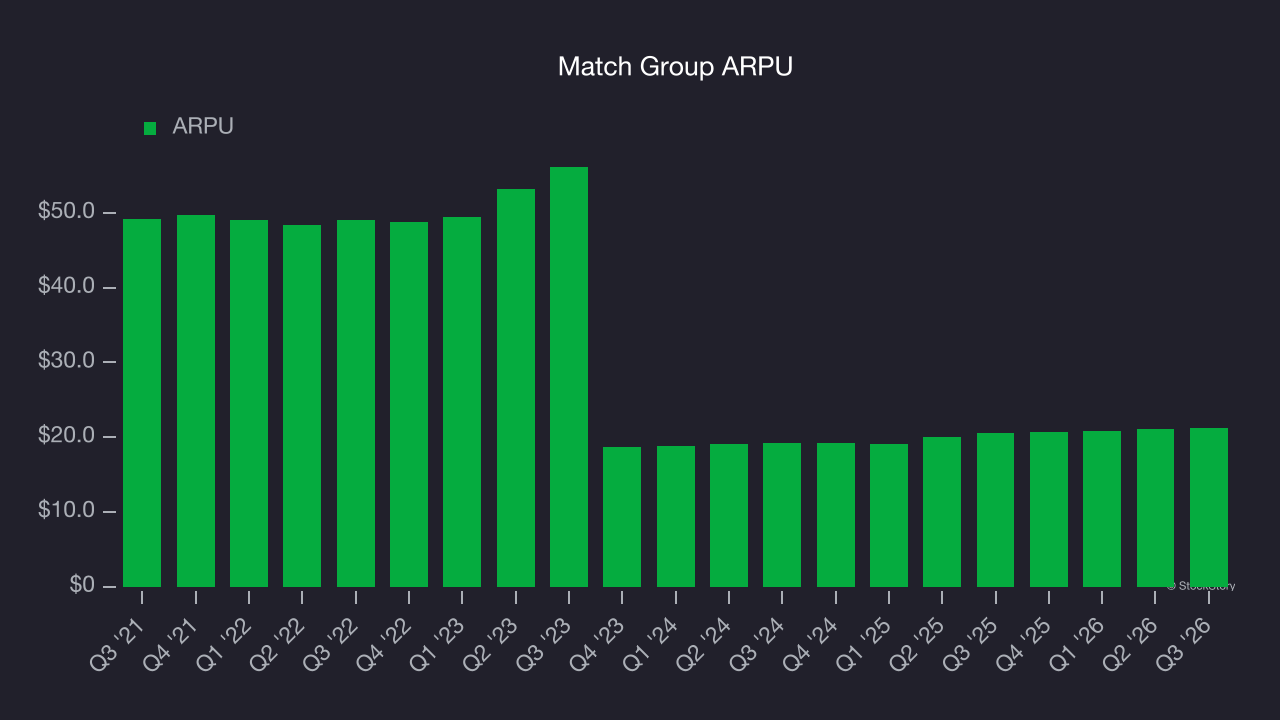
This quarter, Match Group’s ARPU was $21.19. It grew by 3% year on year, faster than its payers.
Key takeaways from Match Group’s Q3 results
Match Group’s EBITDA beat was a positive in an otherwise weaker quarter. Its user count declined, and revenue guidance for next quarter was in line with Wall Street’s consensus estimates. Shares edged lower 1.6% to $41.41 immediately after the report.
Should you invest in Match Group? The latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest. Read our full research report here (it’s free).